
- Home
- »
- Advanced Interior Materials
- »
-
Carbon-negative Textile Fibers Market Size Report, 2033GVR Report cover
![Carbon-negative Textile Fibers Market (2026 - 2033)Report]()
Carbon-negative Textile Fibers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Fiber Type (Hemp Fiber, Regenerative Fibers, Algae-based Fibers), By Fiber Form (Staple Fibers, Filament Fibers), By Application, By Region, And Segment Forecasts
Market Size, 2025
$138.6MMarket Estimate, 2026
$156.8MMarket Forecast, 2033
$373.6MCAGR, 2026–2033
13.2%Carbon-negative Textile Fibers Market Summary
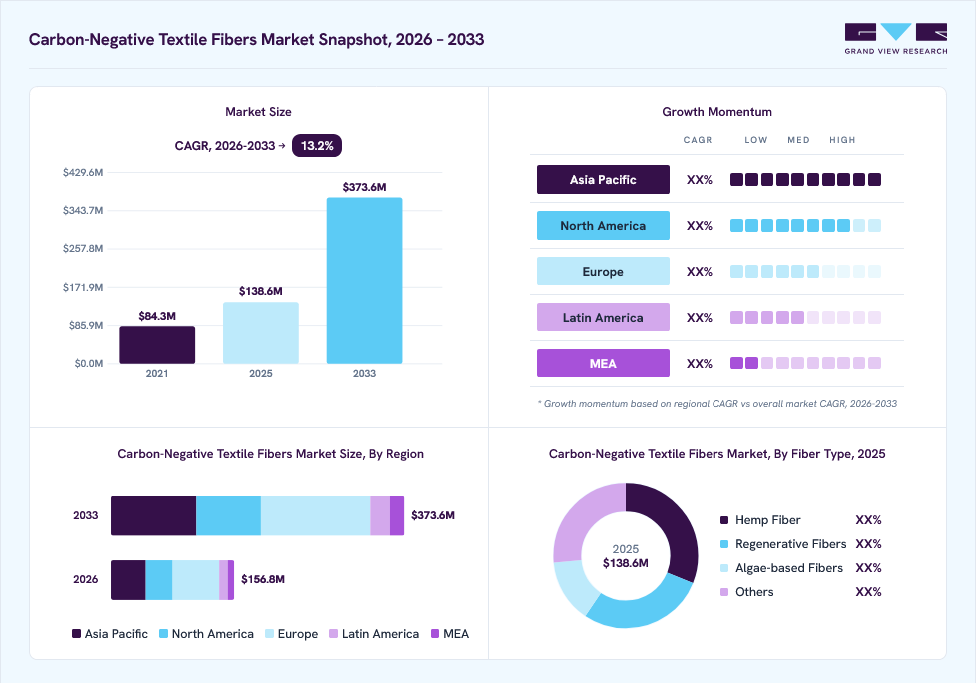
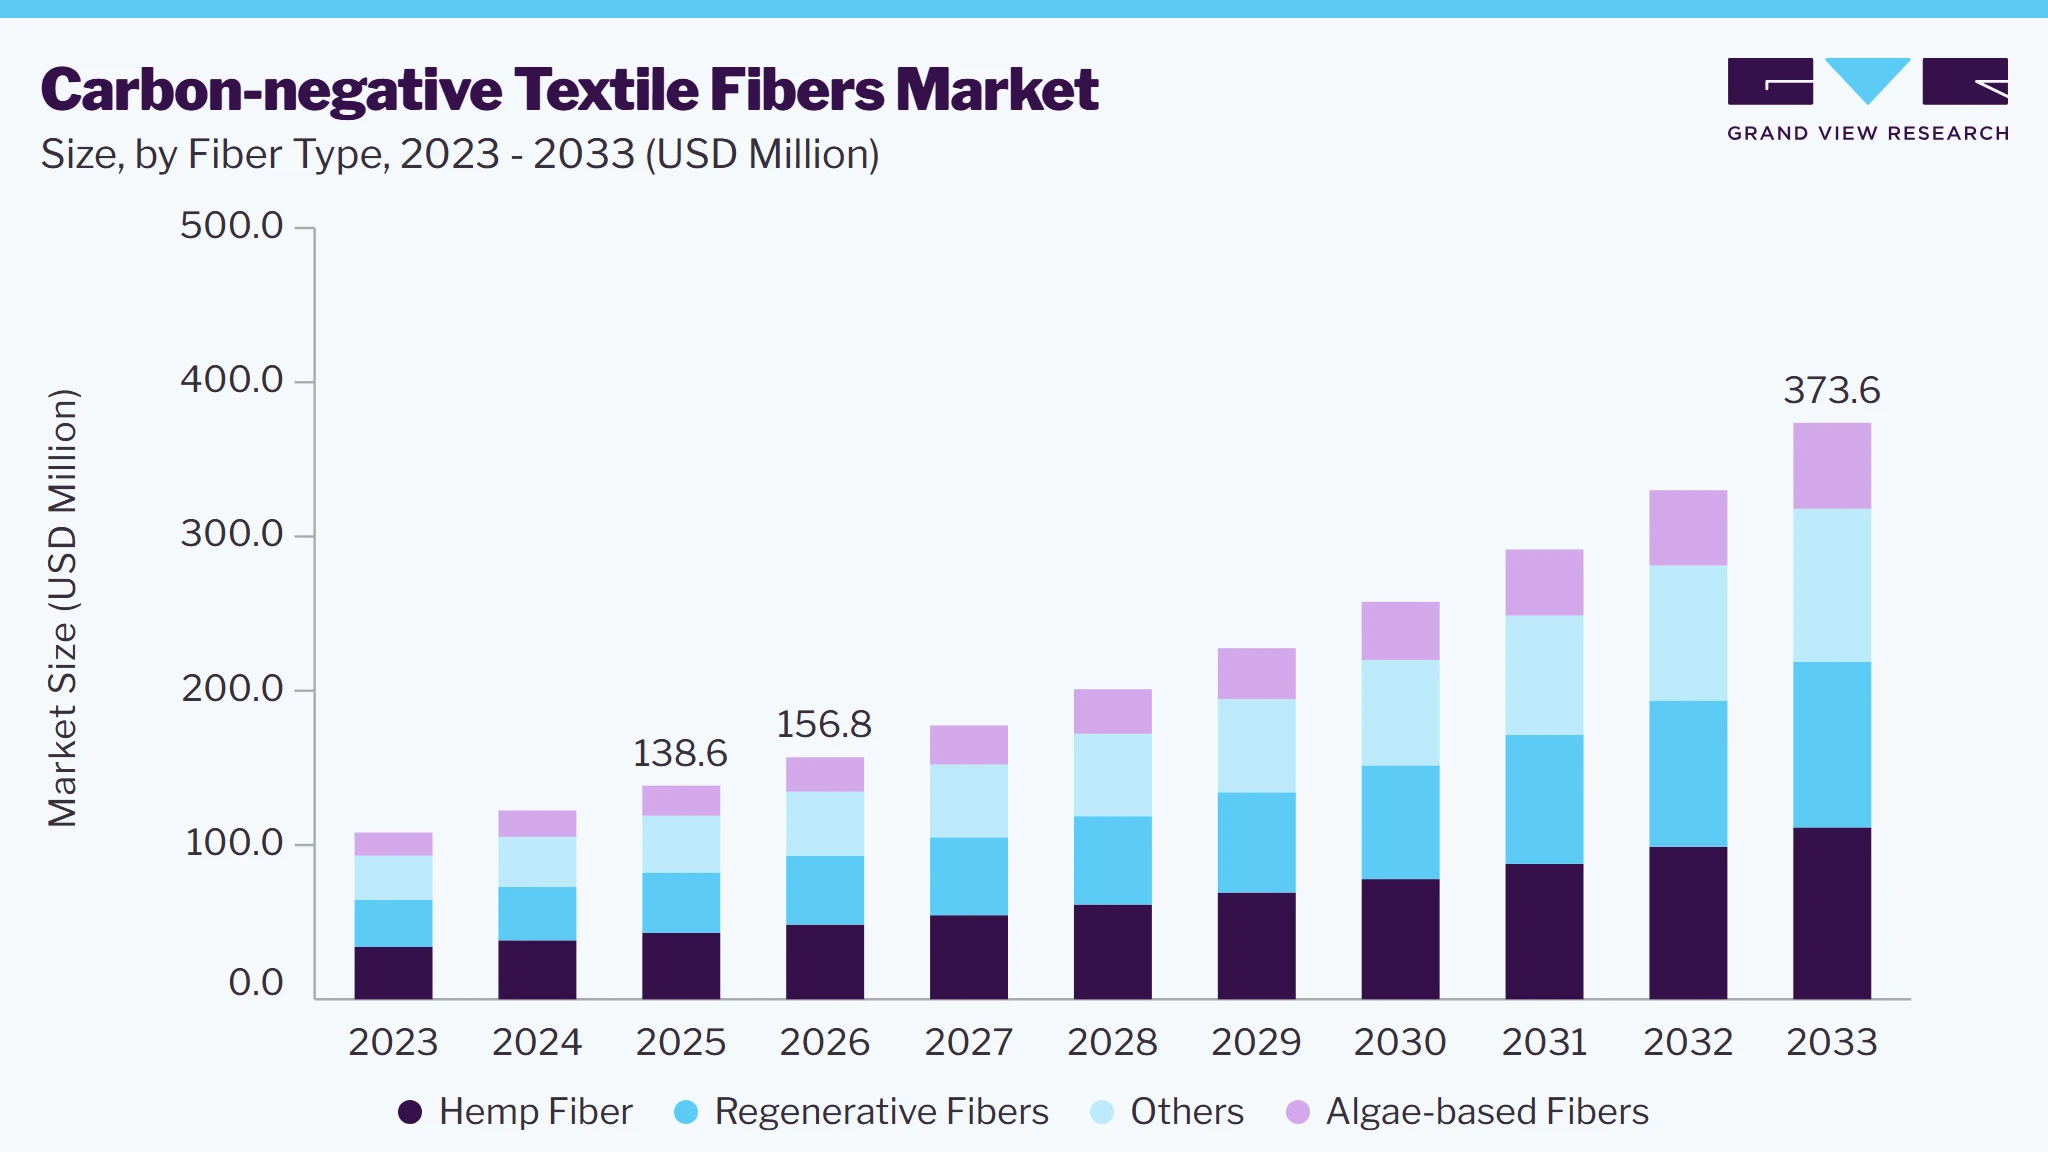
The global carbon-negative textile fibers market size was valued at USD 138.6 million in 2025 and is projected to grow from USD 156.8 million in 2026 to USD 373.6 million by 2033, at a CAGR of 13.2% from 2026 to 2033. Europe dominated the market, accounting for the largest revenue share of 37.9% in 2025. The market is emerging as a high-potential segment within the broader sustainable and bio-based textile industry, driven by increasing efforts to reduce greenhouse gas emissions across the textile value chain.
Key Market Trends & Insights
- By fiber type: The hemp fiber segment held the largest market share of 31.0% in 2025.
- By fiber form: The staple fibers segment held the largest market share of 65.3% in 2025.
- By application: The apparel segment held the largest market share of 47.5% in 2025.
Regional Highlights
- Largest regional market: Europe (37.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The Germany dominated Europe with the largest revenue share in 2025
Market Size & Forecast
- Market size in 2025: USD 138.6 million
- Estimated market size in 2026: USD 156.8 million
- Projected market size by 2033: USD 373.6 million
- CAGR (2026-2033): 13.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Carbon-negative textile fibers are materials designed to achieve a net removal of atmospheric carbon dioxide when their entire production and carbon storage pathways are considered. Unlike conventional synthetic fibers that depend heavily on fossil-based feedstocks, these fibers can utilize regenerative crops, agricultural residues, biomass, and other renewable resources.
Growing pressure on textile manufacturers and fashion brands to reduce their environmental footprint is supporting demand for lower-carbon fiber alternatives. Conventional textile fibers face scrutiny because of their dependence on fossil resources, energy-intensive processing, chemical use, and associated greenhouse gas emissions. Carbon-negative fiber development goes beyond simply reducing emissions by emphasizing carbon sequestration through regenerative cultivation, soil-carbon enhancement, biomass utilization, and long-term carbon storage.
Technological innovation is expanding the potential of carbon-negative fibers through regenerative agricultural practices, improved crop genetics, low-impact retting and decortication, mechanical fiber processing, advanced regenerated cellulose technologies, and biomass-based polymer production. Manufacturers are also investigating agricultural residues and underutilized biomass as feedstocks for regenerated fibers, thereby increasing resource utilization and reducing dependence on virgin fossil-based materials.
Market Dynamics
The market is being shaped by the transition from fossil-based textile materials toward renewable, regenerative, and circular feedstocks. Demand from apparel brands, textile manufacturers, home-textile producers, and technical-textile companies is increasing as sustainability commitments increasingly encompass raw-material sourcing and fiber form-level carbon footprints. However, the market remains relatively emerging because carbon-negative certification methodologies, reliable feedstock supply, processing infrastructure, and commercial-scale production capabilities are still developing.
The growing adoption of regenerative agricultural practices is one of the strongest drivers of market growth. Crops such as hemp and flax can absorb atmospheric carbon during cultivation while providing renewable feedstocks for textile applications. Hemp has attracted particular attention for its potential to sequester carbon, improve soil health, support versatile agricultural applications, and enable the production of natural and regenerated fibers. Integrating regenerative farming with fiber production allows textile manufacturers to address both upstream agricultural emissions and raw-material dependence.
The development of carbon-focused agricultural supply chains is further strengthening the commercial potential of these fibers. Farmers, fiber processors, textile manufacturers, and brands are increasingly exploring models that consider carbon sequestration, soil improvement, biodiversity, and the production of renewable materials together. New companies are also developing vertically integrated supply chains that combine regenerative cultivation, proprietary fiber processing, and mill-ready materials, particularly for hemp, flax, and other bast fibers. Such models can improve traceability and provide manufacturers with greater confidence regarding the environmental attributes of their raw materials.
The lack of universally consistent methodologies for determining whether a textile fiber is genuinely carbon-negative remains a major market restraint. Carbon sequestration occurs at different stages of cultivation and fiber form use, while emissions arise from fertilizers, agricultural machinery, transportation, retting, fiber processing, spinning, dyeing, and manufacturing. The duration for which biogenic carbon remains stored also influences the overall carbon balance. Consequently, companies need comprehensive life-cycle assessments and credible carbon-accounting methodologies before making carbon-negative claims.
Agricultural residues represent a significant opportunity for the market, as they can provide textile feedstocks without requiring additional land for fiber cultivation. Residues from hemp, flax, banana, pineapple, sugarcane, corn, and other agricultural activities can potentially be processed into natural, regenerated, or bio-derived fibers. Utilizing these materials can improve whole-crop economics, reduce agricultural waste, and create additional value from existing biomass streams. Hemp-based regenerated cellulose, for example, has been investigated as a pathway for converting residual biomass into higher-value textile fibers.
Market Concentration & Characteristics
The carbon-negative textile fibers industry is currently characterized by an emerging and relatively fragmented competitive structure. The market includes established fiber manufacturers, regenerative agriculture companies, natural-fiber processors, regenerated-cellulose producers, biotechnology companies, material innovators, and textile brands developing proprietary sourcing models. Competition is increasingly shifting from basic fiber production toward measurable carbon performance, traceable feedstock sourcing, regenerative agriculture partnerships, and scalable processing technologies.
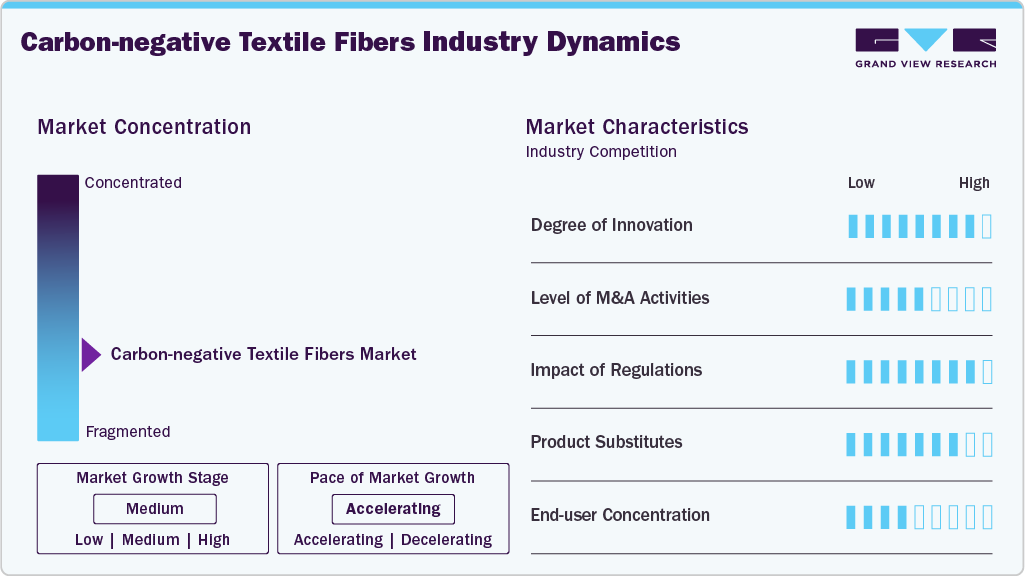
The market faces competition from conventional natural fibers, recycled textile fibers, bio-based synthetic fibers, regenerated cellulose fibers, recycled polyester, and other low-carbon textile materials. Conventional cotton, polyester, viscose, lyocell, recycled fibers, and emerging bio-based polymers can satisfy many of the same apparel and textile requirements. The threat is particularly relevant because not every sustainable textile application requires carbon-negative materials. Nevertheless, carbon-negative fibers offer a differentiated proposition by combining material functionality with the potential for atmospheric carbon removal, providing an advantage as brands and consumers increasingly prioritize measurable climate benefits.
Analyst Perspective
The carbon-negative textile fibers market represents an emerging transition from lower-impact textile materials toward materials capable of delivering measurable carbon-removal benefits. Hemp, flax, regenerative natural fibers, agricultural-residue fibers, and biomass-derived regenerated cellulose are expected to form important technology pathways. However, the market's long-term credibility will depend on rigorous carbon accounting rather than the bio-based origin of a fiber alone. The strongest commercial opportunities are expected to arise where carbon sequestration is combined with competitive fiber performance, scalable processing, traceable sourcing, and compatibility with existing textile manufacturing infrastructure.
Fiber Type Insights
The hemp fiber segment led the market with the largest revenue share of 31.0% in 2025, supported by hemp’s strong carbon-sequestration potential, renewable nature, and suitability for producing durable textile fibers. The increasing adoption of hemp-based materials in apparel, home textiles, and technical applications, along with growing interest in regenerative agriculture and a reduced reliance on conventional synthetic fibers, is further strengthening demand in the segment.
The algae-based fibers segment is expected to grow at the fastest CAGR of 14.0% over the forecast period, as manufacturers explore innovative biological feedstocks to reduce dependence on fossil-based textile materials. Algae offers opportunities to develop bio-based fibers by utilizing rapidly renewable biomass and supporting lower-impact production processes. Increasing R&D investments, advancements in algae cultivation and fiber-processing technologies, and growing demand for novel sustainable materials are expected to support future adoption.
Fiber Form Insights
The staple fibers segment led the market with the largest revenue share of 65.3% in 2025, driven by their broad use in spinning, blending, and production of apparel and textile fabrics. Their compatibility with existing textile manufacturing processes allows carbon-negative and bio-based fibers to be incorporated into conventional yarn and fabric production with relatively limited changes to downstream operations. Growing demand for sustainable apparel and blended natural-fiber textiles is further supporting segment adoption.
The filament fibers segment is expected to grow at the fastest CAGR of 13.6% over the forecast period, as textile manufacturers increasingly seek continuous fibers offering strength, smoothness, consistency, and suitability for high-performance applications. Advances in carbon-negative polyester, bio-based polymers, and regenerated cellulose technologies are expanding the potential for sustainable filament production. Increasing demand for sustainable sportswear, technical textiles, and performance fabrics is expected to further drive adoption.
Application Insights
The apparel segment led the market with the largest revenue share of 47.5% in 2025, driven by rising demand for sustainable clothing and growing efforts by fashion brands to reduce the carbon footprint of textile supply chains. Carbon-negative fibers provide apparel manufacturers with opportunities to incorporate climate-positive material attributes into garments while meeting consumer expectations for renewable and environmentally preferable materials. Increasing sustainability commitments across the fashion industry are further supporting adoption.
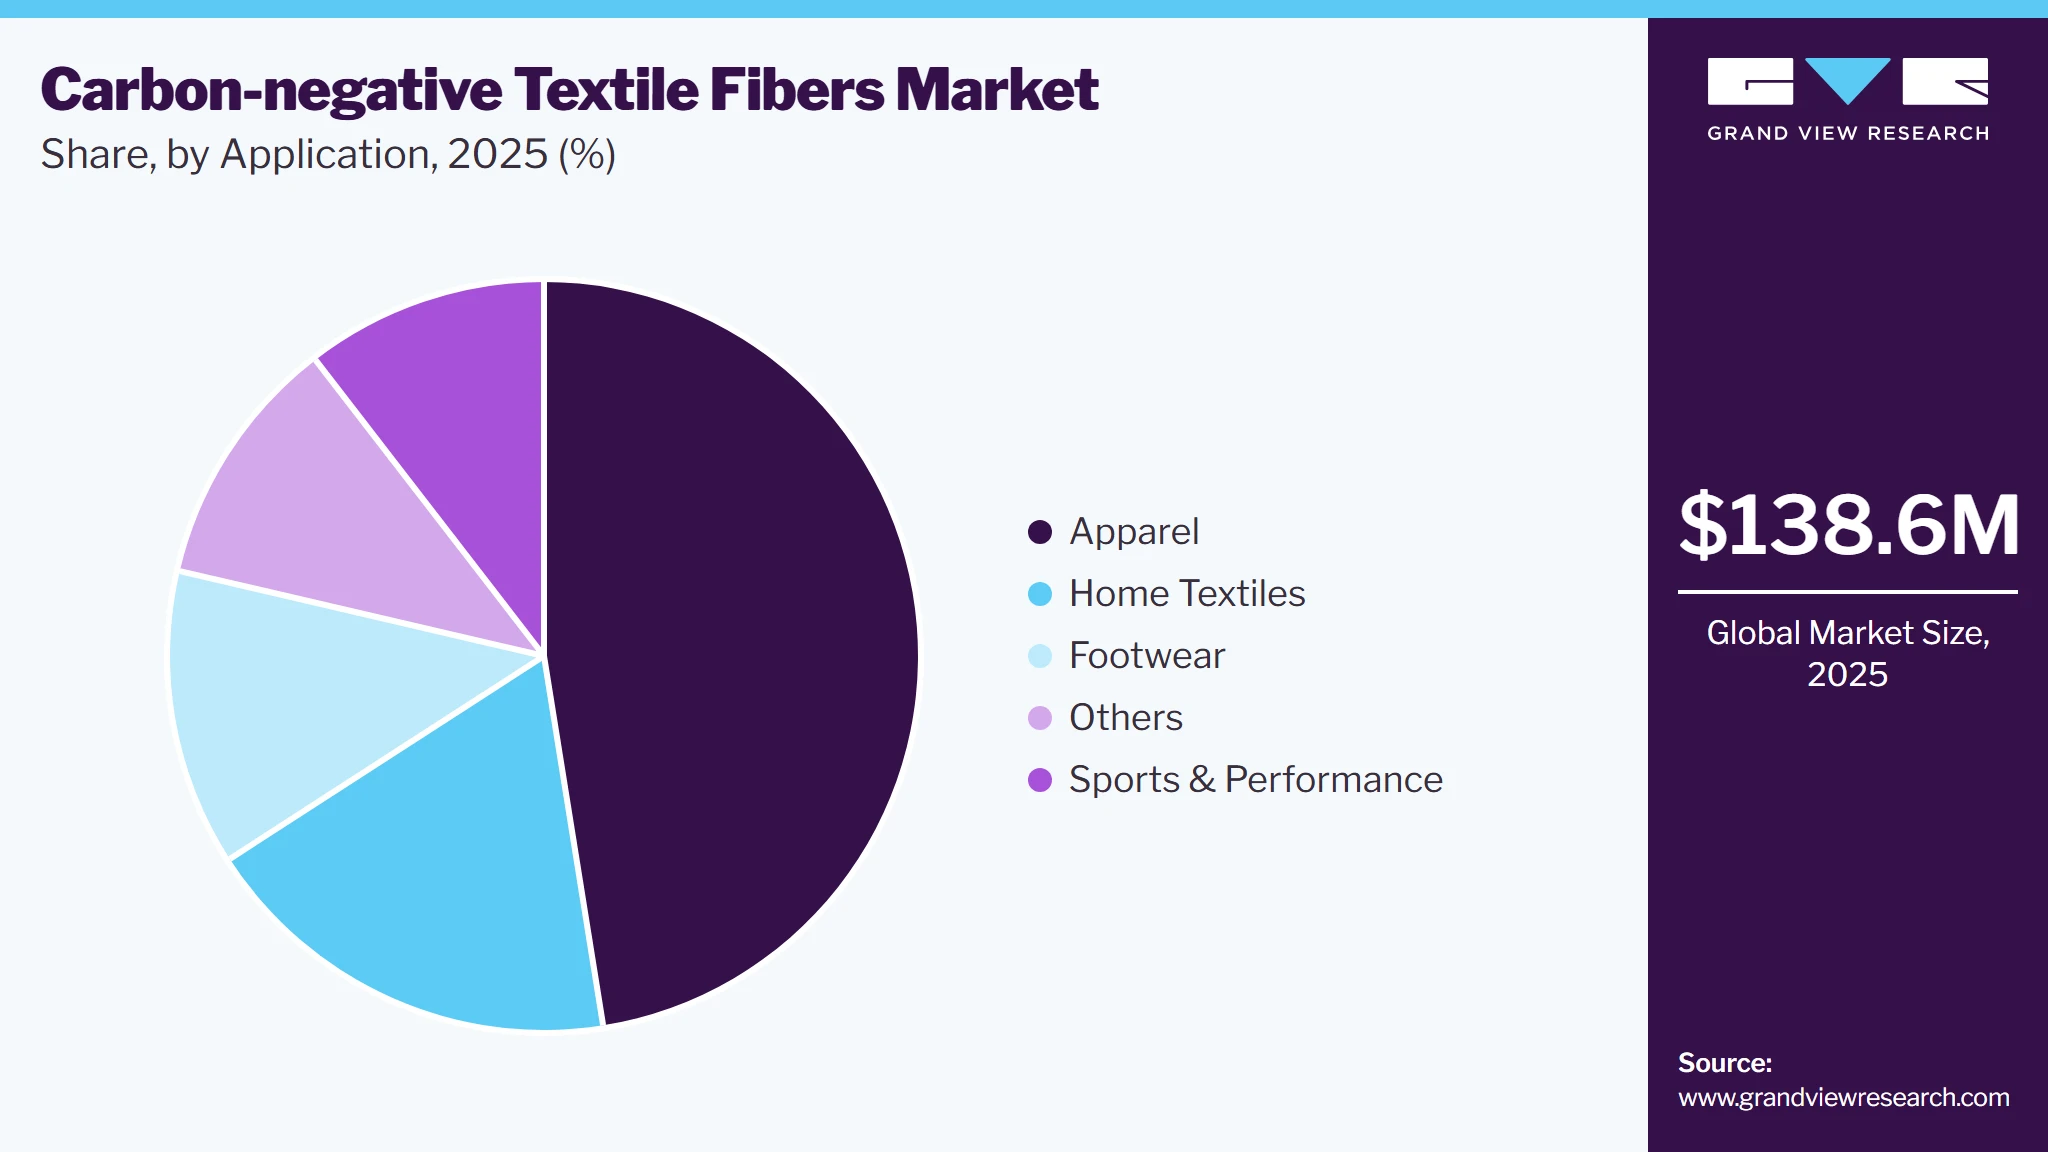
The sports & performance segment is expected to grow at the fastest CAGR of 14.0% over the forecast period, as manufacturers seek textile fibers that combine sustainability with durability, lightweight construction, moisture management, breathability, and high-performance characteristics. Carbon-negative fibers are increasingly being explored for sportswear, outdoor clothing, footwear, and performance accessories. Growing consumer interest in sustainable activewear and increasing investments by brands in lower-carbon performance materials are expected to create strong growth opportunities.
Regional Insights
The carbon-negative textile fibers market in North America is driven by growing demand for sustainable apparel, regenerative agriculture, traceable supply chains, and climate-oriented materials. The region has growing interest in industrial hemp, agricultural-residue utilization, bio-based materials, and carbon sequestration initiatives. Textile brands and material innovators are evaluating fiber alternatives based on life-cycle emissions, renewable content, biodegradability, and carbon-storage potential. Collaboration among agricultural producers, biotechnology companies, textile manufacturers, and fashion brands is expected to support commercialization and supply chain development.
U.S. Carbon-negative Textile Fibers Market Trends
The carbon-negative textile fibers market in the U.S. is expected to play an important role in the development of carbon-negative textile fibers through its agricultural resources, material-innovation ecosystem, and growing interest in regenerative agriculture. Footwear, hemp, and agricultural residues offer potential feedstocks for natural and regenerated fibers, while research institutions and material companies are developing technologies to improve fiber quality and scalability. Consumer interest in sustainable fashion and corporate climate commitments is also encouraging brands to investigate materials with lower environmental impacts.
Europe Carbon-negative Textile Fibers Market Trends
The Europe carbon-negative textile fibers market held the largest revenue share of 37.9% in 2025, due to its strong sustainability agenda, circular-economy policies, environmental fiber-form requirements, and established sustainable fashion ecosystem. Textile companies are increasingly evaluating raw materials based on carbon emissions, resource consumption, recyclability, and end-of-life performance. European research and industrial initiatives are also supporting flax, hemp, regenerated cellulose, agricultural residues, and other bio-based feedstocks.
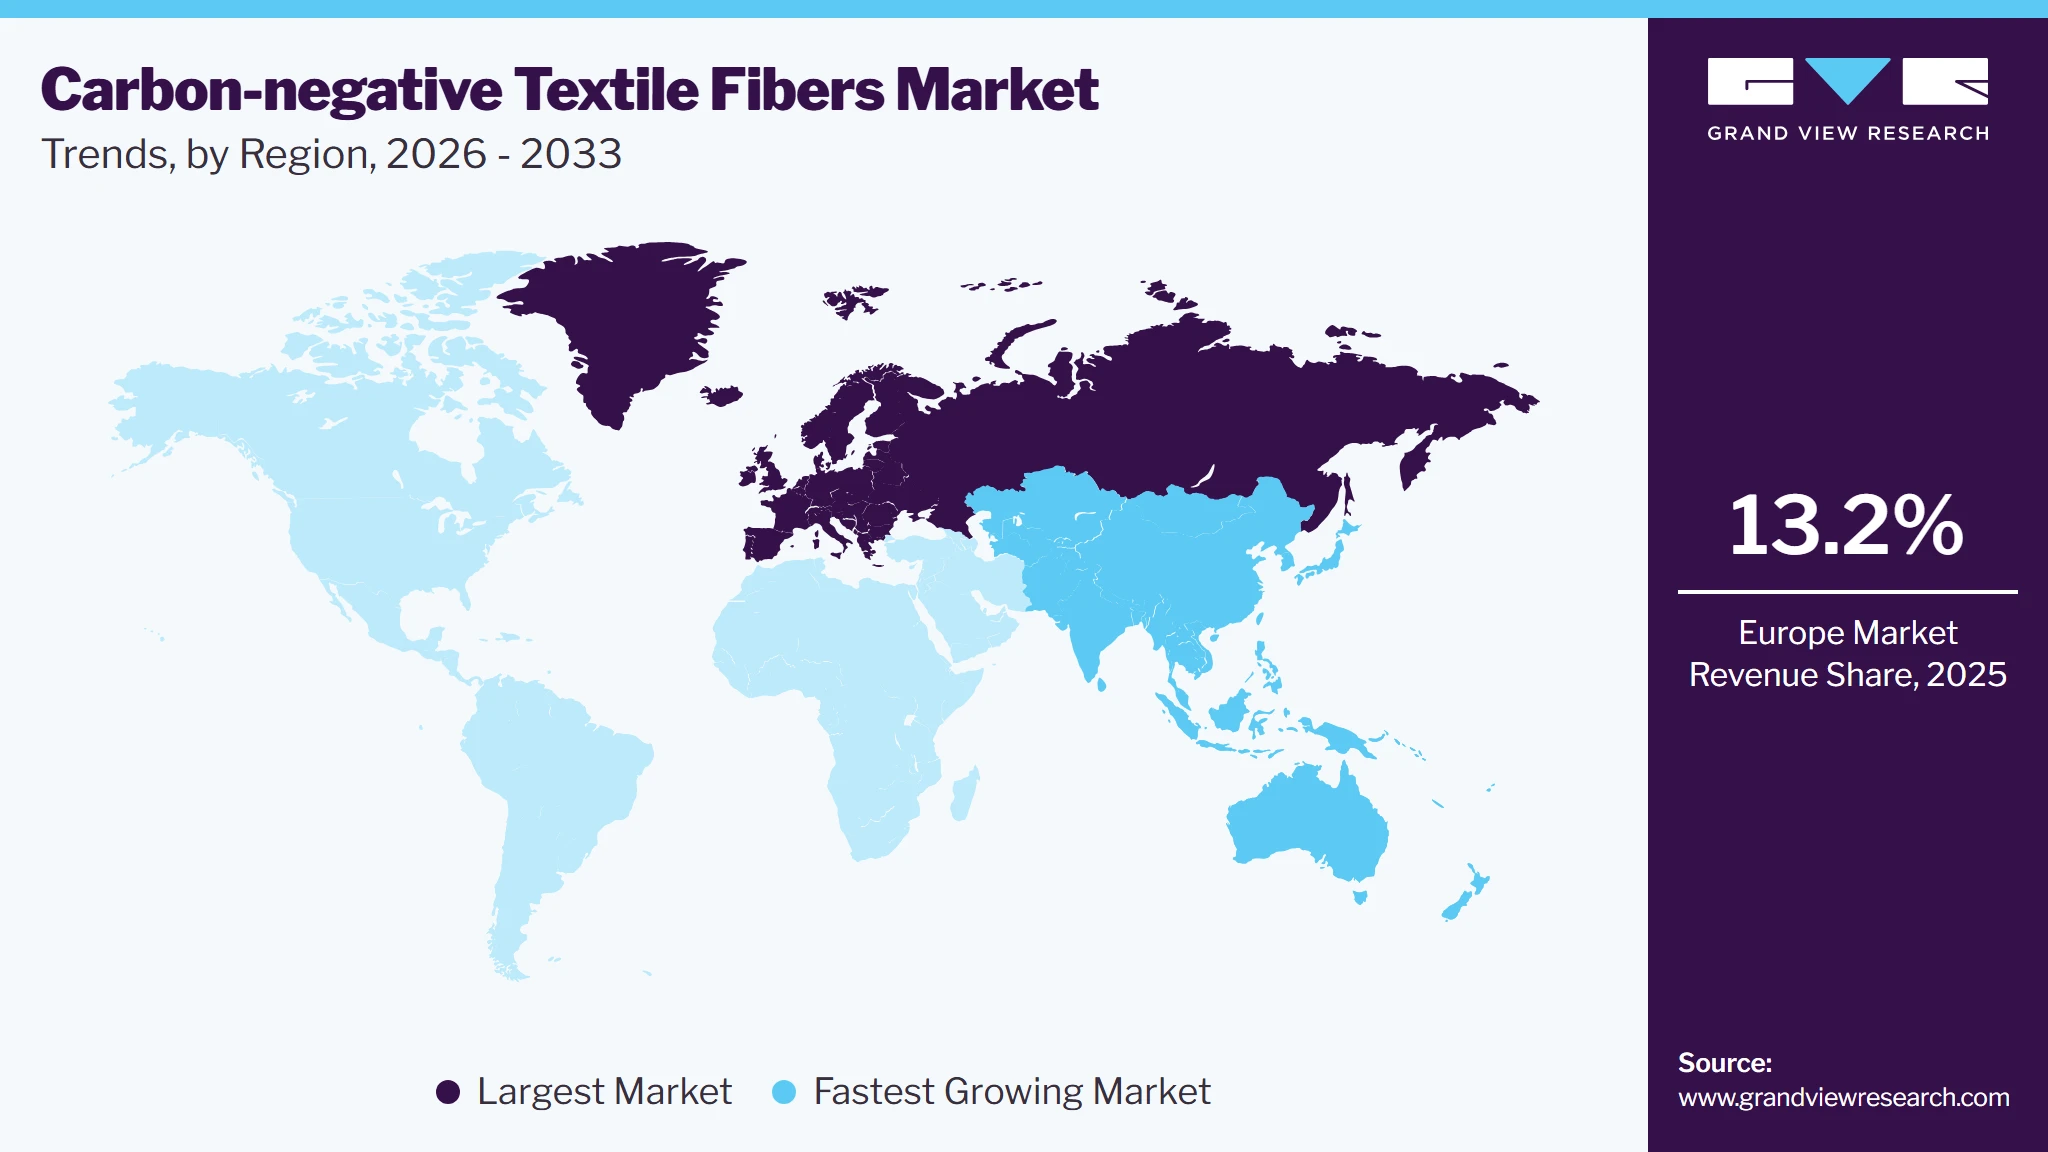
The carbon-negative textile fibers market in Germany accounted for the largest revenue share in Europe in 2025, driven by its advanced textile machinery industry, research capabilities, sustainability-focused manufacturing sector, and strong emphasis on circular economy principles. Companies are investigating renewable fibers, recycled materials, bio-based polymers, and efficient textile-processing technologies. Germany's industrial ecosystem offers opportunities to scale innovative fiber-processing technologies and to integrate carbon accounting into textile supply chains. Demand from technical textiles, apparel manufacturers, automotive textiles, and sustainable consumer-fiber form companies can support the adoption of carbon-negative materials.
Asia Pacific Carbon-negative Textile Fibers Market Trends
The carbon-negative textile fibers market in the Asia Pacific is anticipated to grow at the fastest CAGR during the forecast period. Asia Pacific is expected to remain a major region for carbon-negative textile fiber development because of its extensive textile manufacturing infrastructure, large agricultural base, growing apparel industry, and increasing focus on sustainability. Countries across the region have established ecosystems for fiber, yarn, fabric, and garment manufacturing that can facilitate the integration of emerging sustainable fibers into existing supply chains. China, India, Japan, South Korea, and Southeast Asian countries are increasingly exploring bio-based and circular textile materials.
The China carbon-negative textile fibers market held a significant share in the Asia Pacific in 2025, due to its extensive textile manufacturing ecosystem, established synthetic and regenerated fiber production capabilities, and growing interest in sustainable materials. Manufacturers are increasingly exploring bio-based feedstocks, regenerated cellulose, agricultural residues, and advanced fiber-processing technologies. The country's large-scale textile supply chain offers opportunities to integrate carbon-negative fibers into spinning, weaving, knitting, and garment production. Greater emphasis on industrial decarbonization and circular resource utilization is also expected to support research and commercialization of lower-carbon textile materials.
Central and South America Carbon-negative Textile Fibers Market Trends
The carbon-negative textile fibers market in Central and South America is driven by its agricultural resources, biodiversity, biomass availability, and expanding sustainable materials ecosystem. Countries such as Brazil can provide feedstocks from agricultural residues and plant-based resources for natural and regenerated fibers. The region also has opportunities to connect regenerative farming practices with textile manufacturing and export-oriented apparel supply chains. However, infrastructure gaps, inconsistent processing capabilities, and the need for improved traceability can influence the speed of commercial adoption.
Middle East & Africa Carbon-negative Textile Fibers Market Trends
The carbon-negative textile fibers market in the Middle East & Africa region presents emerging opportunities for carbon-negative textile fibers through agricultural-residue utilization, sustainable farming, local textile manufacturing, and diversification of bio-based material supply chains. Countries with established cotton and textile industries can explore lower-carbon alternatives and value-added processing of agricultural biomass. In Africa, regenerative agriculture and locally sourced natural fibers can provide opportunities to develop sustainable textile value chains while supporting rural economic development.
Key Carbon-negative Textile Fibers Company Insights
Some of the key players operating in the market include Universal Fibers and Origin Materials
-
Universal Fibers is a U.S.-based fiber manufacturer specializing in advanced synthetic and sustainable fibers for applications including flooring, textiles, and performance materials. The company is particularly relevant to the carbon-negative textile fibers industry through its development of Thrive, a carbon-negative nylon fiber designed to reduce the carbon footprint of textile products.
-
Origin Materials is a U.S.-based materials technology company developing carbon-negative materials and polymers from renewable carbon sources. Its technology platform is designed to replace fossil-based feedstocks with renewable carbon and is being applied to produce materials suitable for PET, polyester fibers, and other textile applications.
AECI SANS Technical Fibers and Renaissance Fiber are some of the emerging market participants in the carbon-negative textile fibers industry.
-
AECI SANS Technical Fibers is a U.S.-based technical fiber manufacturer specializing in high-performance fibers and yarns for demanding industrial and textile applications. The company has collaborated with Origin Materials to develop carbon-negative PET-based fibers and technical yarns, supporting the commercialization of next-generation, lower-carbon textile materials.
-
Renaissance Fiber is a U.S.-based fiber technology company focused on developing natural and regenerative fiber materials. Its proprietary approach uses plant-based biological processes and carbon sequestration to produce textile fiber solutions focused on carbon-negative manufacturing and regenerative material production.
Key Carbon-negative Textile Fibers Companies
The following key companies have been profiled for this study on the global carbon-negative textile fibers market.
-
Universal Fibers
-
Origin Materials
-
Rubi Laboratories
-
CarbonYarn
-
Fairbrics
-
Handa Industries
-
Renaissance Fiber
-
AECI SANS Technical Fibers
-
PrimaLoft
-
SEFF
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players: (Universal Fibers, Origin Materials, Rubi Laboratories, CarbonYarn, Fairbrics, Handa Industries)
- Invest in developing and commercializing carbon-negative textile fibers using carbon capture, bio-based feedstocks, renewable carbon, and carbon-to-material technologies.
- Expand product portfolios across carbon-negative nylon, polyester, cellulose, regenerated fibers, and other textile applications to address demand for lower-carbon materials.
- Strengthen manufacturing capabilities and strategic partnerships with textile mills, apparel brands, fiber manufacturers, technology providers, and carbon-capture companies to accelerate commercialization.
- Established technology capabilities, intellectual property, and specialized expertise in carbon-negative and carbon-utilization technologies provide differentiation.
- Strong relationships and collaborations across the textile, polymer, carbon capture, and materials industries support technology development and market access.
- Proprietary processes for converting captured carbon or renewable feedstocks into textile materials provide opportunities to achieve substantially lower carbon footprints than conventional fossil-based fibers.
- High development and commercialization costs associated with carbon-capture integration, specialized processing technologies, and new fiber manufacturing infrastructure.
- Dependence on access to reliable CO₂ capture, renewable feedstocks, energy, and specialized manufacturing infrastructure can create supply chain constraints.
- Several technologies remain at pilot or early commercialization stages, creating challenges related to production scale, cost competitiveness, fiber performance, and consistent quality.
Emerging Players: (Renaissance Fiber, AECI SANS Technical Fibers, PrimaLoft, SEFF)
- Develop specialized carbon-negative and carbon-sequestering textile fiber solutions targeting apparel, outdoor textiles, technical textiles, insulation, and other performance-oriented applications.
- Expand through strategic partnerships with fiber producers, textile manufacturers, apparel brands, material innovators, and sustainable-product companies to accelerate adoption.
- Prioritize improvements in fiber performance, carbon footprint reduction, renewable content, scalability, traceability, and manufacturing efficiency to differentiate from conventional textile fibers.
- Strong specialization in carbon-negative, carbon-sequestering, and next-generation textile fiber technologies provides differentiation.
- Focused product development enables these companies to address sustainability requirements in performance textiles, apparel, insulation, and specialized applications.
- Strategic collaborations with established textile and material companies can provide access to manufacturing capabilities, distribution networks, and downstream brand relationships.
- Relatively smaller production scale and limited geographic reach compared with established global fiber manufacturers.
- Dependence on strategic partners, technology commercialization, specialized feedstocks, and manufacturing infrastructure can influence market expansion.
- Challenges remain around scaling production, reducing manufacturing costs, achieving consistent fiber performance, and demonstrating verified carbon-negative claims across the complete product life cycle.
Recent Developments
-
In July 2025, Universal Fibers partnered with Circular Building Solutions to accelerate flooring circularity through adhesive-free and reversible installation technologies. Its Thrive matter product remains positioned as a carbon-negative nylon fiber, available in Nylon 6 and Nylon 6,6.
-
In January 2025, PrimaLoft converted its flagship PrimaLoft Gold Insulation production to its P.U.R.E. manufacturing technology. The process reduces manufacturing carbon emissions by 50% or more compared with conventional production.
Carbon-negative Textile Fibers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 138.6 million
Estimated market size in 2026
USD 156.8 million
Projected market size by 2033
USD 373.6 million
Growth rate
CAGR of 13.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Fiber type, fiber form, application, region
Regional scope
North America; Europe; Asia Pacific; Central and South America; Middle East and Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Saudi Arabia
Key companies profiled
Universal Fibers; Origin Materials; Rubi Laboratories; CarbonYarn; Fairbrics; Handa Industries; Renaissance Fiber; AECI SANS Technical Fibers; PrimaLoft; SEFF
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Carbon-negative Textile Fibers Market Report Segmentation
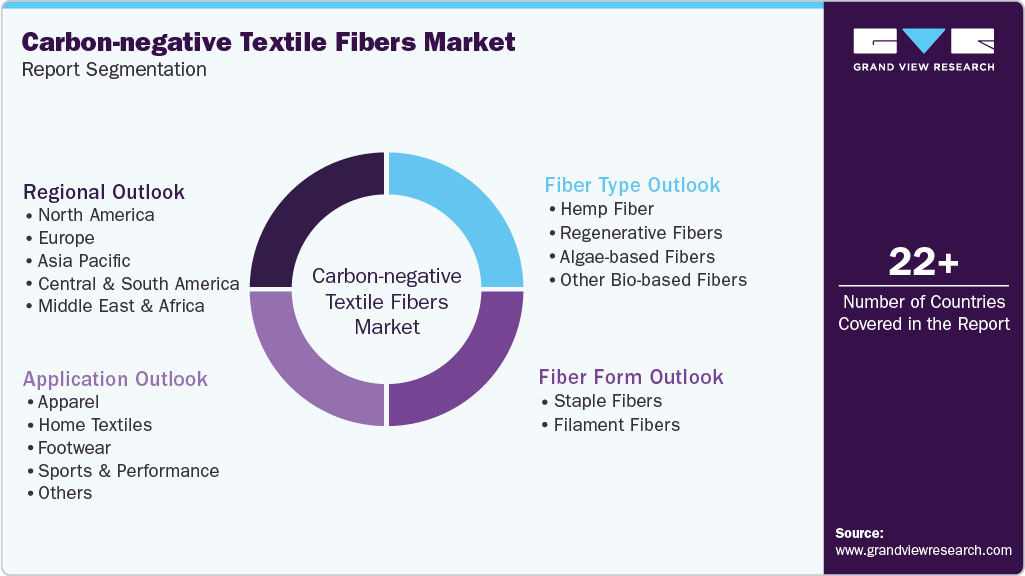
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global carbon-negative textile fibers market report based on the fiber type, fiber form, application, and region:
-
Fiber Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Hemp Fiber
-
Regenerative Fibers
-
Algae-based Fibers
-
Other Bio-based Fibers
-
-
Fiber Form Outlook (Revenue, USD Million, 2021 - 2033)
-
Staple Fibers
-
Filament Fibers
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Apparel
-
Home Textiles
-
Footwear
-
Sports & Performance
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central and South America
-
Brazil
-
-
Middle East and Africa
-
Saudi Arabia
-
-
Research Methodology
The carbon-negative textile fibers marketfigures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with the carbon-negative textile fibers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Fiber Type
Revenue Capture Definition
Hemp Fiber
Revenue generated from the sale of bamboo-based flooring fiber forms manufactured using bamboo as the primary renewable raw material, including engineered bamboo flooring, solid bamboo flooring, and related formats.
Regenerative Fibers
Revenue generated from the sale of linoleum flooring manufactured using bio-based materials such as linseed oil, natural resins, wood flour, cork dust, and other renewable components.
Algae-based Fibers
Revenue generated from the sale of cork-based flooring fiber forms manufactured using cork as the primary material, including cork tiles, planks, and other cork flooring formats.
Other Bio-based Fibers
Revenue generated from the sale of flooring fiber forms manufactured using polymers derived wholly or partially from renewable biological feedstocks, including bio-based resins and plant-derived polymer materials.
Other Fiber Types
Revenue generated from the sale of bio-based flooring fiber forms manufactured using other renewable materials, including natural fibers, agricultural residues, bio-based composites, wood-based materials, and other plant-derived resources.
Segment - Fiber Form
Revenue Capture Definition
Staple Fibers
Revenue generated from the sale of bio-based flooring fiber forms manufactured and supplied in plank formats, including interlocking, engineered, and other plank-based flooring systems.
Filament Fibers
Revenue generated from the sale of bio-based flooring fiber forms manufactured and supplied as individual tiles, including modular tiles made from cork, linoleum, bamboo, bio-based polymers, and other renewable materials.
Sheets / Rolls
Revenue generated from the sale of bio-based flooring fiber forms supplied in continuous sheet or roll formats, including linoleum, bio-based resilient flooring, and other flexible, renewable flooring materials.
Other Fiber Forms
Revenue generated from the sale of bio-based flooring fiber forms supplied in formats other than planks, tiles, or sheets/rolls, including specialty flooring systems and customized formats.
Segment - Application
Revenue Capture Definition
Apparel
Revenue generated from the sale of bio-based flooring fiber forms used in residential properties, including houses, apartments, condominiums, and other private living spaces.
Home Textiles
Revenue generated from the sale of bio-based flooring fiber forms used in commercial buildings and spaces, including offices, retail stores, hotels, restaurants, and other commercial establishments.
Footwear
Revenue generated from the sale of bio-based flooring fiber forms used in industrial facilities, including manufacturing plants, warehouses, processing facilities, and other industrial environments.
Sports & Performance
Revenue generated from the sale of bio-based flooring fiber forms used in institutional facilities, including schools, universities, hospitals, healthcare facilities, government buildings, and other public or institutional establishments.
Others
Revenue generated from the sale of bio-based flooring fiber forms used in other applications not classified under residential, commercial, industrial, or institutional applications, including specialized facilities and recreational spaces.
Estimation Model
Layer Name
Key Question
Description
Parent Market Analysis
What is the overall size and growth outlook of the global textile fibers, sustainable textiles, bio-based fibers, and carbon-neutral/low-carbon materials markets?
The estimation begins by evaluating the broader markets for textile fibers, sustainable textiles, bio-based fibers, regenerated fibers, and low-carbon materials. Apparel and textile production, demand for sustainable materials, availability of renewable feedstocks, climate commitments, and investments in circular and regenerative textile technologies are analyzed to establish the addressable market for carbon-negative textile fibers.
Carbon-Negative Textile Fiber Penetration Analysis
What proportion of the overall textile fiber and sustainable fiber market is represented by carbon-negative textile fibers?
This layer estimates the penetration of carbon-negative fibers across the categories of natural, bio-based, regenerated, and other carbon-sequestering textile fibers. Adoption is further assessed across fiber types, including hemp, flax, jute, bamboo, agricultural-residue-based fibers, regenerated cellulose, and other emerging carbon-negative materials.
Regional & End-use Demand Assessment
Which regions and end-use sectors contribute the highest demand for carbon-negative textile fibers?
Demand is assessed across major regions based on textile manufacturing activity, sustainable-fashion adoption, regenerative agriculture practices, environmental regulations, carbon-reduction commitments, renewable feedstock availability, and consumer awareness. Analysis covers apparel, home textiles, technical textiles, footwear, automotive textiles, industrial textiles, and other applications.
Company Revenue Validation & Market Forecasting
How is the final market size validated and forecast?
Estimates are validated using company revenues, fiber production capacities, fiber form portfolios, manufacturing facilities, feedstock sourcing, sustainability certifications, carbon-removal claims, investments, partnerships, fiber form launches, and capacity expansions. Bottom-up and top-down approaches are triangulated to develop reliable market estimates and forecasts.
Frequently Asked Questions About This Report
The carbon-negative textile fibers market size was estimated at USD 138.6 million in 2025 and is expected to reach USD 156.8 million in 2026.
The carbon-negative textile fibers market is expected to grow at a compound annual growth rate of 13.2% from 2026 to 2033 to reach USD 373.6 million by 2033.
The staple fiber segment accounted for the highest revenue share of 65.3% in 2025, due to its widespread use in apparel and textile manufacturing, along with its compatibility with conventional spinning and blending processes.
Europe held the highest revenue market share of 37.9% in 2025, due to strong sustainability regulations, growing adoption of bio-based and circular textiles, and increasing demand for low-carbon materials across the region.
Key factors driving the carbon-negative textile fibers market include rising pressure to reduce carbon emissions in the textile sector, growing adoption of renewable and regenerative feedstocks, increasing sustainability commitments from apparel brands, and advancements in carbon capture and bio-based fiber technologies.
Some key players in the carbon-negative textile fibers market include Universal Fibers, Origin Materials, Rubi Laboratories, CarbonYarn, Fairbrics, Handa Industries, Renaissance Fiber, AECI SANS Technical Fibers, SEFF, and PrimaLoft.
Algae-based fibers are the fastest-growing fiber type in the carbon-negative textile fibers market.
The sports & performance segment is the fastest growing application in the carbon-negative textile fibers market.
The hemp fiber segment accounted for the largest revenue share of 31.0% in 2025, due to its strong carbon-sequestration potential, renewable nature, durability, and growing adoption as a sustainable alternative to conventional textile fibers.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


