
- Home
- »
- Next Generation Technologies
- »
-
Access Control Market Size & Share Report, 2026-2033GVR Report cover

Access Control Market (2026 - 2033)
Size, Share & Trends Analysis Report By Offering (Hardware, Software), By Type, By End-use (Business & Enterprise Environments, Financial Institutions, Hospitality & Entertainment), By Region, And Segment Forecasts
Market Size, 2025
$11.6BMarket Estimate, 2026
$12.5BMarket Forecast, 2033
$22.8BCAGR, 2026–2033
9.0%Access Control Market Summary
The global access control market size was estimated at USD 11.6 billion in 2025 and is projected to grow from USD 12.5 billion in 2026 to USD 22.8 billion by 2033, growing at a CAGR of 9.0% from 2026 to 2033. North America dominated the global market with the largest revenue share of 32.3% in 2025. The market is driven by the need for cloud-based and mobile access control solutions that integrate AI-powered identity verification and biometric authentication into modern security infrastructure.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By offering: Hardware segment dominated the market, with a revenue share of 44.3% in 2025.
- By type: RBAC segment held the largest market share of 47.2% in 2025.
- By end use: Business & enterprise environments segment held the largest market share of 19.4% in 2025.
Regional Highlights
- Largest regional market: North America (32.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 11.6 Billion
- Estimated market size in 2026: USD 12.5 Billion
- Projected market size by 2033: USD 22.8 Billion
- CAGR (2026-2033): 9.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Heightened security threats, regulatory mandates, and the increasing integration of advanced technologies contribute to the demand for sophisticated access control systems. Urbanization trends and smart city initiatives further amplify the need for effective access management solutions in residential, commercial, and public spaces. Moreover, the growing adoption of cloud-based and IoT-enabled systems provides scalable and efficient access control options, driving market expansion. To learn more about this report, Download Free Sample Report
Organizations are increasingly moving towards biometric authentication such as fingerprint, facial recognition, iris scanning, and Multi-Factor Authentication (MFA) to strengthen security and reduce the risks associated with traditional access methods such as passwords or keycards. Moreover, the integration of IoT technology and cloud computing in access control systems allows for real-time monitoring, remote management, and scalability, driving growth within the access control industry as businesses seek more flexible and secure access solutions. This shift is further amplified by the declining costs of biometric technologies and increased awareness of the vulnerabilities associated with traditional security measures. In addition, advancements in AI and ML are improving the accuracy and efficiency of biometric systems, making them more reliable for diverse applications across industries
Rising incidents of data breaches, theft, and unauthorized access to physical and digital spaces are pushing organizations and governments to adopt advanced access control solutions for enhanced security. Moreover, the expansion of commercial, industrial, and residential construction globally is fueling the demand for access control systems to secure facilities. This is particularly strong in developing regions with increasing urbanization and construction activities. Modern access control systems are increasingly integrated with video surveillance, intrusion detection, and fire alarm systems, providing organizations with a more comprehensive and layered approach to security.
Market Dynamics
The growing need to protect people, assets, and sensitive information across commercial, industrial, residential, and government facilities is driving strong demand for advanced access control solutions. Organizations are increasingly replacing traditional lock-and-key systems with centralized, identity-based access control platforms that improve security, operational efficiency, and regulatory compliance. The expansion of smart buildings connected workplaces, and hybrid work environments has further increased the need for flexible, cloud-enabled, and mobile credential-based access management.
The increasing frequency of unauthorized access incidents, workplace security risks, and data breaches is encouraging organizations to strengthen physical security through advanced access control systems. Businesses, government agencies, healthcare facilities, educational institutions, and industrial sites are replacing conventional access methods with identity-based solutions that verify users through credentials, biometrics, smart cards, or mobile devices. This transition improves control over who can enter restricted areas while reducing the risks associated with lost or duplicated physical keys.
Furthermore, organizations are adopting centralized identity management platforms that enable administrators to monitor, authenticate, and manage user access across multiple locations from a single interface. The integration of access control with biometric authentication, mobile credentials, and real-time monitoring enhances both security and operational efficiency, making identity-based access management a key driver of growth in the global access control market.
The increasing adoption of biometric access control systems has raised concerns regarding the collection, storage, and use of sensitive personal data such as fingerprints, facial images, and iris scans. Unlike passwords or access cards, biometric information cannot be easily changed if compromised, making organizations more cautious about large-scale deployment. Strict data protection regulations and growing public awareness of digital privacy require organizations to implement robust security measures, transparent consent policies, and secure data management practices. These compliance requirements increase implementation complexity and costs, while concerns over data misuse and unauthorized access can slow the adoption of biometric authentication solutions across privacy-sensitive industries.
The increasing shift toward cloud infrastructure is creating significant growth opportunities for Access Control as a Service (ACaaS), as organizations seek centralized and remotely managed security solutions. Cloud-based access control eliminates the need for extensive on-premises hardware, reduces maintenance costs, and enables administrators to monitor and manage multiple locations through a single platform. This model is particularly attractive for businesses with distributed offices, retail chains, educational institutions, and healthcare facilities that require scalable and flexible security management.
The growing adoption of hybrid work environments and multi-site operations is further accelerating demand for ACaaS, as it supports real-time credential updates, remote access permissions, and seamless software upgrades. Integration with mobile credentials, video surveillance, visitor management, and identity management platforms enhances operational efficiency while improving security. As organizations continue their digital transformation initiatives, cloud-based access control is expected to become a key growth avenue for vendors offering subscription-based and scalable security solutions.
Market Concentration & Characteristics
The impact of regulations is high, as organizations must comply with stringent security, privacy, and data protection requirements across industries such as government, healthcare, banking, and critical infrastructure. Regulations on identity verification, cybersecurity, workplace safety, and personal data protection encourage the adoption of advanced, compliant access control systems. Vendors increasingly focus on delivering secure, auditable, and standards-compliant solutions to meet evolving regulatory requirements.
 To learn more about this report, Download Free Sample Report
The access control market exhibits high-end-user concentration across multiple industries, with strong demand from commercial buildings, government facilities, healthcare institutions, educational campuses, manufacturing plants, transportation hubs, and residential complexes. No single industry dominates the market, creating a broad and diversified customer base. This widespread adoption across sectors enhances market stability while encouraging vendors to develop customized solutions for different operational and security requirements.
Analyst Perspective
The access control market is entering a phase where value is shifting from standalone physical security devices to intelligent identity and access management platforms that connect people, facilities, and digital infrastructure through a unified ecosystem. The strongest competitive advantage is expected to belong to vendors that combine cloud-native architecture, AI-driven authentication, biometrics, mobile credentials, and seamless interoperability with video surveillance and building management systems. As organizations modernize workplaces, critical infrastructure, and smart buildings, demand is increasingly centered on scalable, software-defined platforms rather than isolated hardware deployments.
Offering Insights
Based on offering, the hardware segment led the market with the largest revenue share of 44.3% in 2025 and is expected to grow at a significant CAGR over the forecast period. Technological advancements, security demands, and regulatory requirements are key factors that shape the hardware segment. Moreover, biometric authentication technologies, such as fingerprint scanners, facial recognition, and iris scanning, are increasingly being used due to their accuracy and enhanced security. These systems are being adopted across various sectors, such as government, healthcare, and financial institutions, driving the demand for biometric hardware devices.
The services segment is anticipated to grow at the fastest CAGR over the forecast period due to the increasing need for ongoing support and maintenance of access control systems. Organizations require continuous technical assistance to ensure optimal performance and security of these systems, which includes services like authentication, authorization, auditing, and monitoring. The adoption of cloud-based access control solutions further necessitates service support to manage and analyze data effectively. As a result, the demand for services such as system upgrades, troubleshooting, and training is rising, driving the growth of this segment.
Type Insights
Based on type, the RBAC segment led the market with the largest revenue share of 47.2% in 2025. RBAC is widely adopted across various industries, including commercial, healthcare, education, and government, due to its simplicity and scalability. It allows organizations to assign access rights based on predefined roles, streamlining access management for large workforces. RBAC is easier to implement and manage compared to other segments, as access rights are associated with roles of administrator and user rather than individuals, making it highly efficient in environments with frequent role changes or new hires. RBAC is often a key component of compliance frameworks, making it a beneficial solution for organizations in industries that require stringent access control and auditing.
The Mandatory Access Control (MAC) segment is anticipated to exhibit the fastes CAGR over the forecast period. Various industries, such as government, military, and critical infrastructure, have stringent regulatory requirements for data protection and access control, driving the demand for MAC systems. For instance, in military security, MAC is exemplified when the classification of sensitive information, such as top-secret documents, is determined by a central authority rather than the individual data owner. This centralized control ensures that access permissions are managed and cannot be altered by individual users, maintaining the integrity and security of classified information. Moreover, growing awareness about the benefits of MAC and its role in enhancing security helps drive its adoption across industries with high-security needs. Furthermore, high-security data centers require MAC to ensure controlled access to sensitive data and infrastructure.
End-use Insights
Based on end use, the business & enterprise environments segment led the market with the largest revenue share of 19.4% in 2025 and is expected to grow at a significant CAGR over the forecast period. Business and enterprise environments encompass a broad range of organizations and industries that require access control solutions for managing employee access, securing sensitive areas, and protecting company data. Moreover, businesses and enterprises often require scalable access control systems to accommodate large numbers of users and various types of access permissions. Continuous investments in upgrading security infrastructure and adopting new technologies contribute to the growth of the access control industry within business and enterprise environments, driving significant demand for access control solutions.
 To learn more about this report, Download Free Sample Report
The healthcare and life sciences segment is anticipated to exhibit the fastest CAGR over the forecast period. The rise in cyberattacks targeting healthcare data emphasizes the need for advanced access control systems to safeguard electronic health records and other sensitive data from unauthorized access. Moreover, the expansion of healthcare facilities, including hospitals, clinics, research labs, and long-term care facilities, drives demand for scalable and comprehensive access control systems. Thus, the growth of the healthcare & life sciences segment in the global access control industry is driven by stringent regulatory requirements, increasing cybersecurity threats, facility expansion, the need for patient safety, technological advancements, and a focus on operational efficiency.
Regional Insights
North America dominated the access control market with the largest revenue share of 32.3% in 2025. Increasing concerns over workplace violence, school shootings, and general crime in public and private spaces are driving demand for access control solutions to enhance safety in this region. Moreover, AI and machine learning are being incorporated into access control systems to enhance security, with capabilities such as real-time threat detection, predictive analytics, and automated decision-making.
 To learn more about this report, Download Free Sample Report
U.S. Access Control Market Trends
The access control market in the U.S. held the largest share in the North America region in 2025. With the rise of remote work and hybrid working environments in the U.S., companies are increasingly adopting cloud-based access control systems that enable secure, remote management of facilities and systems. This trend is expected to continue driving demand for flexible access control solutions. Moreover, continuous growth in commercial real estate, industrial facilities, and critical infrastructure projects in the U.S. requires access control systems for security and management, further contributing to market growth.
Europe Access Control Market Trends
The access control industry in Europe is expected to witness significant growth over the forecast period. Europe's strict data protection and privacy regulations, such as the General Data Protection Regulation (GDPR), are driving businesses to adopt compliant access control systems that can ensure the secure management of personal data. Additionally, numerous industries such as finance, healthcare, and defense face sector-specific regulations that require access control protocols. Moreover, with rising concerns about terrorism, crime, and workplace violence, there is a heightened demand for access control solutions across Europe.
Asia Pacific Access Control Market Trends
The access control industry in the Asia Pacific region is anticipated to register the highest CAGR over the forecast period. The Asia-Pacific region is witnessing extensive urbanization, leading to the development of smart cities and modern infrastructure projects. Governments and private sectors are investing heavily in access control systems to enhance security in new commercial buildings, residential complexes, transportation hubs, and public spaces. Furthermore, rapid industrialization in developing countries such as China, India, and Southeast Asian nations is fueling the need for access control systems.
China access control market dominated the regional market in 2025 driven by rapid urbanization, smart city development, and the need for security in large commercial and industrial sectors. The government's focus on enhancing security infrastructure and the increasing adoption of IoT-based solutions further contributed to this dominance. In addition, China's significant investment in technological advancements and its large consumer base create a favorable environment for access control solutions. For instance, in February 2024, Hangzhou Hikvision Digital Technology Co., Ltd. introduced its second-generation professional access control products, featuring enhanced web management, flexible authentication, and advanced access applications, marking a substantial advancement in access management.
Key Access Control Company Insights
Key access control companies include Allegion, ASSA ABLOY, and Axis Communications AB.
-
Allegion specializes in the development of innovative products that enhance safety and convenience. The company provides a comprehensive range of electronic locks, keyless entry systems, and advanced access control technologies tailored for residential, commercial, and institutional applications. Allegion's focus on integrating IoT and smart technologies into its offerings has positioned it as a key player in modernizing access management systems.
-
ASSA ABLOY is a world-renowned provider of access control and security solutions, offering a diverse portfolio that includes electronic locks, biometric systems, and cloud-based access management platforms. The company caters to various sectors such as commercial buildings, healthcare, and education, emphasizing sustainability and cutting-edge technology. Through continuous innovation and acquisitions, ASSA ABLOY has established itself as a leader in delivering comprehensive and scalable access control solutions.
Key Access Control Companies:
The following key companies have been profiled for this study on the access control market.
-
Allegion
-
ASSA ABLOY
-
Axis Communications AB
-
Bosch Sicherheitssysteme GmbH
-
dormakaba Group
-
Honeywell International Inc.
-
Identiv, Inc.
-
Johnson Controls Inc.
-
Nedap N.V.
-
Siemens
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Allegion; ASSA ABLOY; Axis Communications AB; Bosch Sicherheitssysteme GmbH; dormakaba Group)
- Focus on integrated access control ecosystems combining hardware, software, cloud platforms, and building automation.
- Expand market presence through acquisitions, strategic partnerships, and continuous investment in AI, biometrics, and cloud technologies.
- Broad global distribution networks with comprehensive product portfolios serving multiple industry verticals.
- Strong brand recognition and long-term enterprise relationships supported by extensive service capabilities.
- Large product portfolios can increase implementation complexity and deployment timelines.
- Premium pricing may limit adoption among cost-sensitive small and medium-sized organizations.
Emerging Players (Identiv, Inc.; Nedap N.V.)
- Focus on cloud-native access control, mobile credentials, and identity-centric security platforms for targeted industry applications.
- Differentiate through agile product development and partnerships with technology providers and system integrators.
- Faster innovation cycles enable rapid adoption of new authentication technologies and software enhancements.
- Flexible deployment models and specialized solutions address evolving customer requirements.
- Limited global sales channels and service networks compared with established market participants.
- Smaller product portfolios and lower brand visibility can affect participation in large enterprise projects.
Recent Developments
-
In April 2025, Rently and ASSA ABLOY announced a strategic partnership to launch the Smart Bolt Elite, a cutting-edge smart lock tailored for the rental housing sector. This device integrates Rently's expertise in leasing automation and smart home technology with ASSA ABLOY's advanced SmartKey Security re-keying solution.
-
In March 2025, Johnson Controls, a provider of smart, healthy, and sustainable building solutions, unveiled a series of enhancements to its Access Control And Video Surveillance (ACVS) offerings. These upgrades are designed to integrate with existing security systems, thereby improving the management of critical security operations and providing comprehensive protection for people, buildings, and assets.
-
In January 2025, dormakaba Group, announced the expansion of its partnership with technology company Rohde & Schwarz from the airport sector to the critical infrastructure domain. The two companies have developed an innovative automated personnel screening solution designed to enhance security checks while increasing capacity and efficiency.
-
In June 2024, Control iD, an access control system provider, partnered with Paravision, an AI software provider, and launched its new product, the iDFace Max, using facial identification technology. Key features of iDFace Max include advanced facial identification, design and connectivity, and embedded web software.
-
In June 2024, Carrier Global Corporation, an intelligent climate and energy solutions provider, announced the sale of its security division, Global access solutions, to Honeywell International Inc. It has been finalized with the transaction valued at USD 4.95 billion in enterprise value
Access Control Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.6 billion
Estimated market size in 2026
USD 12.5 billion
Projected market size by 2033
USD 22.8 billion
Growth rate
CAGR of 9.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Offering, type, end use, region
Regional scope
North America, Asia Pacific; Europe; MEA; Latin America
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Allegion; ASSA ABLOY; Axis Communications AB; Bosch Sicherheitssysteme GmbH; dormakaba Group; Honeywell International Inc.; Identiv, Inc.; Johnson Controls Inc.; Nedap N.V.; Siemens
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Access Control Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global access control market report based on the offering, type, end-use, and region:
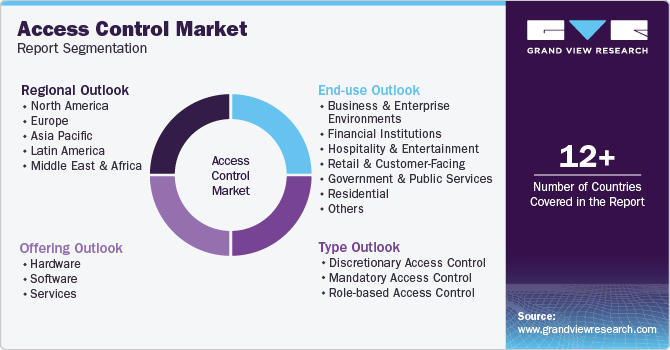 To learn more about this report, Download Free Sample Report
-
Offering Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Software
-
Services
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Discretionary Access Control (DAC)
-
Mandatory Access Control (MAC)
-
Role-Based Access Control (RBAC)
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Business & Enterprise Environments
-
Financial Institutions
-
Hospitality & Entertainment
-
Retail & Customer-Facing
-
Government & Public Services
-
Residential
-
Education & Research
-
Healthcare & Life Sciences
-
Energy & Utility Infrastructure
-
Transportation & Logistics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
MEA
-
UAE
-
South Africa
-
KSA
-
-
Research Methodology
The access control market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each access control segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Offering
Revenue capture definition
Hardware
Revenue in the hardware segment is generated from electronic locks, controllers, card readers, biometric devices, access panels, and related physical components deployed across secured facilities. Demand is supported by new installations, infrastructure upgrades, and replacement of legacy security equipment.
Software
The software segment captures revenue from access management platforms, identity management applications, credential administration, monitoring dashboards, and cloud-based access control solutions. Growth is supported by increasing adoption of centralized security management and system integration.
Services
Revenue in the services segment is derived from system design, installation, integration, consulting, maintenance, technical support, and managed access control services. Organizations rely on these services to optimize system performance, ensure regulatory compliance, and maintain operational continuity.
Segment - Type
Revenue capture definition
DAC
DAC generates revenue from organizations requiring flexible permission management, where resource owners control user access based on operational requirements. Its adoption remains notable among SMEs, enterprise file systems, and collaborative workplace environments seeking simplified access administration.
MAC
MAC contributes revenue through deployments in government, defense, and highly regulated industries that require policy-driven access enforcement and strict information security. Demand is supported by environments handling classified data and compliance-focused security frameworks.
RBAC
RBAC accounts for a significant share of market revenue due to its ability to assign permissions based on organizational roles, improving administrative efficiency. Its widespread implementation across enterprises, healthcare, BFSI, and IT sectors supports consistent demand for scalable identity and access management solutions.
Segment - End Use
Revenue capture definition
Business & Enterprise Environments
Revenue is generated from access control deployments across corporate offices, business parks, and enterprise campuses to manage employee access and secure sensitive areas. Demand includes integrated credential management, visitor access, and centralized security administration.
Financial Institutions
This segment captures revenue from banks, insurance companies, and financial service providers deploying high-security authentication systems to protect branches, vaults, and data centers. Adoption is supported by compliance requirements and multi-layer security infrastructure.
Hospitality & Entertainment
Revenue originates from hotels, resorts, stadiums, casinos, and entertainment venues using access control to manage guest entry, staff movement, and restricted zones. Mobile credentials and integrated property management systems support deployment in this segment.
Retail & Customer-Facing
This segment includes access control solutions installed in retail stores, shopping malls, and commercial outlets to secure inventory, cash handling areas, and employee-only spaces. Retailers also integrate these systems with surveillance and loss prevention platforms.
Government & Public Services
Revenue is derived from government offices, defense facilities, municipal buildings, and public service institutions requiring secure identity verification and controlled access. Deployments emphasize regulatory compliance and protection of sensitive infrastructure.
Residential
This segment covers smart locks, biometric entry systems, gated community access, and apartment security solutions designed for residential properties. Increasing adoption of connected home technologies supports revenue generation across this market.
Education & Research
Revenue is generated from schools, universities, and research institutions implementing access control for classrooms, laboratories, libraries, and residential campuses. These systems help manage student, staff, and visitor access through centralized administration.
Healthcare & Life Sciences
This segment includes hospitals, clinics, laboratories, and pharmaceutical facilities using access control to protect patient areas, medical records, drug storage, and research environments. Security requirements and controlled access policies support technology adoption.
Energy & Utility Infrastructure
Revenue comes from power plants, renewable energy sites, water treatment facilities, and utility networks deploying access control to secure operational assets and restricted locations. Integration with broader physical security systems is common across critical infrastructure.
Transportation & Logistics
This segment captures revenue from airports, rail networks, seaports, warehouses, and logistics centers requiring controlled access for personnel, cargo handling, and operational facilities. Deployments support security, workforce management, and site monitoring.
Others
Revenue includes deployments across religious institutions, sports complexes, cultural venues, construction sites, and other specialized facilities with unique access management requirements. Solution configurations vary according to operational and security needs.
Estimation Model
Layer Name
Key Questions
Description
Infrastructure Layer
Where can access control systems be deployed?
Identify the addressable building and facility base across commercial, industrial, residential, government, healthcare, education, transportation, and other sectors. This establishes the total installation opportunity for access control solutions.
Deployment Layer
How many sites adopt access control?
Apply technology adoption and installation rates across identified facilities to estimate the number of sites implementing access control systems. This converts the addressable infrastructure into the active deployment base.
Solution Layer
Which access control technologies are implemented?
Measure the distribution of deployments across hardware, software, cloud-based platforms, biometric systems, mobile credentials, and managed services. This reflects technology penetration and solution mix within the market.
Monetization Layer
How much revenue is generated?
Apply the average revenue generated from hardware, software licenses, installation, maintenance, cloud subscriptions, upgrades, and professional services across deployments to estimate total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Entry & Expansion Assessment
Regional demand sizing and forecasting
Customer segmentation and buying behavior analysis
Competitive landscape benchmarking
Regulatory and distribution channel assessment
Identified high-growth market opportunities
Supported go-to-market strategy development
Highlighted investment priorities and risks
Enabled data-driven expansion planning
Technology & Innovation Assessment
Emerging technology trend analysis
Innovation pipeline
Technology adoption readiness assessment
Ecosystem and partnership mapping
Identified future growth areas
Supported roadmap planning innovation
Evaluated commercialization potential
Strengthened strategic partnership decisions
Customer & End-User Insights Study
Consumer awareness and adoption analysis
Purchase decision journey mapping
Satisfaction and loyalty assessment
Usage pattern and pain-point evaluation
Revealed key adoption drivers and barriers
Supported customer-centric product development
Improved targeting and engagement strategy
Identified opportunities for retention and upselling
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The Hardware segment led with a 44.3% revenue share in 2025, while Services is the fastest growing segment.
RBAC held the largest revenue share in 2025, while MAC is the fastest growing segment.
Business & Enterprise Environments held the largest revenue share in 2025, while Healthcare & Life Sciences is the fastest growing segment.
Some key players operating in the access control market include Allegion; ASSA ABLOY; Axis Communications AB; Bosch Sicherheitssysteme GmbH; dormakaba Group; Honeywell International Inc.; Identiv, Inc.; Johnson Controls Inc.; Nedap N.V.; Siemens.
North America dominated the access control market with a share of 32.3% in 2025. Increasing concerns over workplace violence, school shootings, and general crime in public and private spaces are driving demand for access control solutions to enhance safety in this region. Moreover, AI and machine learning are being incorporated into access control systems to enhance security, with capabilities such as real-time threat detection, predictive analytics, and automated decision-making.
The market is driven by the need for cloud-based and mobile access control solutions that integrate AI-powered identity verification and biometric authentication into modern security infrastructure.
The global access control market size was esti22.8 billionmated at USD 11.6 billion in 2025 and is projected to grow from USD 12.5 billion in 2026
The global access control market is expected to grow at a compound annual growth rate of 9.0% from 2026 to 2033 to reach USD 22.8 billion by 2033
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


