
- Home
- »
- Semiconductors
- »
-
Gallium Nitride Semiconductor Devices Market Report, 2026-2033GVR Report cover
![Gallium Nitride Semiconductor Devices Market (2026 - 2033)Report]()
Gallium Nitride Semiconductor Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (GaN Radio Frequency Devices, Opto-semiconductors), By Component (Transistor, Diode), By Wafer Size, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$3.7BMarket Estimate, 2026
$4.6BMarket Forecast, 2033
$28.9BCAGR, 2026–2033
30.0%Gallium Nitride Semiconductor Devices Market Summary
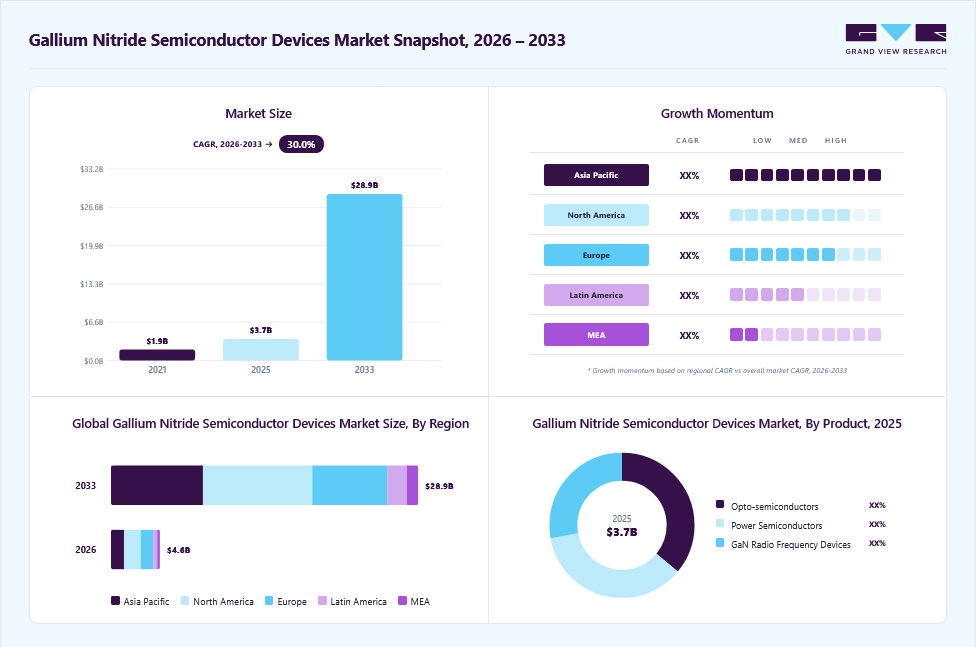
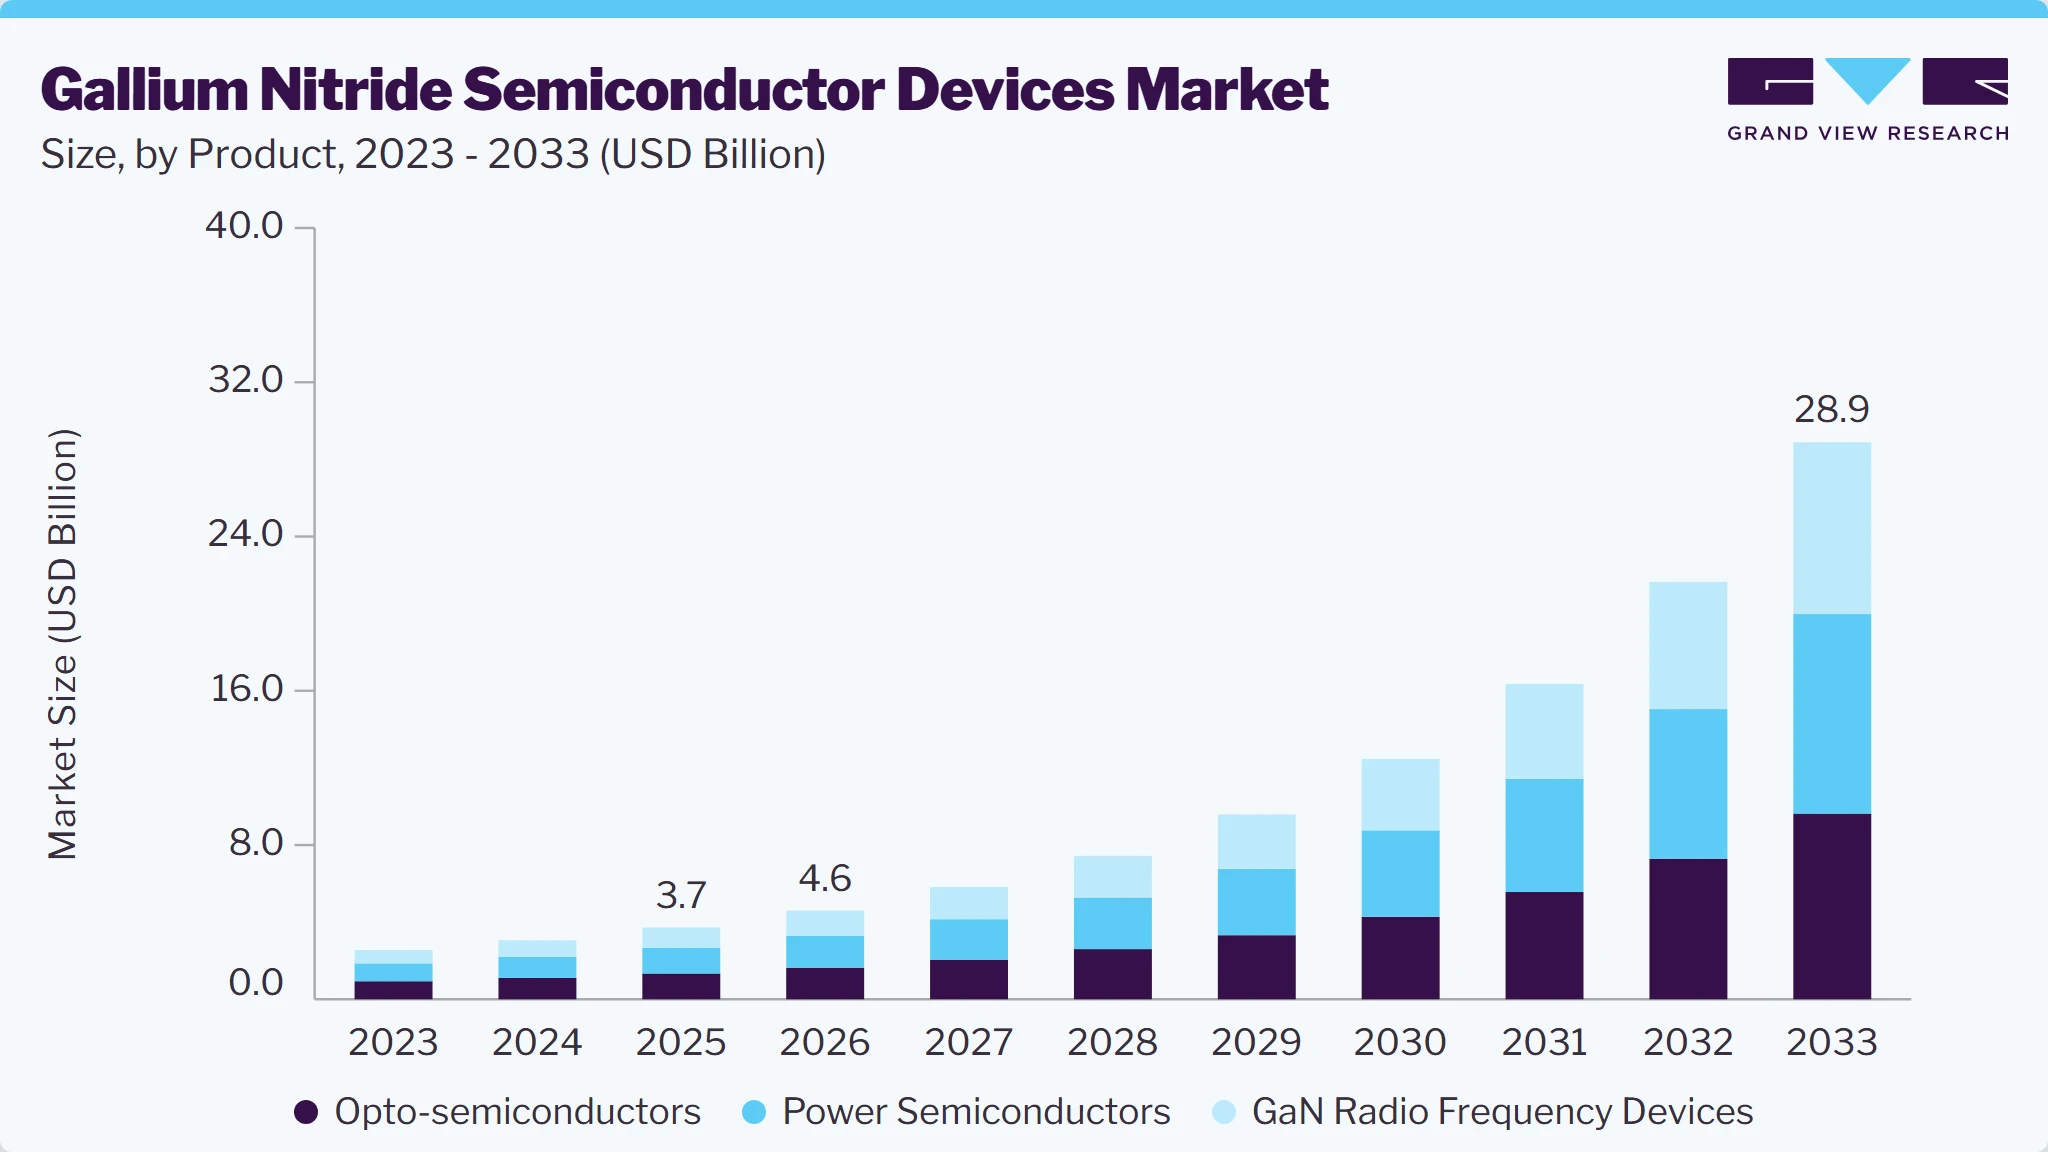
The global gallium nitride (GaN) semiconductor devices market size was valued at USD 3.7 billion in 2025 and is projected to grow from USD 4.6 billion in 2026 to USD 28.9 billion by 2033, at a CAGR of 30.0% from 2026 to 2033. North America dominated the global market with the largest revenue share of 34.4% in 2025. Gallium semiconductors provide high-speed performance and contribute to lower carbon emissions, which positions them as effective devices in the field of electronics.
Key Market Trends & Insights
- By product: Power semiconductors segment dominated the market, with a revenue share of 36.1% in 2025.
- By component: Transistor segment held the largest market share of 37.1% in 2025.
- By wafer size: 4 inch segment held the largest revenue share of 38.5% in 2025.
- By end use: information & communication technology accounted for the largest revenue share of 23.5% in 2025.
Regional Highlights
- Largest regional market: North America (34.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.7 Billion
- Estimated market size in 2026: USD 4.6 Billion
- Projected market size by 2033: USD 28.9 Billion
- CAGR (2026-2033): 30.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Gallium Nitride (GaN) possesses a wide band gap that makes the device more compact and capable of handling larger electric fields. As GaN possesses a wider band gap (approximately 3.4 eV) in contrast to silicon (1.2 eV), it facilitates higher carrier density, exceptionally low resistance, and capacitance, contributing to 100 times faster speeds. In addition, the integration of GaN technology across diverse sectors such as optoelectronics, automotive, and data centers has been instrumental in driving the growth of the market.The automotive sector is currently experiencing a significant transformation toward electrification, with GaN semiconductor devices emerging as crucial components driving this change. Leveraging GaN's exceptional efficiency and robust power handling capabilities, various applications within electric vehicles, including onboard chargers, DC-DC converters, and power inverters, are being optimized for enhanced performance. As the global demand for electric vehicles escalates, the market for GaN semiconductor devices is positioned for substantial expansion, playing a pivotal role in accelerating the widespread adoption of electric transportation solutions. This evolution not only underscores the automotive industry's commitment to sustainability but also signifies a paradigm shift toward cleaner and more efficient mobility solutions on a global scale.
New application areas, such as healthcare, are expected to stimulate the market growth of GaN semiconductor devices. For instance, robots using GaN components are used for the effective execution of delicate surgeries. Leveraging GaN's exceptional speed, efficiency, and reliability, robotic systems equipped with GaN technology offer unprecedented precision and control, crucial for intricate surgeries. These advanced robots, enabled by GaN semiconductor devices, empower healthcare professionals to perform minimally invasive surgeries with unparalleled accuracy, minimizing patient trauma and recovery times. As the healthcare industry continues to embrace technological advancements, the utilization of GaN semiconductor devices in medical robotics represents a compelling frontier, promising transformative benefits for both patients and practitioners.
The demand for wireless communication devices, primarily in defense communication, is expected to drive the demand for GaN semiconductors. GaN technology offers several advantages that are particularly well-suited for defense communication systems. Its high power density, wide bandwidth, and superior thermal conductivity enable the development of robust and reliable wireless devices capable of operating in demanding environments. These attributes make GaN semiconductors ideal for applications such as radar systems, electronic warfare, and satellite communication, where performance, efficiency, and resilience are important.
The industry faces a significant challenge in the form of high initial investments. The fabrication of gallium nitride-based devices demands sophisticated manufacturing processes and specialized equipment, resulting in elevated upfront costs for companies entering the market. These expenses encompass research and development, epitaxial growth, wafer processing, and device packaging, among others. As a result, while the potential benefits of gallium nitride semiconductors, such as higher efficiency and power density, are compelling, the substantial initial investment required poses a considerable challenge for market entrants and smaller players, potentially limiting the market's growth and accessibility.
Market Dynamics
Gallium nitride (GaN) semiconductor devices offer superior electrical properties compared to traditional silicon-based semiconductors, including higher electron mobility, faster switching speeds, lower conduction losses, and enhanced thermal efficiency. These advantages enable the development of smaller, lighter, and more energy-efficient power systems, making GaN devices increasingly attractive for modern electronic applications.
The rapid adoption of fast-charging consumer electronics, electric vehicles, data centers, renewable energy systems, and 5G telecommunications infrastructure is further accelerating demand for GaN-based power electronics. As governments and industries worldwide emphasize energy efficiency and carbon emission reduction, manufacturers are increasingly integrating GaN power devices into power supplies, inverters, converters, and charging systems. This growing shift toward high-performance and energy-efficient electronic solutions continues to support the expansion of the GaN semiconductor devices market.
The growth of the GaN semiconductor devices market is restrained by the high manufacturing and production costs associated with GaN technology. Compared to conventional silicon semiconductors, GaN devices require specialized substrates, advanced fabrication techniques, and complex packaging processes, thereby increasing overall production costs. In addition, lower manufacturing yields, limited large-scale production capacity, and the need for significant investments in research and development further contribute to higher device costs. These factors can discourage adoption among cost-sensitive industries and small-scale manufacturers, limiting the widespread commercialization of GaN semiconductor devices despite their superior performance advantages.
The rapid expansion of electric vehicles (EVs) worldwide is creating significant growth opportunities for the GaN semiconductor devices market. GaN-based power devices offer higher efficiency, faster switching speeds, lower power losses, and superior thermal performance compared to conventional silicon semiconductors, making them highly suitable for onboard chargers, DC-DC converters, traction inverters, and EV charging infrastructure. According to the International Energy Agency (IEA), the global EV fleet is projected to reach approximately 250 million vehicles by 2030, highlighting the growing demand for advanced power semiconductor technologies such as GaN.
The rapid adoption of renewable energy systems is also emphasizing demand for GaN semiconductor devices. GaN technology improves the efficiency and power density of solar inverters, wind power converters, energy storage systems, and smart grid infrastructure, reducing energy losses and enhancing performance. Governments worldwide are investing heavily in clean energy to meet decarbonization targets. For example, India's Ministry of New and Renewable Energy (MNRE) reports the country added a record 44.5 GW of renewable energy capacity in 2025, raising its total non-fossil fuel power capacity to 262.74 GW. As renewable energy installations and grid modernization expand globally, demand for high-performance GaN-based power electronics is expected to rise, offering long-term growth opportunities for market participants.
Analyst Perspective
Rising demand for high-efficiency power electronics in electric vehicles, renewable energy, consumer electronics, data centers, and 5G infrastructure is driving growth in the GaN Semiconductor Devices Market. Increased emphasis on energy efficiency, electrification, and advanced communication networks is further accelerating GaN adoption across industries. Moreover, continued investment in semiconductor innovation and expanded manufacturing capacity support market development. As production costs decrease and commercialization advances, GaN devices are expected to achieve wider acceptance and play a key role in the global semiconductor industry.
Product Insights
Based on product, the power semiconductors segment led the market with the largest revenue share of 36.1% in 2025. This can be largely attributed to the application of opto-semiconductors in devices such as LEDs, solar cells, photodiodes, lasers, and optoelectronics. The automotive sector is increasingly utilizing opto-semiconductors in automotive lights, indoor and outdoor lighting, and pulse-powered lasers. This is subsequently propelling the adoption of opto-semiconductors in the automotive and consumer electronics industries. Furthermore, opto-semiconductors are being widely used in applications such as Light Detection and Ranging (LiDAR) and pulsed lasers, which bodes well for the growth of the segment.
The GaN radio frequency devices segment is anticipated to expand as a result of the increasing use of gallium nitride radio frequency devices for a wide variety of applications across industries such as consumer electronics and defense, which are early adopters in the market. These devices are also used in Improvised Explosive Devices (IEDs) as they offer high performance at moderate costs, which is anticipated to further drive the segment growth. Moreover, high-frequency GaN devices are used in vehicular communication systems and vehicle-to-grid communication systems of electric vehicles.
Component Insights
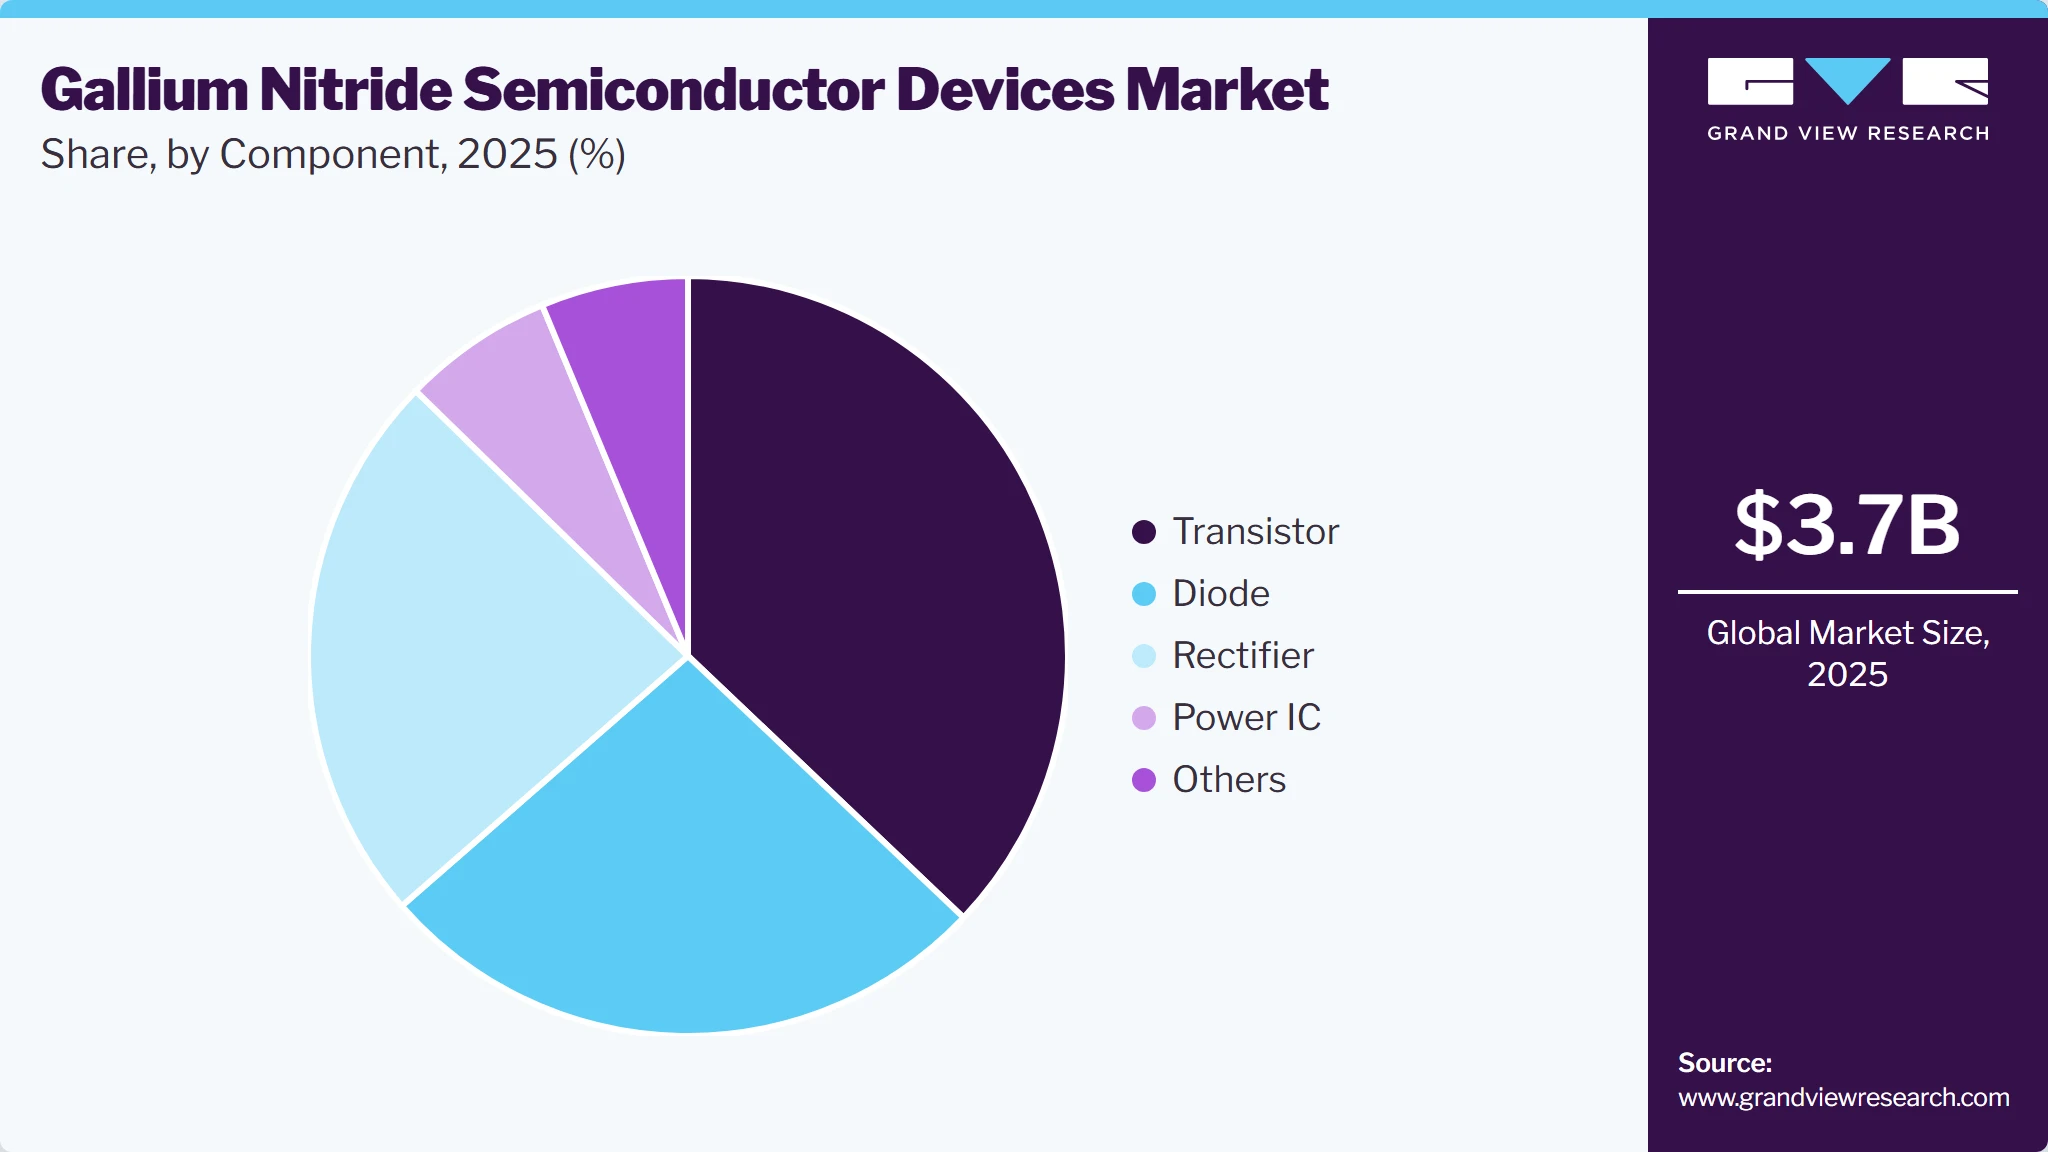
Based on component, the transistor segment led the market with the largest revenue share of 37.1% in 2025. GaN transistors, specifically high electron mobility transistors (HEMTs), demonstrate quantifiably better characteristics than silicon-based alternatives, with documented improvements in switching speeds, breakdown voltage, and conduction losses. These technical attributes position GaN transistors as suitable components for applications including electric vehicle powertrains, fast-charging infrastructure, and 5G network equipment, where specific performance requirements must be met. The ability of GaN transistors to operate at higher temperatures while maintaining performance further enhances their appeal in these applications.
The rectifier segment is expected to grow at the fastest CAGR of 29.8% over the forecast period. This growth can be attributed to the increasing demand for high-efficiency power conversion solutions across various industries, including automotive, consumer electronics, and telecommunications. GaN rectifiers exhibit lower conduction and switching losses, resulting in higher energy efficiency and reduced power dissipation. This efficiency translates into lower operating costs and improved overall system performance, particularly in high-power and high-frequency applications where energy efficiency is paramount. In addition, GaN rectifiers feature faster switching speeds and higher breakdown voltages, enabling them to operate at higher frequencies and handle higher voltages with greater reliability.
Wafer Size Insights
Based on wafer size, the 4 inch segment led the market with the largest revenue share of 38.5% in 2025. This is because 4-inch wafers facilitate the large-scale production of semiconductor devices. The implementation of 4-inch wafers is increasing rapidly as these wafers help overcome the limitations of 2-inch wafers and are widely used in semiconductor product-based industries. Furthermore, the increasing demand for gallium nitride devices with 4-inch wafers in high-power amplifiers, optoelectronics devices, telecom frontends, and high-temperature devices is driving the segment growth. Moreover, the suitability of a 4-inch substrate for space communication applications, owing to its radiation-hardened properties, is anticipated to be a key factor influencing segment growth.
The 6-inch segment is anticipated to expand owing to the benefits such as uniform voltage supply and precise current control offered by 6-inch wafers. A 6-inch wafer is engineered to provide better uniformity in voltage and precise control over the current. It has wide applications in defense equipment and consumer electronics owing to benefits such as high breakdown voltage and low current leakage. Furthermore, the increasing adoption of 6-inch wafers in commercial applications such as Monolithic Microwave Integrated-Circuit (MMIC) power amplifiers for wireless cellular base stations and automotive collision-avoidance systems bodes well for the segment growth.
End Use Insights
Based on end use, the information & communication technology segment led the market with the largest revenue share of 23.5% in 2025. The growth can be attributed to the increasing adoption of Internet-of-Things (IoT) technology globally. IoT devices demand efficient and cost-effective components that facilitate a constant exchange of information. GaN-based semiconductors are expected to meet low power consumption and high-efficiency requirements for the proper functioning of IoT-enabled products. In addition, these semiconductors are widely used in Distributed Antenna System (DAS), small cells, and remote radio head network densification. They are also used in data centers, servers, base stations, transmission lines, satellite communication, and base transceiver stations, among others.
The growth of the defense and aerospace segment can be attributed to the increasing applications of GaN technology in the defense and aerospace sector to increase the bandwidth and performance reliability in communications, electronic warfare, and radars. The ICs used in radar boards incorporate GaN, which enables efficient navigation, facilitates collision avoidance, and enables real-time air traffic control. The higher operating frequencies provided by GaN semiconductors make them suitable for use in radar communication, terrestrial radios, and military jammers. Moreover, the increasing usage of wideband GaN power transistors in amplifiers for software-defined radios is a major factor responsible for the segment growth.
Regional Insights
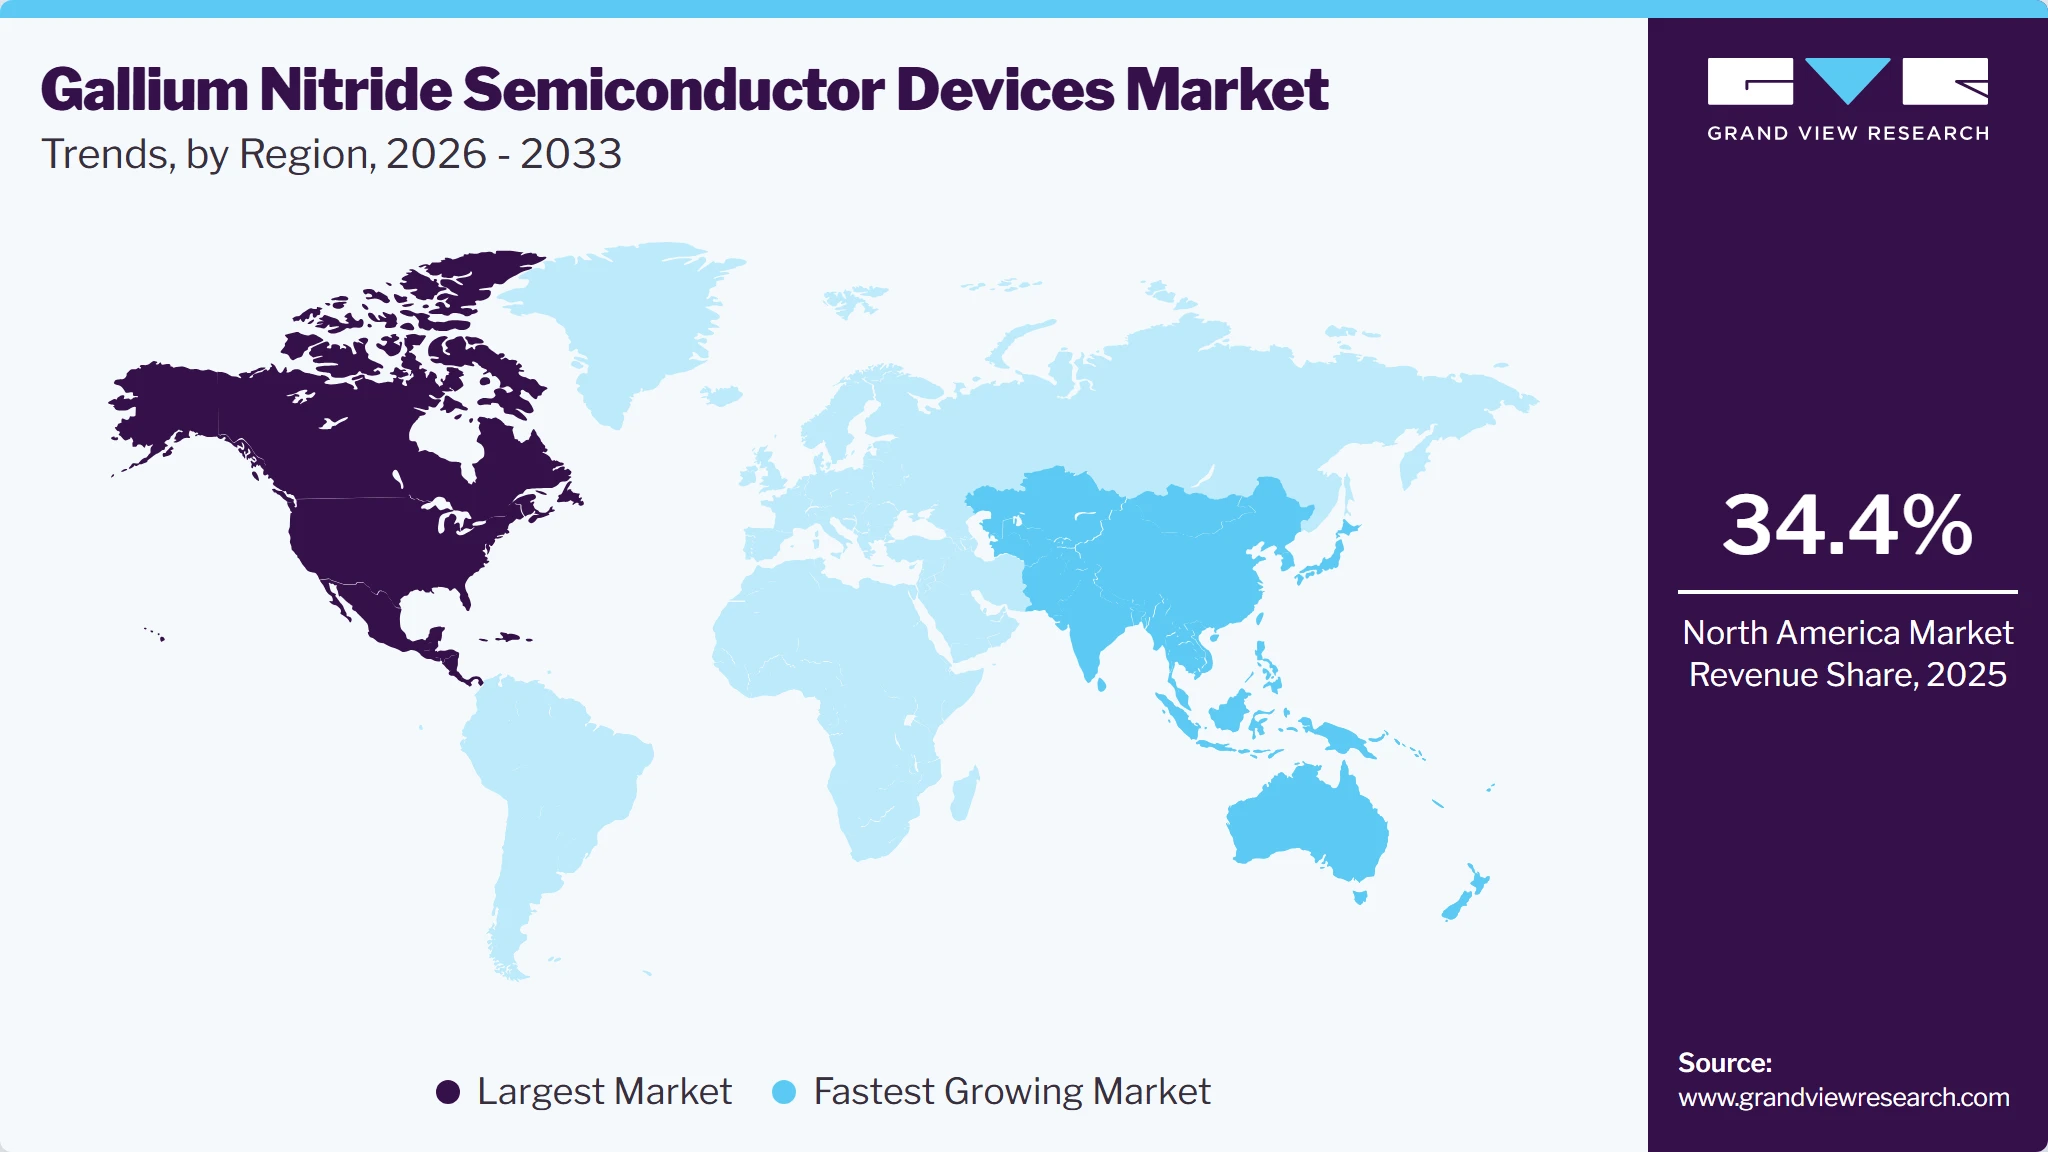
North America dominated the global gallium nitride semiconductor devices market with the largest revenue share of 34.4% in 2025. Increasing investments from the defense and aerospace industry in research & development are fueling the market growth in the region. Furthermore, funding provided by government bodies to semiconductor companies is expected to drive market growth in the region. Companies in this region are also focusing on launching the commercialization rights for a range of gallium nitride on silicon (GaN-on-Si) patents. For instance, in March 2024, 5N Plus Inc., a semiconductor technology company, launched the commercialization rights for a collection of gallium nitride on silicon (GaN-on-Si) patents. According to the company, these patents can facilitate the swift development of prototypes and the early market introduction of innovative vertical GaN-on-Si power devices.
U.S. Gallium Nitride Semiconductor Devices Market Trends
U.S. is the fastest growing country in the North America gallium nitride semiconductor devices market. Advancements in GaN technology and manufacturing processes are bolstering the U.S. market's expansion, positioning the U.S. as a key country in the global GaN semiconductor landscape.
Asia Pacific Gallium Nitride Semiconductor Devices Market Trends
The gallium nitride (GaN) semiconductor devices market in Asia Pacific is anticipated to emerge as the fastest-growing market through the projection period, owing to rapid technological advancements that are leading to increased demand for high-performance and efficient radio frequency components. Countries such as China and Japan in the region are some of the largest manufacturers of consumer electronics, including LED display devices, smartphones, and gaming consoles. This is a key factor boosting the growth of the regional market. The demand for reliable communication devices has expanded due to the expanding defense budgets in countries such as China, South Korea, and India, and this demand is expected to boost the market for gallium nitride-based RF devices. The development of telecommunications infrastructure and the notable rise in the usage of wireless electronic devices in the Asia Pacific region are further propelling the market's expansion.
China gallium nitride (GaN) semiconductor devices market is expected to grow at a significant CAGR from 2025 to 2030. Government initiatives to bolster domestic semiconductor production and advancements in GaN fabrication technologies are key drivers of market expansion, positioning China as a prominent force in the global GaN semiconductor market.
Europe Gallium Nitride Semiconductor Devices Market Trends
The gallium nitride semiconductor devices market in Europe is expected to grow at a significant CAGR of 29.0% from 2026 to 2033. GaN technology finds traction in sectors like renewable energy, automotive, and telecommunications as Europe focuses on reducing energy consumption and carbon emissions. Europe's robust semiconductor industry and supportive regulatory framework drive market expansion, establishing the region as a hub for GaN research, development, and manufacturing.
Germany gallium nitride (GaN) semiconductor devices market is expected to grow at a significant CAGR from 2025 to 2030. Germany, with its robust automotive industry and growing focus on renewable energy sources, presents a fertile ground for the adoption of GaN-based devices, thereby contributing to the growth of the market.
Key Gallium Nitride Semiconductor Devices Companies Insights
Key players operating in the gallium nitride (GaN) semiconductor devices market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Gallium Nitride Semiconductor Devices Companies:
The following key companies have been profiled for this study on the gallium nitride semiconductor devices market.
- Fujitsu Ltd.
- Efficient Power Conversion Corporation
- Transphorm, Inc.
- Infineon Technologies AG
- NXP Semiconductors.
- Qorvo, Inc
- Texas Instruments Incorporated.
- Toshiba Corporation
- GaN Systems
- NTT Advanced Technology Corporation.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Fujitsu Ltd., Infineon Technologies AG, NXP Semiconductors, Qorvo, Inc., Texas Instruments Incorporated, Toshiba Corporation, NTT Advanced Technology Corporation.)
- Focus on large-scale manufacturing and global supply chain optimization to achieve cost efficiency and high-volume production.
- Invest heavily in R&D to develop advanced GaN solutions for various applications.
- Leverage diversified semiconductor portfolios and established customer relationships to accelerate GaN adoption across multiple end-use industries.
- Strong brand recognition and long-standing relationships with global OEMs and industrial customers.
- Extensive manufacturing infrastructure and economies of scale that support cost-effective production.
- Broad product portfolios enabling cross-selling opportunities across multiple semiconductor categories.
- Complex organizational structures can slow decision-making and delay the commercialization of new GaN innovations.
- Dependence on large-scale operations and legacy semiconductor product lines may reduce flexibility in addressing niche GaN market opportunities.
Emerging Players (Efficient Power Conversion Corporation, Transphorm, Inc., GaN Systems.)
- Focus on GaN-specific innovation and product differentiation to address high-growth application areas.
- Develop application-specific solutions for electric vehicles, fast chargers, renewable energy systems, and data centers.
- Collaborate with OEMs, system integrators, and technology partners to accelerate commercialization and market penetration.
- Deep expertise and specialization in GaN technology development and optimization.
- Faster innovation cycles and greater agility in responding to evolving market requirements.
- Strong focus on high-performance, energy-efficient solutions tailored to specific applications.
- Limited manufacturing scale and financial resources compared to large multinational semiconductor companies.
- Higher dependence on partnerships and a narrower product portfolio can increase business and supply chain risks.
Recent Developments
-
In April 2024, Transphorm, Inc., a GaN power semiconductor provider, and Weltrend Semiconductor Inc. announced the introduction of two new GaN System-in-Packages (SiPs). These latest additions, namely the WT7162RHUG24C and WT7162RHUG24B, combine Weltrend’s high-frequency multi-mode (QR/Valley Switching) Flyback PWM controller with Transphorm's 480 mΩ and 150 mΩ SuperGaN FETs, respectively. This collaboration builds upon Weltrend’s flagship GaN SiP unveiled last year, collectively establishing the first SiP product family based on Transphorm’s SuperGaN platform.
-
In March 2024, Efficient Power Conversion Corporation launched EPC2361, a groundbreaking gallium nitride (GaN) field-effect transistor (FET) boasting the lowest on-resistance on the market at 100V, 1mΩ. This innovation promises to double the power density when compared to EPC's previous-generation products. The EPC2361 exhibits an impressive typical RDS (on) of only 1mΩ, housed in a thermally enhanced QFN package with an exposed top, occupying a mere footprint of 3mm x 5mm.
-
In January 2024, Transphorm Inc. launched two new 650V SuperGaN devices packaged in a 4-lead TO-247 package (TO-247-4L). These new FETs, named TP65H035G4YS and TP65H050G4YS, boast on-resistances of 35mΩ and 50mΩ, respectively, featuring a Kelvin-source terminal that enables customers to achieve versatile switching capabilities with reduced energy losses.
Gallium Nitride (GaN) Semiconductor Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.7 billion
Estimated Market size in 2026
USD 4.6 billion
Projected Market size by 2033
USD 28.9 billion
Growth rate
CAGR of 30.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, component, wafer size, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Fujitsu Ltd.; Efficient Power Conversion Corporation; Transphorm, Inc.; Infineon Technologies AG; NXP Semiconductors.; Qorvo, Inc.; Texas Instruments Incorporated.; Toshiba Corporation; GaN Systems; NTT Advanced Technology Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Gallium Nitride (GaN) Semiconductor Devices Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global gallium nitride (GaN) semiconductor devices market report based on product, component, wafer size, end use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
GaN Radio Frequency Devices
-
Opto-semiconductors
-
Power Semiconductors
-
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Transistor
-
Diode
-
Rectifier
-
Power IC
-
Others
-
-
Wafer Size Outlook (Revenue, USD Million, 2021 - 2033)
-
2-inch
-
4-inch
-
6-inch
-
8-inch
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Consumer Electronics
-
Defense & Aerospace
-
Healthcare
-
Industrial & Power
-
Information & Communication Technology
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia Pacific
-
India
-
China
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The gallium nitride semiconductor devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each gallium nitride semiconductor devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
GaN Radio Frequency Devices
GaN radio frequency (RF) devices are semiconductor components designed to operate at high frequencies and power levels for wireless communication applications. They are widely used in 5G base stations, satellite communications, radar systems, and defense electronics due to their high efficiency and signal performance.
Opto-semiconductors
GaN opto-semiconductors are light-emitting and light-detecting devices that utilize gallium nitride materials to generate or sense optical signals. These devices are commonly used in LEDs, laser diodes, displays, automotive lighting, and optical communication systems because of their high brightness and energy efficiency.
Power Semiconductors
GaN power semiconductors are electronic devices that control and convert electrical power in various systems with minimal energy loss. They are extensively used in electric vehicles, fast chargers, renewable energy systems, industrial power supplies, and data centers owing to their high switching speed and superior power efficiency.
Segment - Component
Revenue capture definition
Transistor
GaN transistors are semiconductor switching devices used to control and amplify electrical signals. They enable high-speed switching and improved energy efficiency in power and RF applications.
Diode
GaN diodes are semiconductor components that allow current to flow in one direction while blocking reverse current. They are valued for their low power losses and fast recovery performance.
Rectifier
GaN rectifiers convert alternating current (AC) into direct current (DC) with high efficiency. They are widely used in power supplies, renewable energy systems, and industrial electronics.
Power IC
GaN power integrated circuits combine multiple power management functions into a compact semiconductor device. They help improve power density, efficiency, and thermal performance in electronic systems.
Others
The others segment includes GaN-based modules, amplifiers, sensors, and specialized semiconductor components. These devices support niche applications across industrial, aerospace, defense, and communication sectors.
Segment - Wafer Size
Revenue capture definition
2 inch
2-inch GaN wafers are primarily used for research, prototyping, and low-volume semiconductor production. They support technology development and specialized applications requiring limited manufacturing scale.
4 inch
4-inch GaN wafers are used in the commercial production of RF and power semiconductor devices. They offer a balance between manufacturing cost and production efficiency for medium-scale applications.
6 inch
6-inch GaN wafers enable higher production volumes and improved economies of scale in semiconductor manufacturing. They are increasingly adopted for power electronics, 5G infrastructure, and automotive applications.
8 inch
8-inch GaN wafers support large-scale semiconductor production with enhanced yield and lower per-unit manufacturing costs. They are gaining traction as manufacturers expand capacity for high-volume commercial applications.
Segment - End Use
Revenue capture definition
Automotive
The automotive segment utilizes GaN semiconductor devices in electric vehicles, onboard chargers, DC-DC converters, and advanced driver-assistance systems. These devices improve power efficiency, reduce energy losses, and support vehicle electrification.
Consumer Electronics
GaN semiconductors are widely used in smartphones, laptops, fast chargers, gaming devices, and home appliances. They enable compact designs, faster charging capabilities, and improved energy efficiency.
Defense & Aerospace
The defense and aerospace sector employs GaN devices in radar systems, electronic warfare equipment, satellite communications, and avionics. Their high-frequency performance and reliability make them ideal for mission-critical applications.
Healthcare
GaN semiconductor devices are used in medical imaging systems, diagnostic equipment, and healthcare monitoring devices. They provide efficient power management and support high-performance medical technologies.
Information & Communication Technology
The ICT segment utilizes GaN devices in 5G base stations, data centers, optical networks, and telecommunications infrastructure. These semiconductors enhance signal performance, data transmission efficiency, and power management.
Industrial & Power
GaN devices are used in industrial automation systems, renewable energy installations, motor drives, and power supplies. They improve energy conversion efficiency, system reliability, and operational performance.
Others
The others segment includes applications in transportation, scientific research, consumer services, and emerging technologies. These sectors leverage GaN devices for specialized high-performance electronic requirements.
Estimation Model
Layer Name
Key Question
Description
Power Semiconductor Industry Layer
What is the overall addressable market for power semiconductor devices?
Assess the global power semiconductor industry, including silicon, silicon carbide (SiC), and gallium nitride (GaN) devices across automotive, industrial, consumer electronics, telecommunications, renewable energy, and data center applications. This establishes the total market base from which GaN adoption is derived.
GaN Penetration Layer
What proportion of power semiconductor demand is being served by GaN devices?
Evaluate the adoption of GaN technology relative to conventional silicon and SiC solutions across different voltage ranges and applications. Analyze factors such as efficiency improvements, switching performance, power density, and declining production costs driving market penetration.
Application Demand Layer
Which end-use applications are generating demand for GaN semiconductor devices?
Quantify GaN device demand across key applications including fast chargers and adapters, electric vehicles, renewable energy systems, data center power supplies, telecom infrastructure, consumer electronics, and industrial power systems. Adoption rates and device content per application are assessed to estimate market contribution.
Revenue Realization Layer
What is the resulting market revenue generated by GaN semiconductor devices?
Calculate market revenues by combining application-level unit demand with average selling prices (ASPs) of GaN transistors, ICs, diodes, and power modules. Revenue estimates are validated through manufacturer revenues, shipment analysis, and regional demand trends to derive the final market size.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Evaluation of the impact of AI data center expansion on future GaN power device demand.
Developed a dedicated demand assessment model quantifying GaN adoption across hyperscale data centers, AI servers, and power supply units.
Enabled accurate identification of emerging revenue pockets and long-term demand potential from AI-driven infrastructure investments.
Assessment of GaN supply chain vulnerabilities and capacity expansion plans across wafer suppliers, foundries, and device manufacturers.
Mapped the complete value chain, analyzed production, capacity additions, and key supplier dependencies across major regions.
Helped evaluate supply security risks and identify potential sourcing and partnership opportunities.
Analysis of technology transition from Silicon and Silicon Carbide to GaN across major power electronics applications.
Conducted comparative technology benchmarking covering performance, cost trajectory, efficiency gains, and commercialization readiness by application.
Supported strategic technology investment decisions and enabled prioritization of applications with the highest conversion potential.
Frequently Asked Questions About This Report
The global gallium nitride semiconductor devices market size was estimated at USD 3.7 billion in 2025 and is expected to reach USD 4.6 billion in 2026.
The global gallium nitride semiconductor devices market is expected to grow at a compound annual growth rate of 30.0% from 2026 to 2033 to reach USD 28.9 billion by 2033.
Based on product, the power semiconductors segment led the market with the largest revenue share of 36.1% in 2025.The segment's dominance can be attributed to the increasing adoption of GaN power devices in high-efficiency power conversion applications across consumer electronics, automotive, telecommunications, industrial automation, and renewable energy systems.
Some key players operating in the GaN semiconductor devices market include NXP Semiconductor N.V., GaN Systems, Inc., Efficient Power Conversion Corporation, Inc., Toshiba Corporation, Qorvo, Inc., Cree, Inc., Fujitsu Ltd., and Texas Instruments, Inc., among others.
The key factor that is driving the gallium nitride semiconductor devices market growth includes the accelerating demand for power electronics that consume less power and are energy efficient.
North America dominated with a 34.4% revenue share in 2025.
Asia Pacific is the fastest growing over the forecast period.
The transistor segment led with a 37.1% revenue share in 2025, and rectifier is the fastest growing segment.
The 4 inch segment led with a 38.5% revenue share in 2025, and 8 inch is the fastest growing segment.
About the Author(s)
Semiconductors Research Team
Semiconductors & Electronics · SemiconductorsThis report was authored by the semiconductors research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the semiconductors segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


