
- Home
- »
- Medical Devices
- »
-
Continuous Glucose Monitoring Devices Market Report, 2033GVR Report cover

Continuous Glucose Monitoring Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Sensors, Applicators), By Connectivity, By Indication (Type 1 Diabetes, Type 2 Diabetes), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$13.4BMarket Estimate, 2026
$15.5BMarket Forecast, 2033
$41.4BCAGR, 2026–2033
15.1%Continuous Glucose Monitoring Devices Market Summary
The global continuous glucose monitoring devices market size was valued at USD 13.4 billion in 2025 and is projected to grow from USD 15.5 billion in 2026 to USD 41.4 billion by 2033, at a CAGR of 15.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 63.3% in 2025. This growth is attributed to clinical needs, technological innovation, and shifting care models.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Sensor segment led the market with the largest revenue share of 62.8% in 2025.
- By connectivity: Bluetooth segment led the market with the largest revenue share of 57.3%in 2025.
- By indication: Type 1 diabetes segment led the market with the largest revenue share of 64.9% in 2025.
- By distribution channel: Pharmacies segment led the market with the largest revenue share of 59.4% in 2025.
Regional Highlights
- Largest regional market: North America (63.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 13.4 Billion
- Estimated market size in 2026: USD 15.5 Billion
- Projected market size by 2033: USD 41.4 Billion
- CAGR (2026-2033): 15.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Another primary factor for market growth is the rising global prevalence of diabetes, which has intensified the demand for more efficient and real-time glucose monitoring solutions. Traditional blood glucose testing is often invasive, intermittent, and inconvenient, prompting both patients and providers to adopt continuous glucose monitoring (CGM) systems for better glycemic control and improved quality of life. According to the International Diabetes Federation (IDF), as of 2024, there are approximately 589 million adults living with diabetes worldwide.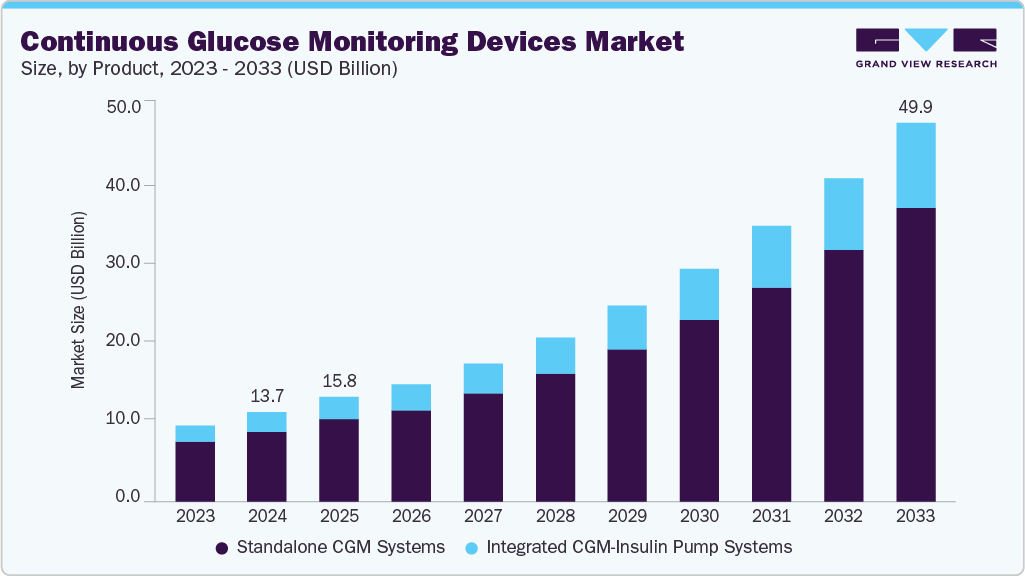 To learn more about this report, Download Free Sample Report
Global Diabetes Prevalence, 2024, Age [20-79]
Country
2024 (In Mn)
North America and the Caribbean
56m
South and Central America
35m
Europe
66m
Southeast Asia
107m
Western Pacific
215m
Middle East & North Africa
85m
Africa
25m
Total
589m
Source: International Agency for Research on Cancer (IARC), GVR Analysis
CGM devices are minimally invasive and offer an easy and effective way to manage diabetes. They can also detect drastic changes in blood glucose levels, thereby preventing hypoglycemic conditions. The continuous glucose monitoring (CGM) devices facilitate the analysis of blood glucose levels at different time intervals with the help of a sensor. Respective readings fed into diabetes management software through a wireless network allow patients to understand the disease better, thereby helping them to manage it more effectively. Smoking, obesity, physical inactivity, high blood pressure, and high cholesterol are the common risk factors associated with diabetes complications. For instance, in January 2024, Medtronic received CE Mark approval in Europe for its MiniMed 780G system with Simplera Sync, a next-generation, minimally invasive CGM sensor that integrates fully with its automated insulin delivery pump.
The market is also witnessing a shift toward the increasing demand for personalized, real-time diabetes care. Unlike traditional fingerstick glucose monitoring, CGM devices offer continuous insights into glucose trends, helping patients and healthcare providers make proactive decisions. For instance, in August 2024, Abbott and Medtronic announced a global partnership to integrate Abbott’s FreeStyle Libre CGM technology with Medtronic’s automated insulin delivery systems. This was a critical step towards simplifying diabetes management and reducing the burden of constant self-monitoring. According to a key personnel member at Abbott Laboratories’ Diabetes Care Division,
“Libre technology has set the standard for accurate, accessible, easy-to-use, and reliable continuous glucose monitoring. Connecting this CGM built for Medtronic's insulin delivery systems and algorithms makes it easier for people to spend less time thinking about their diabetes and more time living.”
Patients with diabetes are increasingly seeking tools that provide real-time data to prevent both hyperglycemic and hypoglycemic events. CGMs provide this data by measuring interstitial glucose levels daily and at night, offering alerts and predictive analysis that allow for timely interventions. This is especially important in insulin-dependent populations such as those with Type 1 diabetes or advanced Type 2 diabetes.
Rapid technological improvements and product innovation are driving the adoption of CGM systems by making monitoring easier, more accurate, and more tightly integrated with diabetes care. Companies are focusing on longer sensor life, smaller form factors, faster wireless connectivity, and AI-enabled analytics so users and clinicians get actionable trends rather than raw numbers.
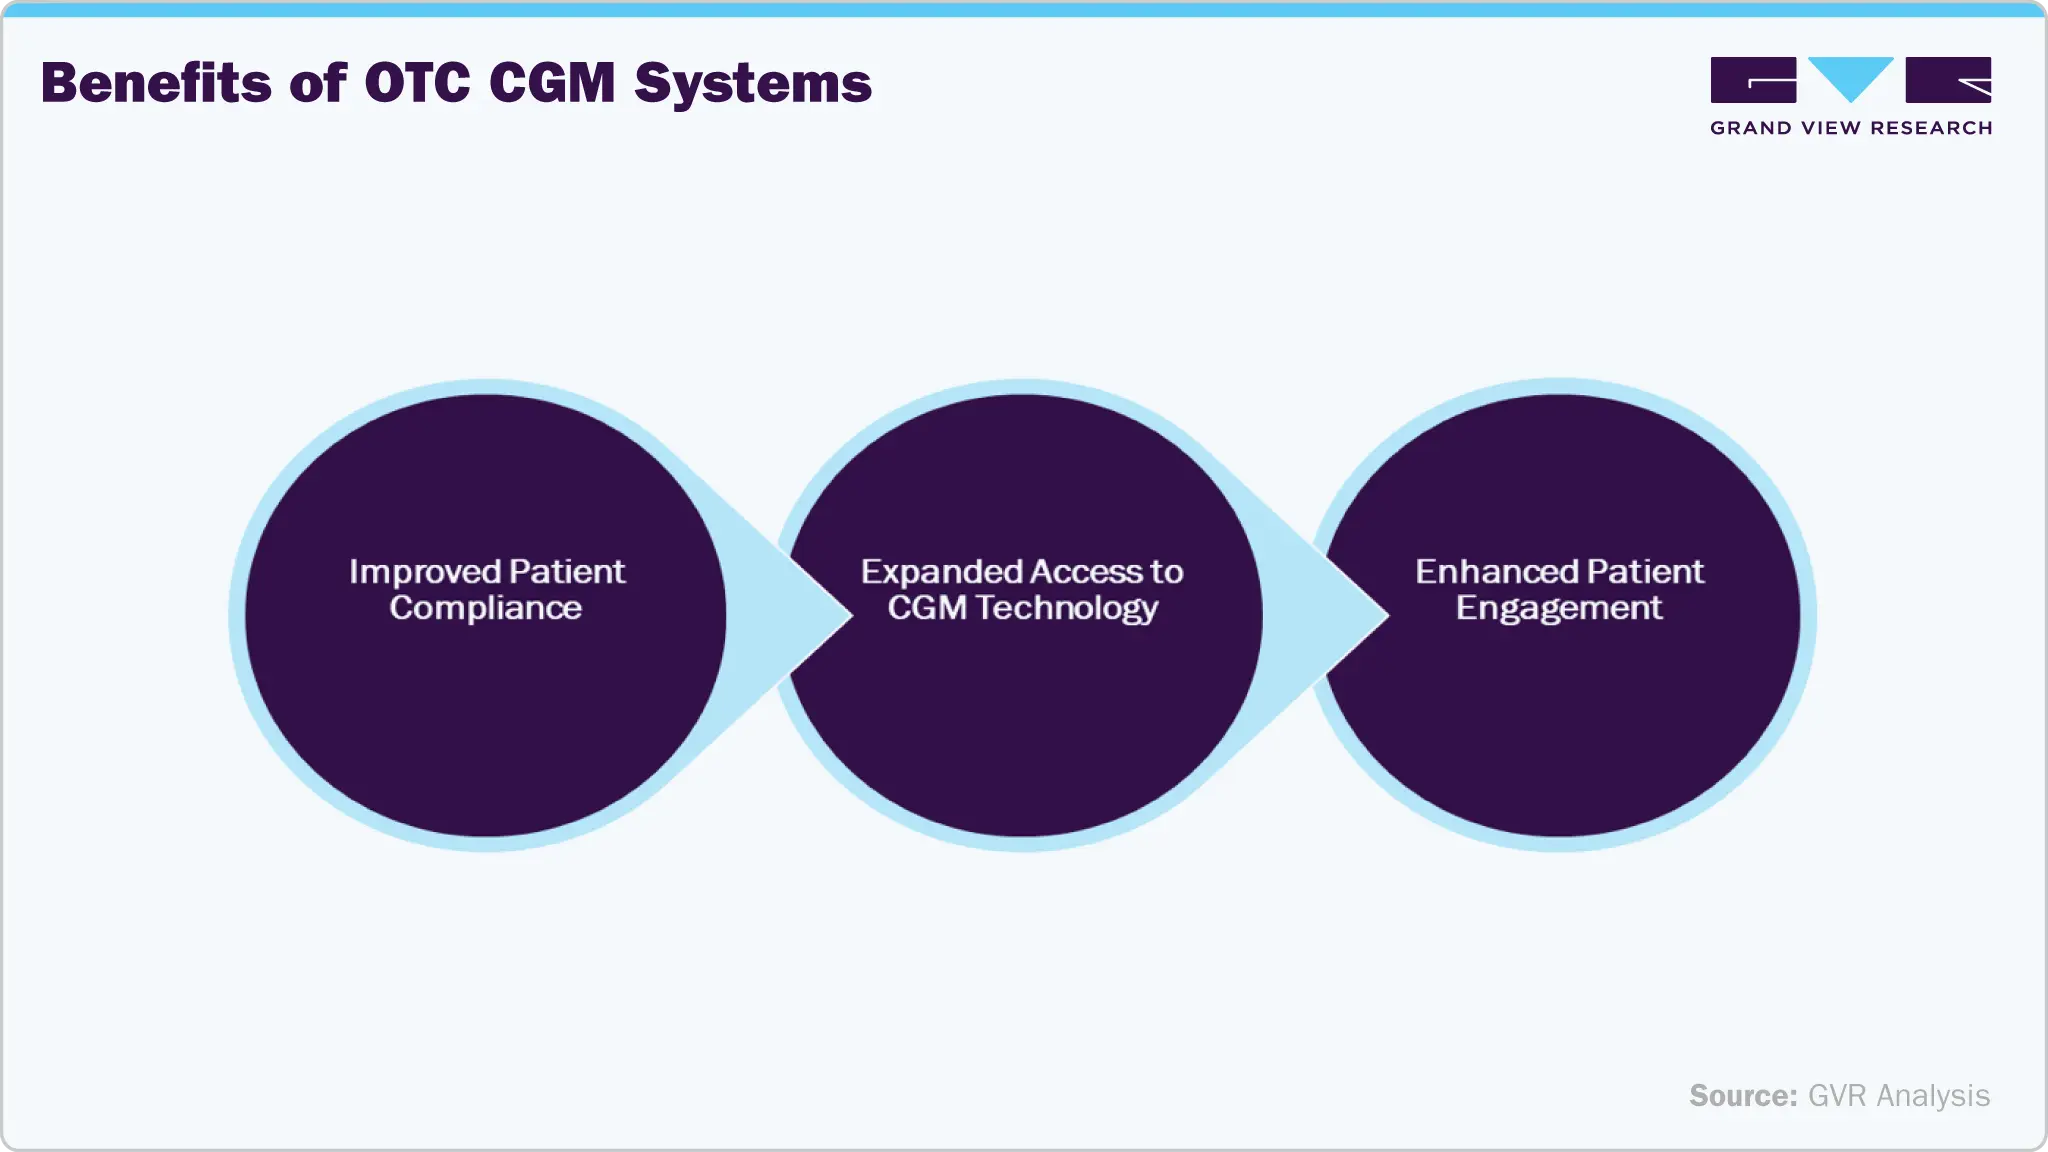
Recent over-the-counter (OTC) approvals for continuous glucose monitoring devices are broadening access beyond traditional prescription users. These systems allow individuals, including those without diabetes, to understand how daily habits influence glucose levels and make informed lifestyle adjustments.
 To learn more about this report, Download Free Sample Report
With user-friendly designs, seamless smartphone connectivity, and reduced access barriers, these developments are expanding adoption, promoting preventive health practices, and improving overall metabolic awareness.
Market Dynamics
Continuous glucose monitoring (CGM) devices are witnessing widespread adoption across hospitals, diabetes clinics, and home care settings as they enable individuals with diabetes and healthcare providers to continuously monitor glucose levels through wearable sensors and connected monitoring platforms. These advanced systems integrate technologies such as real-time continuous glucose sensing, predictive glucose alerts, Bluetooth connectivity, smartphone integration, cloud-based data sharing, and artificial intelligence (AI)-enabled analytics to provide accurate and actionable glycemic insights. By delivering continuous glucose trends and reducing dependence on routine fingerstick testing, CGM devices support improved glycemic control and personalized diabetes management. They enhance clinical decision-making, facilitate remote patient monitoring, and help reduce the risk of hypoglycemic and hyperglycemic events while improving overall patient outcomes.
The increase in the prevalence of diabetes due to aging, obesity, and unhealthy lifestyle is one of the factors contributing to the growth of the continuous glucose monitoring devices market. Obesity is a major factor leading to diabetes. According to WHO, in 2022, 1 in 8 people living with obesity. The 2.5 million adult individuals were living with overweight out of this 890 million were living with obesity. This number continues to grow. If things continue as they are, WHO predicts that by 2025, around 167 million people, both adults and children, will experience worsening health problems due to their weight issues. In addition to obesity, diabetes is becoming increasingly prevalent globally. The International Diabetes Federation (IDF) estimates that there were 589 million adults (aged 20-79) living with diabetes in 2025, and this number is expected to increase to 853 million by 2050. The IDF also reports that the prevalence of diabetes is growing globally, with the highest increase witnessed in low- and middle-income countries. In 2025, the regions with the highest number of adults living with diabetes were the Western Pacific (215 million), South East Asia (107 million), and Middle East & North Africa (85 million).
Data accuracy and technical limitations continue to hinder the growth of the continuous glucose monitoring (CGM) market, as they impact clinical confidence, reimbursement decisions, and the willingness of patients and providers to rely on these devices. CGMs measure glucose in interstitial fluid rather than directly in blood, which creates a natural delay and can cause noticeable differences from finger stick readings when glucose levels rise or fall quickly. Accuracy can also vary between device generations, different sensor placements, and patient-specific factors such as hydration, temperature, or skin characteristics. Due to these variations, clinicians often ask patients to confirm critical readings with a traditional finger stick, which reduces the convenience and efficiency that CGMs are expected to provide. A May 2024 study published by the National Library of Medicine on factory-calibrated continuous glucose monitors reported that leading CGM systems showed variable accuracy and a tendency to underestimate glucose levels in critically ill patients, indicating that performance in hospital settings remains inconsistent. The study highlights that shifting CGMs from outpatient to inpatient use introduces additional challenges, including rapid glucose fluctuations and medication interactions. It notes that additional validation, improved calibration approaches, and stronger clinical training are still required before CGMs can be reliably used in high-acuity hospital environments.
Market Concentration & Characteristics
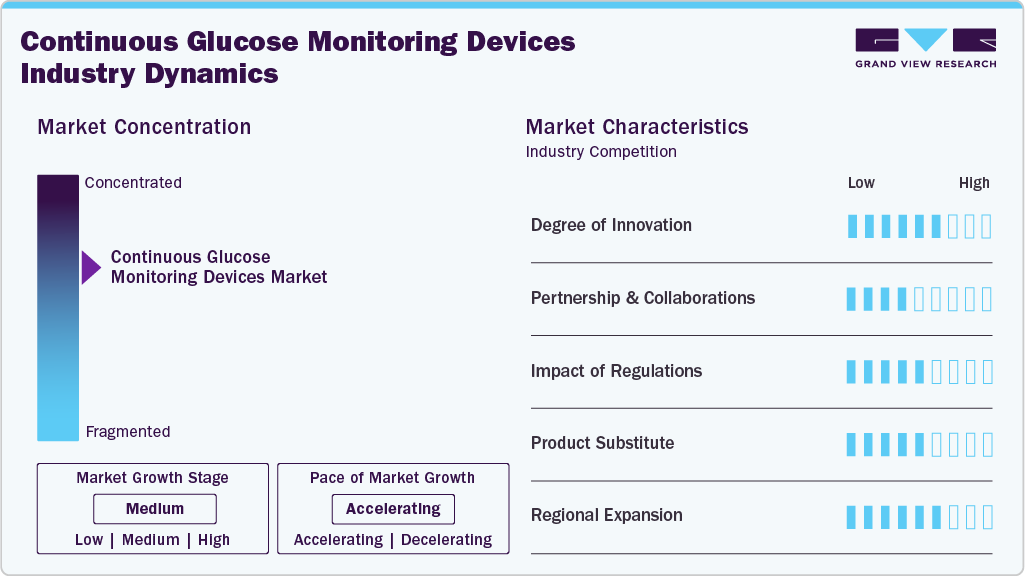
The continuous glucose monitoring devices industry witnesses’ significant industry concentration, with key players focusing on expansion and product differentiation. DexCom, Inc., Abbott Laboratories, and Medtronic plc hold significant market share. The market is characterized by steady growth driven by increasing diabetes cases, technological advancements, and a focus on patient safety and real-time data monitoring.
The CGM devices industry experiences a high degree of innovation, primarily driven by continuous advancements aimed at improving accuracy, user comfort, wear duration, and connectivity. Innovations such as factory-calibrated sensors, real-time mobile app integration, and non-invasive sensing technologies have significantly improved usability and patient adherence. Major players like Dexcom and Abbott have introduced next-generation sensors (G7 and Libre 3) that are smaller, faster, and more discreet, while others like Senseonics are pushing boundaries with implantable CGM systems.
 To learn more about this report, Download Free Sample Report
Industry leaders are increasingly partnering with insulin pump manufacturers, digital health platforms, and pharmaceutical companies to build integrated diabetes care ecosystems. Furthermore, tech collaborations with Apple, Fitbit, and cloud-based platforms have enabled real-time remote glucose monitoring, improving both user experience and clinical decision-making.
Regulatory oversight plays a pivotal role in shaping the market, given the clinical implications of continuous glucose data. In regions like the U.S. and Europe, strict regulatory pathways (FDA, CE Mark) ensure product safety, accuracy, and reliability. Recent policy shifts have also expanded access, such as Medicare’s 2023 coverage for CGMs in non-insulin-treated Type 2 diabetes, significantly broadening the eligible user base. While regulatory hurdles can delay time-to-market, they reinforce trust and help high-quality manufacturers secure a competitive advantage through regulatory differentiation.
While CGMs offer superior insight and convenience, they face partial competition from traditional blood glucose meters (BGMs), particularly in price-sensitive and emerging markets. However, the substitute threat is declining as CGMs become more affordable, receive broader insurance coverage, and demonstrate better outcomes in glycemic control.
The CGM devices industry is witnessing significant regional expansion, particularly in emerging economies where surgical volumes are rising and healthcare infrastructure is improving. Similarly, increasing regulatory compliance and hospital facility requirements are expected to drive demand. In addition, multiple companies are working together to expand the accessibility and adoption of CGM devices and technologies across regions. For instance, in November 2024, Dexcom led a $75 million Series D round for ŌURA and forged a tech partnership to integrate Dexcom’s CGM data (including OTC Stelo) with the ŌURA Ring. This was done to help consumers improve their metabolic health by integrating DexCom CGM data with vital sign, sleep, stress, heart health and activity data from the Oura Ring.
Analyst Perspective
The continuous glucose monitoring (CGM) devices market is positioned at the convergence of several long-term healthcare and digital health trends, including the rising global prevalence of diabetes, increasing adoption of continuous disease monitoring, and continuous advancements in wearable sensor technologies. The growing burden of Type 1 and Type 2 diabetes, coupled with the need for improved glycemic control and personalized diabetes management, is driving significant demand for real-time glucose monitoring solutions. CGM devices are increasingly utilized across hospitals, diabetes clinics, and home care settings to support insulin therapy optimization, reduce hypoglycemic and hyperglycemic events, and enable proactive disease management. Furthermore, ongoing innovations such as AI-powered glucose analytics, extended-wear sensors, smartphone connectivity, cloud-based remote monitoring, and integration with automated insulin delivery systems are enhancing patient outcomes, improving clinical decision-making, and accelerating the adoption of connected diabetes care.
Product Insights
Based on product, the sensor segment led the market with the largest revenue share of 62.8% in 2025. Sensors form the core component of CGM systems, as they continuously measure glucose levels in interstitial fluid and transmit data to receivers or connected mobile applications. This segment holds the largest market share primarily due to the recurring replacement cycle of sensors, which typically need to be replaced every 10-15 days depending on the device, resulting in significantly higher sales volumes compared with transmitters or receivers that last longer. Growth of this segment is further supported by the expanding adoption of CGM devices among individuals with both type 1 and type 2 diabetes, improvements in sensor accuracy and wear duration, and increasing integration of CGM systems with digital health platforms and automated insulin delivery technologies.
The transmitters segment in the market is witnessing significant growth during the forecast period. Transmitters play a critical role in CGM systems by wirelessly transmitting glucose data from the sensor to receivers, smartphones, or connected digital health platforms, enabling real-time glucose monitoring and data sharing. Growth of this segment is largely driven by the increasing adoption of CGM systems, expansion of connected diabetes management ecosystems, and advancements in wireless communication technologies such as Bluetooth-enabled data transmission. In addition, the growing integration of CGM devices with mobile applications, insulin pumps, and automated insulin delivery systems is increasing the demand for advanced transmitters that support seamless connectivity, improved battery life, and enhanced data reliability. As the global installed base of CGM users continues to expand, the demand for transmitters is expected to increase steadily, contributing to the segment’s strong growth trajectory.
By Connectivity
Based on connectivity, the Bluetooth segment led the market with the largest revenue share of 57.3%in 2025. CGM sensors are equipped with Bluetooth chips. As the patient hovers the recording device over the sensor, detailed information on the blood glucose levels is transferred via Bluetooth into the device. Further, the information is displayed on the reading device. The data may or may not be shared via 4G network to be saved in the monitor center database. CGM manufacturers mainly outsource these chips to provide precise and accurate data capture from the sensor. Companies like Nordic Semiconductors, Renesas Electronics, Onsemi, and others develop these chips for CGM devices. The chip is replaced every 14 days as the sensors need to be changed.
The near field communication (NFC) segment is expected to witness significant growth at a CAGR of 19.54% during the forecast period. This is driven by its ease of use, cost-effectiveness, and widespread smartphone compatibility. Unlike Bluetooth or cellular-based systems, NFC allows users to retrieve glucose data simply by bringing a reader or smartphone close to the CGM sensor, eliminating the need for continuous wireless transmission. This method reduces power consumption and makes devices more affordable-an especially appealing factor in emerging markets and among non-insulin-dependent Type 2 diabetics.
By Indication
Based on indication, the type 1 diabetes segment led the market with the largest revenue share of 64.9% in 2025. People suffering from Type 1 diabetes (T1D) are the primary users of CGM devices, owing to their lifelong requirement for insulin and the critical need to tightly regulate glucose levels. CGMs offer real-time data, trends, and automated alerts. According to the CDC, approximately 1.7 million adults aged 20 years or older, or 5.7% of all U.S. adults with diagnosed diabetes, reported having type 1 diabetes and using insulin. T1D management demands frequent blood glucose monitoring and precise insulin dosing. Real-time CGM data is integral to achieving glycemic targets and reducing acute complications.
The Type 2 segment is expected to grow significantly, at a CAGR of 15.60% during the forecast period. Type 2 diabetes (T2D) is emerging as the fastest-growing indication in the CGM market. A combination of rising disease prevalence, expanded clinical use cases, and broader reimbursement policies supports CGM adoption among non-insulin-using T2D patients. Regulatory changes have further accelerated this trend. In 2023, Medicare expanded coverage for CGM devices to include people with Type 2 diabetes who are not on insulin, recognizing their benefits in proactive disease management. In addition, the launch of over-the-counter CGM devices like Dexcom’s Stelo has opened the door for widespread consumer access without prescriptions, especially for those with early-stage or prediabetic conditions.
Distribution Channel Insights
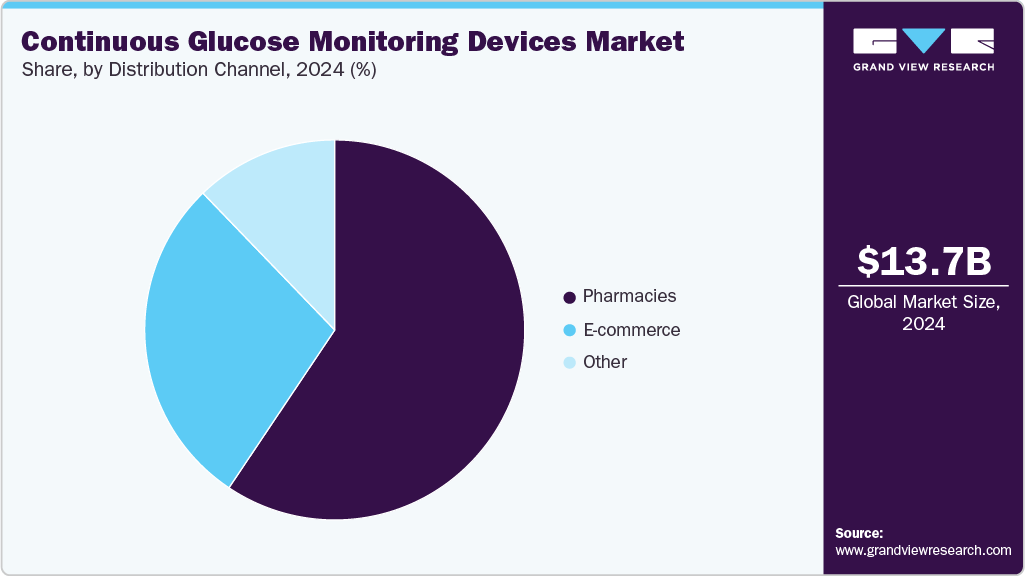
Based on distribution channel, the pharmacies segment led the market with the largest revenue share of 59.4% in 2025, which is driven by their accessibility, trusted role in chronic disease management, and evolving business models that now support prescription and over-the-counter (OTC) CGM product sales. Partnerships between CGM manufacturers and national pharmacy chains further reinforce the dominance of this channel. For instance, companies like DexCom, Inc. and Abbott have partnered with CVS Health, Walgreens, and Walmart to offer their devices in-store and through online prescription services.
 To learn more about this report, Download Free Sample Report
The e-commerce segment is expected to grow significantly at a CAGR of 15.31% during the forecast period. The expansion of direct-to-consumer (DTC) offerings and recent regulatory approvals enable over-the-counter (OTC) sales of CGM devices online. Furthermore, the shift towards virtual healthcare and remote patient monitoring has validated e-commerce as a viable and trusted channel. CGM manufacturers have responded by investing in robust online ecosystems that support product education, purchasing, and subscription-based delivery models. For instance, DexCom, Inc. offers Stelo through a monthly subscription model online, giving users a recurring, low-friction experience that aligns with consumer expectations in other health tech sectors.
Regional Insights
North America Continuous Glucose Monitoring Devices Market Trends
North America dominated the continuous glucose monitoring devices market with the largest revenue share of 63.3% in 2025, driven by the increasing prevalence of diabetes, rising adoption of CGM devices, technological advancements, and the presence of key companies. In addition, the efforts taken by the federal government to manage the disease at a larger level are fueling market growth. For instance, in February 2024, Canada’s federal government announced Bill C-64, which aims to establish a Canada-wide diabetes device fund to support access to CGMs and other essential diabetes supplies.
 To learn more about this report, Download Free Sample Report
North America Continuous Glucose Monitoring Devices Market Trends
The continuous glucose monitoring devices market in the U.S. held the largest share in the North America region in 2025. According to the National Diabetes Statistics Report 2022 by the CDC, over 130 million adults in the U.S. are either suffering from diabetes or have prediabetes. The high per capita income and increasing healthcare spending are among the key factors likely to drive market growth.
U.S. Diabetes Prevalence from 2021-2033, Age [20-79]
Year
Number of People Suffering from Diabetes (In Million)
2000
15.3
2011
23.7
2024
38.5
2050
43.0
Source: International Diabetes Federation (IDF), GVR Analysis
The high per capita income and increasing healthcare spending are among the key factors likely to drive market growth. According to the International Diabetes Federation (IDF), diabetes caused at least USD 1 trillion in health expenditure, a 338% increase over the last 17 years. Key players in the U.S. are executing various strategies to expand their market share. For instance, Abbott Laboratories introduced a more affordable version of Libre at around USD 75 for a month’s supply (which includes two sensors lasting up to 14 days each) in May 2022. This move aims to reduce the financial burden on diabetic patients in the country.
Europe Continuous Glucose Monitoring Devices Market Trends
The European industry for continuous glucose monitoring devices market is witnessing significant growth driven by a rising diabetes burden, favorable public healthcare support, digital health adoption, and demographic trends. According to the International Diabetes Federation (IDF), in 2024, the number of adults (ages 20-79 years) with diabetes in the region was 65.5 million and is expected to reach 72.4 million by 2050. Based on this, CGM devices are increasingly embraced as essential tools for long-term glucose management, particularly among individuals with Type 1 diabetes and high-risk Type 2 cases. Moreover, EU-wide regulatory alignment and cross-border collaborations under initiatives like Horizon Europe have encouraged partnerships between manufacturers, providers, and public health bodies, fostering innovation and broader patient outreach. Despite challenges around affordability and regional disparities, the European CGM market is poised for continued expansion as healthcare systems prioritize early intervention and technology-enabled chronic disease management.
The UK's continuous glucose monitoring devices industry is growing steadily, supported by a strong public healthcare system, national reimbursement programs, and rising diabetes prevalence. The National Health Service (NHS) has played a pivotal role in expanding access, with CGMs now widely reimbursed for individuals with Type 1 diabetes and increasingly for high-risk Type 2 patients. Digital health integration has further accelerated adoption, as CGM data is commonly linked to NHS digital platforms and used in remote consultations. The UK government’s focus on preventive care and self-management, combined with a tech-savvy population and active clinical research ecosystem, continues to position CGMs as a key tool in modern diabetes care.
Germany’s CGM devices industry is among the most advanced markets in Europe, driven by strong public health insurance coverage, early adoption policies, and a well-established diabetes care infrastructure. For a long time, statutory health insurance (GKV) has reimbursed CGM devices for patients with Type 1 diabetes and selected high-risk Type 2 cases, greatly expanding access. Germany’s robust healthcare provider network and emphasis on evidence-based care have supported widespread clinical acceptance of CGMs. In addition, the integration of CGM data into electronic health records and telemedicine platforms aligns with the country’s digital health agenda. Ongoing innovation from local and global manufacturers and Germany’s focus on chronic disease prevention continue to sustain market growth.
Asia Pacific Continuous Glucose Monitoring Devices Market Trends
The CGM devices industry in Asia Pacific expected to grow at the fastest CAGR over the forecast period and is driven by the region’s rising diabetes prevalence, increasing healthcare digitization, and improving access to advanced medical technologies. Countries such as China, India, Japan, South Korea, and Australia are witnessing strong growth due to the growing awareness of diabetes complications, urban lifestyle changes, and government initiatives promoting early diagnosis and self-monitoring.
Asia Pacific Diabetes Prevalence, 2024 Vs. 2050 (In Million)
Country
Number of People Suffering from Diabetes, In Million
2024
2050
China
148.0
168.3
Japan
10.8
9.4
India
89.8
156.7
Republic of Korea
5.0
5.1
Australia
1.7
2.2
Source: International Diabetes Federation (IDF), GVR Analysis
Japan and South Korea have established reimbursement frameworks for CGMs, while India and China have increasing private sector investment and digital health platform integration. With a large diabetic population and rising health consciousness, Asia-Pacific represents a high-growth market for CGM manufacturers seeking long-term expansion.
The continuous glucose monitoring (CGM) devices industry in China is driven by the country’s escalating diabetes burden, rising health awareness, and growing acceptance of digital health solutions. With approximately 148.0 million (as of 2024), living with diabetes, there is a strong push towards better disease monitoring and early intervention. Domestic companies like Sinocare and Yuwell, along with international players such as Abbott and DexCom, are expanding their footprint through e-commerce and partnerships & collaborations. For instance, in January 2024, Trinity Biotech plc announced a partnership with Bayer AG to co-develop and introduce a CGM biosensor in China and India. This collaboration aims to leverage Bayer’s regional presence and Trinity’s biosensor technology to broaden CGM access in China, which aligns with national strategies for diabetes management.
The continuous glucose monitoring (CGM) devices industry in India is evolving rapidly due to the country’s large diabetic population, growing health awareness, and increasing adoption of digital health tools. With over 100 million people living with diabetes, there is a rising demand for more accurate, real-time glucose monitoring solutions, especially in urban areas. Patients and providers are increasingly turning to CGMs as a superior alternative to traditional glucometers, particularly for insulin users and high-risk individuals. The expansion of telemedicine, wellness apps, and virtual diabetes clinics has created new channels for CGM access, while leading hospitals and private healthcare networks are integrating CGMs into chronic care plans. Global players like Abbott, DexCom, and Medtronic are active in India, often selling via e-commerce and diagnostic partnerships, while local innovators are exploring more affordable sensor options.
Latin America Continuous Glucose Monitoring (CGM) Devices Market Trends
The continuous glucose monitoring (CGM) devices industry in Latin America is driven by the increasing prevalence of diabetes, the improvement of healthcare infrastructure, and the rising awareness of advanced glucose monitoring technologies. While access has traditionally been limited due to cost and low reimbursement coverage, urban populations in countries such as Brazil, Argentina, and Colombia are beginning to adopt CGM systems more widely, particularly among patients with Type 1 diabetes and insulin-dependent Type 2 cases.
Brazil's continuous glucose monitoring (CGM) devices industry is witnessing significant growth, which is supported by its sizable diabetic population, progressive regulatory environment, and expanding private healthcare sector. With approximately 16.6 million people living with diabetes, there is a growing demand for more precise and continuous glucose monitoring solutions. The Brazilian National Health Surveillance Agency (ANVISA) has approved several CGM systems, including those from Abbott and Medtronic, enabling their use across both private and selected public healthcare channels.
Middle East and Africa Continuous Glucose Monitoring (CGM) Devices Market Trends
The continuous glucose monitoring (CGM) devices industry in the Middle East and Africa (MEA) is driven by the growing awareness of digital health solutions, government-led efforts to modernize chronic disease care, and the rising prevalence of diabetes cases. Diabetes rates are among the highest globally in parts of the Gulf region, including the UAE, Saudi Arabia, and Qatar, where CGM adoption is increasing due to high-income populations, advanced healthcare infrastructure, and access to private insurance.
Middle East & Africa Diabetes Prevalence, 2024 Vs. 2050 (In Million)
Country
Number of People Suffering from Diabetes, In Million
2024
2050
Saudi Arabia
5.3
9.5
UAE
1.3
1.9
Qatar
0.4
0.6
Kuwait
0.9
1.3
South Africa
2.3
3.9
Source: International Diabetes Federation (IDF), GVR Analysis
The continuous glucose monitoring (CGM) devices industry in Saudi Arabia is witnessing steady growth, driven by strong government investment in healthcare transformation and widespread access to modern medical technologies. With nearly 1 in 5 adults affected by diabetes, there is an urgent focus on early detection and better glycemic control, making CGMs an increasingly adopted solution. Under Vision 2030, Saudi Arabia has prioritized digital health and chronic disease prevention, encouraging hospitals and specialty clinics to incorporate CGM systems into diabetes care protocols.
Key Continuous Glucose Monitoring Devices Company Insights
The continuous glucose monitoring devices industry is highly competitive, with key players such as Abbott Laboratories, DexCom, Inc., and Medtronic plc holding significant positions. The major companies undertake various organic and inorganic strategies such as product introduction, collaborations, and regional expansion to serve the unmet needs of their customers.
Key Continuous Glucose Monitoring Devices Companies:
The following key companies have been profiled for this study on the continuous glucose monitoring devices market.
-
DexCom, Inc.
-
Abbott Laboratories
-
Medtronic plc
-
Sensonics, Inc.
-
Sinocare, Inc. (iCan CGM)
-
i-SENS, Inc.
-
Zhejiang POCTech Co., Ltd.
-
GlucoRx Limited (AiDEX, Vixxa)
-
F. Hoffmann-La Roche Ltd.
-
Nemaura
-
Bionime (RIGHTEST iFree CGM)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (DexCom, Inc.; Abbott Laboratories; Medtronic plc; F. Hoffmann-La Roche Ltd.; Insulet Corporation)
- Focus on expanding comprehensive CGM portfolios comprising real-time CGM (rtCGM), intermittently scanned CGM (isCGM), integrated insulin pump-CGM ecosystems, and AI-enabled diabetes management platforms. Emphasize strategic collaborations with insulin pump manufacturers, digital health companies, healthcare providers, and payers to strengthen reimbursement coverage, expand remote patient monitoring capabilities, and enhance connected diabetes care.
- Strong global brand recognition, extensive reimbursement coverage, well-established distribution networks, and large installed patient bases create significant recurring revenue through sensor replacement cycles. Robust R&D capabilities and integrated diabetes ecosystems combining CGM, insulin delivery, mobile applications, and cloud-based analytics strengthen customer retention and support long-term market leadership.
- High R&D expenditure, stringent regulatory requirements, and continuous clinical validation increase development costs and extend product launch timelines. Premium device pricing and dependence on reimbursement policies may restrict adoption in cost-sensitive and emerging markets, while maintaining cybersecurity, interoperability, and software compliance adds operational complexity.
Emerging Players (Senseonics Holdings, Inc.; Tandem Diabetes Care; Ascensia Diabetes Care (PHC Holdings); AgaMatrix, Inc.; GlucoRx Limited; Zhejiang POCTech Co., Ltd.; i-SENS, Inc.)
- Focus on developing differentiated CGM technologies including long-wear implantable sensors, cost-effective wearable CGM systems, smartphone-first monitoring platforms, and AI-enabled glucose analytics. Prioritize expansion through regional distribution partnerships, digital health integration, telemedicine compatibility, and targeted commercialization in underserved and emerging markets to improve accessibility and affordability.
- Faster innovation cycles and flexible product development enable rapid adoption of advanced sensor technologies, longer wear durations, enhanced connectivity, and software upgrades. Their focus on affordability, niche patient populations, and localized market strategies creates opportunities to expand adoption where premium systems have limited penetration.
- Limited financial resources, smaller commercial infrastructure, and lower brand recognition restrict their ability to compete with established manufacturers for large reimbursement contracts and healthcare system tenders. Achieving global regulatory approvals, generating long-term clinical evidence, and scaling manufacturing capacity remain key challenges that may delay broader market expansion.
Recent Developments
-
In April 2025, DexCom received U.S. Food and Drug Administration (FDA) clearance for its Dexcom G7 15 Day Continuous Glucose Monitoring System for individuals over 18 years of age with diabetes in the U.S.
-
In June 2025, U.S. Health Secretary Robert F. Kennedy Jr. announced that the Department of Health and Human Services will roll out a major federal campaign encouraging the adoption of wearable health monitors, including CGMs, under the "Making America Healthy Again" initiative. This public health push aims to reduce diabetes-related healthcare costs by promoting proactive self-monitoring through devices.
-
In September 2024, Senseonics received FDA approval for the Eversense 365, the first implantable CGM lasting up to 1 year-doubling sensor longevity compared to its predecessor. This device qualifies as an iCGM, that allows integration with integration pumps.
-
In July 2024, Medtronic plc received FDA approval for their Simplera CGM device, which is designed to connect the company’s Smart Multiple Daily Injection System with InPen.
-
In March 2024, DexCom, Inc. received the U.S. FDA approval for Stelo, an over the counter (OTC) CGM tailored for non-insulin-using Type 2 diabetics and wellness users. This device has a 15-day sensor life and is purchasable without a prescription.
-
In January 2024, Abbott Laboratories announced that its FreeStyle Libre 2 Plus sensor can be integrated with Tandem Diabetes Care’s Tandem t:slim X2 insulin pump users. This allows Tandem’s Control-IQ hybrid closed-loop technology to integrate with Abbott’s 15-day CGM sensor.
Continuous Glucose Monitoring Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 13.4 billion
Estimated market size in 2026
USD 15.5 billion
Projected market size by 2033
USD 41.4 billion
Growth rate
CAGR of 15.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, connectivity, indication, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Mexico; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
DexCom, Inc.; Abbott Laboratories; Medtronic plc; Senseonics Holdings, Inc.; Insulet Corporation; Tandem Diabetes Care; Ascenia Diabetes Care (subsidiary of PHC Holdings); AgaMatrix, Inc.; GlucoRx Limited; Zhejiang POCTech Co.,Ltd.; i-SENS, Inc.; F. Hoffmann-La Roche Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Continuous Glucose Monitoring Devices Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the study, Grand View Research has segmented the continuous glucose monitoring devices market report based on product, connectivity, indication, distribution channel, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Sensors
-
Device/Readers
-
Applicators
-
Transmitters
-
-
Connectivity Outlook (Revenue, USD Million, 2021 - 2033)
-
Bluetooth
-
4G/Cellular
-
Near Field Communication (NFC)
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Type 1 Diabetes
-
Type 2 Diabetes
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmacies
-
E-commerce
-
Other
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The continuous glucose monitoring devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each continuous glucose monitoring devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Sensor
Revenue is primarily generated through the recurring sale of disposable or semi-disposable glucose sensors that continuously measure interstitial glucose levels. Manufacturers benefit from subscription-like replacement cycles, premium sensor chemistries with extended wear duration, improved accuracy, factory calibration technologies, and reimbursement-driven recurring demand.
Transmitters
Revenue is derived from reusable transmitters that wirelessly transmit glucose readings from the sensor to compatible receivers or smart devices. Companies generate income through premium rechargeable transmitters, enhanced battery life, firmware upgrades, connectivity enhancements, and replacement purchases after product lifecycle completion.
Applicators
Revenue is captured through single-use sterile applicators designed for accurate and minimally invasive sensor insertion. Market participants monetize disposable insertion devices, ergonomic applicator innovations that improve patient comfort, and bundled sales with sensor kits.
Device/Readers
Revenue is generated through handheld readers and dedicated monitoring devices that display real-time glucose values, trends, alerts, and historical reports. Companies capture value from hardware sales, integrated diabetes management software, cloud synchronization capabilities, and software updates that enhance patient engagement and clinical decision-making.
Segment - Connectivity
Revenue capture definition
Bluetooth
Revenue is generated through CGM systems equipped with Bluetooth connectivity, enabling real-time wireless communication with smartphones, smartwatches, insulin pumps, and diabetes management platforms. Value is captured through premium connected devices, mobile applications, cloud-based monitoring subscriptions, and digital health ecosystem integration.
4G/Cellular
Revenue is derived from CGM devices incorporating embedded cellular connectivity for direct data transmission without requiring a paired smartphone. Manufacturers monetize integrated communication modules, remote patient monitoring capabilities, telehealth integration, and recurring connectivity service subscriptions where applicable.
NFC (Near Field Communication)
Revenue flows from intermittently scanned CGM systems utilizing NFC technology to retrieve glucose data through compatible readers or smartphones. Companies generate income through NFC-enabled sensors, proprietary scanning devices, mobile application integration, and replacement sensor purchases driven by routine wear cycles.
Segment - Indication
Revenue capture definition
Type 1 Diabetes
Revenue is derived from essential, cost-effective imaging platforms that rely purely on high-contrast structural grayscale displays for anatomical modeling. Revenue streams are concentrated on low-to-mid-tier hardware units, standard high-definition monitors, and core structural measurement tools primarily targeted at emerging markets or basic triaging clinics.
Type 2 Diabetes
Revenue is generated through advanced systems capable of real-time Color Flow Mapping (CFM) superimposed onto 2D or 3D anatomical structures to visually track blood flow direction and turbulence. Manufacturers maximize returns on high-performance graphics-processing hardware, high-end color-calibrated medical displays, and advanced color-Doppler software packages optimized for complex congenital and valvular heart disease analysis.
Segment - Distribution Channel
Revenue capture definition
Pharmacies
Revenue is secured through retail and hospital pharmacy networks supplying CGM sensors, transmitters, and readers directly to patients. Manufacturers benefit from large prescription volumes, reimbursement-driven dispensing, recurring refill purchases, and partnerships with national pharmacy chains.
E-Commerce
Revenue is generated through online sales platforms, manufacturer-owned websites, and digital pharmacies offering CGM devices and accessories. Companies capture value through direct-to-consumer sales, subscription-based sensor replenishment programs, bundled product offerings, and digital customer engagement.
Others
Revenue is captured through alternative distribution channels, including hospitals, diabetes specialty clinics, distributors, durable medical equipment (DME) providers, and government procurement programs. Market participants benefit from institutional purchasing agreements, bulk procurement contracts, and integrated diabetes care partnerships.
Estimation Model
Step
Guiding Question
Process Steps
Data Sources
Scope Definition
What is being studied?
1. Definition of CGM device market and product categories. 2. Segment the market by product, connectivity, indication, distribution channel, and geography. 3. Establish study scope, forecast period (2020-2030), and review boundaries. 4. Establish geographic coverage and forecast model.
WHO, IDF Diabetes Atlas, CDC
Build the Product Base
How large is the total addressable market?
1. Estimate the global diabetes population by indication. 2. Assess the installed base and development base of CGM devices across regions. 3. Analyze annual CGM device shipments, replacement frequency, and new patient adoption. 4. Model new patient adoption, replacement trends, and total device base.
WHO, IDF Diabetes Atlas, manufacturer reports, company annual reports
Estimate Penetration
What proportion of diabetes patients are adopting CGM devices?
1. Evaluate CGM penetration among Type 1 and Type 2 diabetes populations. 2. Assess adoption of real‑time CGM (rtCGM) versus intermittently scanned CGM (isCGM). 3. Analyze reimbursement systems, pricing trends, and adoption drivers. 4. Model adoption and emerging behavioral trends.
WHO, IDF Diabetes Atlas, physician surveys, company presentations, regulatory databases
Revenue Conversion
How do installed devices and recurring consumables translate into market revenue?
1. Determine ASPs for sensors, transmitters, monitors, and other consumables. 2. Calculate recurring revenue from sensor replacement cycles and accuracy claims. 3. Estimate revenue from new device sales, replacement units, and consumables. 4. Model total market revenue, volume, and value trends.
Manufacturer data, procurement databases, distributor pricing data, company reports
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Volume Analysis by Product Segment
Conducted a comprehensive volume analysis of the global CGM devices market across key product categories, including sensors, transmitters, applicators, and readers/devices, covering annual unit sales from 2021 to 2033. The analysis evaluated historical and forecast shipment volumes, product replacement cycles, average sensor wear duration, reusable component lifecycles, adoption trends across real-time CGM (rtCGM) and intermittently scanned CGM (isCGM) systems, and regional demand patterns. It further assessed product mix evolution, recurring sensor consumption, technological advancements extending wear time, and the impact of reimbursement expansion and new patient adoption on annual unit demand.
Enables stakeholders to quantify product-level demand, understand recurring revenue drivers, and identify high-growth product categories across the CGM ecosystem. The study supports manufacturing capacity planning, inventory optimization, supply chain management, pricing strategies, and long-term revenue forecasting by highlighting shipment trends and replacement-driven market dynamics.
BGM vs. CGM Device Adoption Rates, by Region
Conducted a detailed comparative assessment of Blood Glucose Monitoring (BGM) and Continuous Glucose Monitoring (CGM) adoption across major regions. The analysis evaluated transition trends from conventional fingerstick monitoring to continuous glucose monitoring, considering factors such as diabetes prevalence, reimbursement coverage, healthcare infrastructure, physician prescribing behavior, patient awareness, affordability, and regulatory support. It also examined adoption differences across Type 1 and Type 2 diabetes populations, regional penetration rates, and future conversion opportunities.
Enables stakeholders to understand regional technology transition trends and identify markets with the highest CGM conversion potential. The study supports regional expansion planning, commercialization strategies, reimbursement prioritization, investment decisions, and product positioning by identifying barriers and opportunities influencing CGM adoption over traditional BGM systems.
Disease Demographics, by Country
Conducted an in-depth assessment of diabetes epidemiology across major countries, covering Type 1 and Type 2 diabetes prevalence, incidence, diagnosed and undiagnosed patient populations, insulin-treated populations, age-wise disease distribution, and population growth trends influencing CGM demand. The study further evaluated obesity prevalence, aging demographics, diabetes-related complications, healthcare expenditure, reimbursement accessibility, and country-specific disease burden to estimate the addressable patient population and long-term market potential.
Enables stakeholders to identify high-opportunity countries based on disease burden and patient demographics, facilitating evidence-based market prioritization and resource allocation. The study supports country-level forecasting, market entry strategies, reimbursement planning, commercial expansion, and targeted product development by linking epidemiological trends with future CGM adoption potential.
Frequently Asked Questions About This Report
The global continuous glucose monitoring devices market size was estimated at USD 13.4 billion in 2025 and is expected to reach USD 15.5 billion in 2026.
Some key players operating in the continuous glucose monitoring devices market include Dexcom, Inc., Abbott, Medtronic, Senseonics Holdings, Inc., i-Sens, Inc. and, F. Hoffmann La Roche Ltd., among others.
Key factors that are driving the continuous glucose monitoring devices market growth include growing cases of diabetes, coupled with the increasing adoption of continuous glucose monitoring (CGM) devices. This growth is also attributed to clinical needs, technological innovation, and shifting care models.
The sensors segment led with a 62.8% revenue share in 2025.
Bluetooth held the largest revenue share 57.3% in 2025.
Type 1 diabetes held the largest share (over 64.9%) in 2025.
The pharmacies segment led with a 59.4% revenue share in 2025.
The global continuous glucose monitoring devices market is expected to grow at a compound annual growth rate of 15.1% from 2026 to 2033 to reach USD 41.4 billion by 2033.
North America dominated the market with a share of 63.3% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


