
- Home
- »
- Next Generation Technologies
- »
-
Cloud Computing Market Size And Share Report, 2026-2033GVR Report cover
![Cloud Computing Market (2026 - 2033)Report]()
Cloud Computing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service (IaaS, PaaS, SaaS), By Deployment (Public, Private, Hybrid), By Workload (Resource Management), By Enterprise Size, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$943.6BMarket Estimate, 2026
$1,188.1BMarket Forecast, 2033
$3,349.6BCAGR, 2026–2033
16.0%Cloud Computing Market Summary
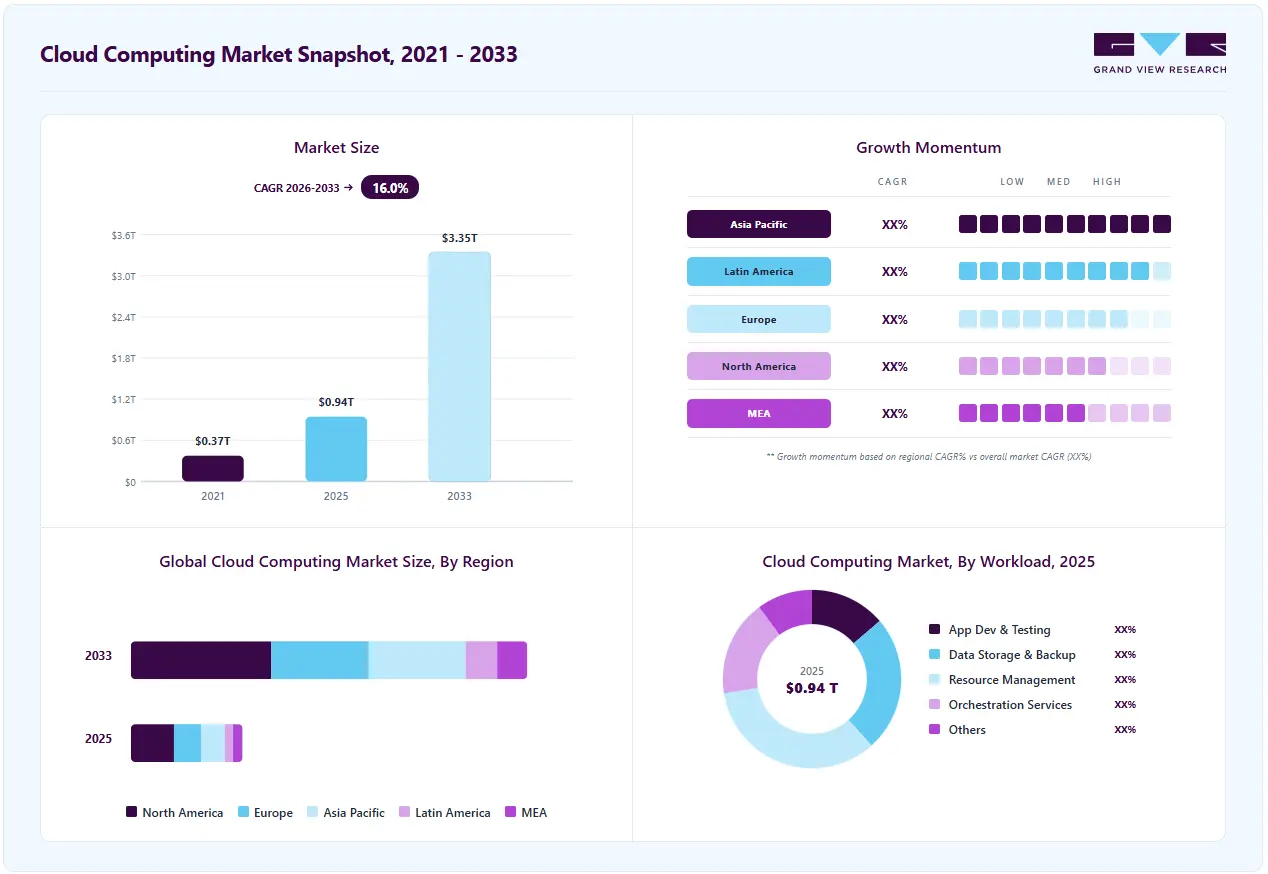
The global cloud computing market size was valued at USD 943.6 billion in 2025 and is projected to grow from USD 1,188.1 billion in 2026 to USD 3,349.6 billion in 2033, at a CAGR of 16.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.6% in 2025. Market growth is accelerating due to the swift adoption of artificial intelligence (AI), generative AI, and cloud-based enterprise applications, which increase the demand for scalable computing, data storage, and infrastructure optimized for AI.
Key Market Trends & Insights
- By service: Software as a Service (SaaS) held the largest revenue share of 53.6% in 2025.
- By workload: Resource management held the largest market share of 34.0% in 2025.
- By deployment: Public cloud held the largest market share of 52.6% in 2025.
- By enterprise size: Large enterprise segment accounted for the largest revenue share in 2025.
- By end use: BFSI segment accounted for the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (38.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 943.6 Billion
- Estimated market size in 2026: USD 1,188.1 Billion
- Projected market size by 2033: USD 3,349.6 Billion
- CAGR (2026-2033): 16.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Businesses across various industries are modernizing their applications, consolidating data environments, and transitioning to consumption-based IT models. These models offer greater scalability and reduce the need for large upfront infrastructure investments. The rapid adoption of artificial intelligence (AI), machine learning, and advanced analytics is driving increased demand for cloud computing services. AI workloads require significant computing power, high-performance GPUs, scalable storage, and flexible infrastructure, making cloud platforms essential for training and deploying modern AI models.The growing adoption of hybrid and multicloud architectures is another key driver of the cloud computing industry. Companies are distributing workloads across multiple cloud providers and their private infrastructures to enhance resilience, optimize performance, manage costs, and lessen reliance on individual vendors. Advances in cloud management platforms, container orchestration, Kubernetes-based environments, and cross-cloud networking have made these architectures easier to implement.

The expansion of edge computing and Internet of Things (IoT) ecosystems is creating additional demand for distributed cloud infrastructure. Connected manufacturing facilities, smart cities, autonomous systems, healthcare environments, and distributed retail operations increasingly require real-time data processing with minimal latency. Edge-cloud architectures meet these needs by combining centralized cloud resources with localized computing at network edges or on connected devices. As businesses deploy more connected devices and data-intensive applications, the integration of edge computing with public, private, and hybrid cloud environments is expected to broaden the range of cloud computing use cases.
Security, regulatory compliance, and data sovereignty are becoming increasingly vital in enterprise cloud adoption. Cloud providers are enhancing their offerings with zero-trust security, automated threat detection, identity management, encryption, and compliance capabilities to meet the rising cybersecurity demands. Simultaneously, governments and regulated industries are placing a stronger focus on data residency and control over digital infrastructure.
Market Dynamics
The cloud computing market is being shaped by the rapid adoption of artificial intelligence (AI), generative AI, cloud-native applications, and data-intensive workloads, which are increasing demand for scalable computing, storage, networking, and AI-optimized infrastructure. The expansion of hybrid and multicloud environments is further supporting demand for interoperable cloud platforms, while growing investments in data centers and sovereign cloud infrastructure are broadening regional deployment opportunities. However, data security, regulatory compliance, data sovereignty requirements, vendor lock-in, and the complexity of managing distributed cloud environments continue to constrain adoption in certain organizations. At the same time, the increasing deployment of AI agents, confidential computing, edge cloud infrastructure, industry-specific cloud platforms, and sovereign cloud services is creating new opportunities for cloud providers to develop specialized offerings and capture demand from enterprises with increasingly complex workloads.
The rapid adoption of artificial intelligence (AI), generative AI, and machine learning is emerging as a major driver of the cloud computing market. Training and deploying increasingly sophisticated AI models requires substantial computing power, high-performance GPUs, scalable storage, and flexible infrastructure capable of dynamically accommodating fluctuating workloads. Cloud platforms provide enterprises with on-demand access to these resources without requiring comparable investments in physical infrastructure. As organizations integrate AI into applications, customer services, business analytics, software development, and operational workflows, demand for cloud-based computing and data services is increasing. The increasing relationship between AI adoption and cloud infrastructure demand was driven by demand across workloads.
The impact of AI adoption was also evident in the rapid increase in cloud infrastructure investment. In July 2026, Microsoft reported that it had added another gigawatt of data center capacity during the fourth quarter of fiscal 2026 and remained on track to approximately double its overall capacity within two years. The company also stated that Microsoft Cloud revenue increased, supported by strong demand for Azure and AI applications and services. In addition, Microsoft reported that its fiscal 2026 capital expenditures were driven by growing demand for cloud and AI offerings, with substantial spending directed toward GPUs, CPUs, data center sites, and networking infrastructure. The continued development of generative AI, AI agents, large language models, and AI-enabled enterprise applications is therefore expected to sustain demand for scalable cloud computing infrastructure throughout the forecast period.
Data security, regulatory compliance, and data sovereignty concerns can restrain cloud computing market growth, particularly among organizations handling sensitive financial, healthcare, government, and enterprise information. Migrating critical workloads to third-party cloud environments increases requirements for identity and access management, encryption, threat monitoring, regulatory compliance, and data governance. Differences in data residency requirements and privacy regulations across countries can further increase operational complexity for multinational organizations. The European Union’s General Data Protection Regulation (GDPR), for instance, establishes requirements governing the processing and transfer of personal data, increasing compliance considerations for organizations operating cloud environments across jurisdictions. Although cloud providers continue to strengthen zero-trust security, automated threat detection, encryption, and compliance capabilities, concerns about unauthorized access, data breaches, service availability, and control over sensitive information can delay cloud migration or prompt organizations to retain certain workloads in private or on-premises environments. These challenges are becoming more significant as governments introduce policies emphasizing greater control over where data is stored, processed, and transferred.
The rapid development of AI-optimized cloud infrastructure presents a significant opportunity for the cloud computing market. AI workloads require specialized computing resources, including GPUs, high-performance networking, accelerated storage, and infrastructure capable of supporting both model training and inference at scale. Cloud providers are consequently expanding AI-ready data center capacity and introducing infrastructure specifically designed for AI-intensive workloads. In April 2026, Google Cloud introduced its eighth-generation Tensor Processing Units (TPUs), as well as new AI-focused compute instances, networking, and storage technologies. It expanded Kubernetes capabilities to support increasingly complex agentic AI workloads. Similarly, Oracle reported in September 2026 that its cloud infrastructure revenue increased, while the company added 850 MW of data center capacity during the quarter. These investments indicate that cloud demand is increasingly extending beyond conventional application hosting toward large-scale AI model development, deployment, and inference.
Analyst Perspective
The cloud computing market is evolving from basic infrastructure migration into a broader foundation for enterprise digital operations. Growing adoption of AI, machine learning, data analytics, application modernization, and cloud-native development is driving demand for scalable computing and storage. Hybrid and multicloud architectures are enabling enterprises to balance performance, flexibility, security, and cost across environments. Cloud providers are expanding into specialized AI infrastructure, managed services, and industry-specific solutions to capture higher-value workloads. Cost optimization and data sovereignty are gaining importance amid rising cloud spending and regulatory complexity. Competition will increasingly focus on integrated platforms, AI capabilities, security, and efficient workload management, creating opportunities for cloud providers, specialized vendors, and technology partners.
Service Insights
The Software as a Service (SaaS) segment dominated the cloud computing industry, accounting for a revenue share at 53.6% in 2025. SaaS adoption continues to benefit from the shift toward subscription-based software models, which reduce upfront licensing costs and simplify maintenance, upgrades, and deployment. The ability to access applications through flexible, recurring payment structures is particularly attractive to organizations seeking greater cost predictability. In addition, SaaS platforms allow businesses to quickly add or reduce users and functionality as requirements change, supporting adoption across functions such as customer relationship management, human resources, finance, and collaboration.
The Infrastructure as a Service (IaaS) segment is anticipated to grow at the fastest CAGR during the forecast period. Enterprises are increasingly replacing or supplementing traditional on-premise infrastructure with cloud-based computing, storage, and networking resources to improve scalability and operational agility. IaaS enables rapid provisioning of infrastructure without significant upfront investment, allowing organizations to support fluctuating workloads and accelerate application deployment. Its growing integration with cloud-native development, containers, microservices, and AI workloads is further increasing demand for flexible and scalable infrastructure environments.
Workload Insights
The resource management segment dominated the cloud computing market, accounting for a revenue share at 34.0% in 2025. The growing complexity of enterprise IT environments is increasing the need for centralized control over cloud resources. Organizations operating across public, private, and on-premise environments require greater visibility into infrastructure utilization, provisioning, and performance. Resource management solutions help address these requirements by enabling automated allocation of computing, storage, and networking resources while supporting consistent governance across distributed environments. As hybrid and multi-cloud deployments become more common, organizations are placing greater emphasis on improving resource utilization and maintaining operational control across diverse infrastructure environments.
The application development & testing segment is anticipated to grow at the fastest CAGR during the forecast period. The increasing adoption of DevOps practices is strengthening the role of cloud platforms in software development, testing, and deployment workflows. Cloud-based environments enable development teams to provision resources on demand, automate testing, and integrate continuous integration and continuous delivery into a unified workflow. This approach can shorten development cycles, improve deployment consistency, and reduce dependence on manual infrastructure management. As enterprises modernize applications and expand cloud-native development, demand for cloud-based development and testing environments is expected to increase.
Deployment Insights
The public segment accounted for the largest revenue share at 52.6% in 2025. Its widespread adoption is largely associated with the ability to access computing infrastructure without the capital and operational commitments required to build and maintain private data centers. Organizations can obtain servers, storage, networking, and other resources on demand through subscription or pay-as-you-go models, allowing IT expenditure to better align with actual requirements. Public cloud also enables faster deployment and capacity expansion, making it suitable for businesses with fluctuating workloads and limited internal infrastructure capabilities. These advantages are supporting adoption across startups, small and medium-sized enterprises, and large organizations seeking greater flexibility in technology investments.
The hybrid segment is expected to register significant growth during the forecast period as enterprises seek greater flexibility in distributing workloads across cloud and on-premise environments. Instead of relying entirely on a single infrastructure model, organizations can retain sensitive or business-critical workloads in controlled environments while using public cloud resources for scalable or variable workloads. This approach provides greater control over data, security, and compliance while preserving the scalability of cloud infrastructure. The increasing adoption of multi-cloud strategies is further strengthening demand for hybrid architectures, particularly among enterprises seeking to improve resilience, avoid overreliance on individual providers, and optimize infrastructure utilization.
Enterprise Size Insights
The large enterprise segment dominated the market with the largest revenue share in 2025. Large organizations are undertaking extensive digital transformation initiatives that require scalable infrastructure, distributed computing capabilities, and greater flexibility in managing enterprise workloads. Cloud adoption is enabling these organizations to modernize legacy systems, transition toward microservices and cloud-native architectures, and support applications across geographically dispersed operations. The growing need to deliver digital customer experiences, automate business processes, and integrate advanced technologies such as artificial intelligence and data analytics is further encouraging enterprises to move critical workloads to cloud environments. In addition, cloud platforms provide the flexibility required to expand infrastructure as business and technology requirements evolve.
The small and medium enterprises segment is expected to register significant growth during the forecast period. Cloud computing provides SMEs with access to enterprise-grade infrastructure and software without requiring substantial investments in servers, data centers, and specialized IT resources. Subscription and pay-as-you-go models allow smaller organizations to align technology expenditure with actual usage and business conditions. This financial flexibility is particularly valuable for companies operating with limited capital or variable workloads. Faster deployment, reduced infrastructure management requirements, and access to scalable digital tools are further enabling SMEs to adopt cloud technologies and compete more effectively without having to build extensive in-house IT infrastructure.
End Use Insights
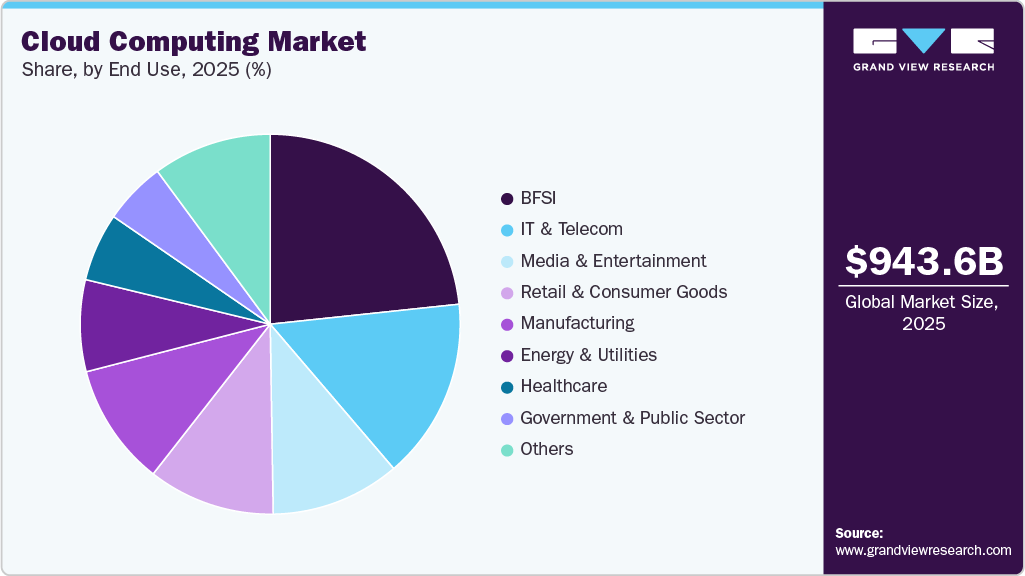
The BFSI segment dominated the cloud computing industry, accounting for the largest revenue share in 2025. Financial institutions are increasingly using cloud infrastructure to modernize legacy systems while maintaining stringent requirements for data security, regulatory compliance, and service availability. Hybrid cloud architectures are particularly relevant, allowing organizations to retain sensitive financial and customer information within controlled environments while using public cloud resources for analytics, customer-facing applications, and digital services. The scalability of cloud platforms also supports the growing volume of digital transactions and data-intensive financial applications. As banks and other financial institutions expand digital banking, fraud detection, and automated financial services, cloud adoption is becoming an important component of their technology modernization strategies.
The manufacturing segment is expected to register significant growth during the forecast period as manufacturers accelerate the transition toward connected and data-driven production environments. Cloud platforms provide a centralized foundation for integrating data generated by industrial equipment, IoT devices, and production systems, enabling real-time monitoring and analysis across facilities. This supports applications such as predictive maintenance, digital twins, production optimization, and remote equipment management. Cloud-based infrastructure also facilitates collaboration between manufacturing sites and enables organizations to scale digital initiatives without deploying extensive local IT infrastructure. As Industry 4.0 adoption deepens, the growing need to connect operational data to analytics and automation systems is expected to drive cloud deployment across manufacturing operations further.
Regional Insights
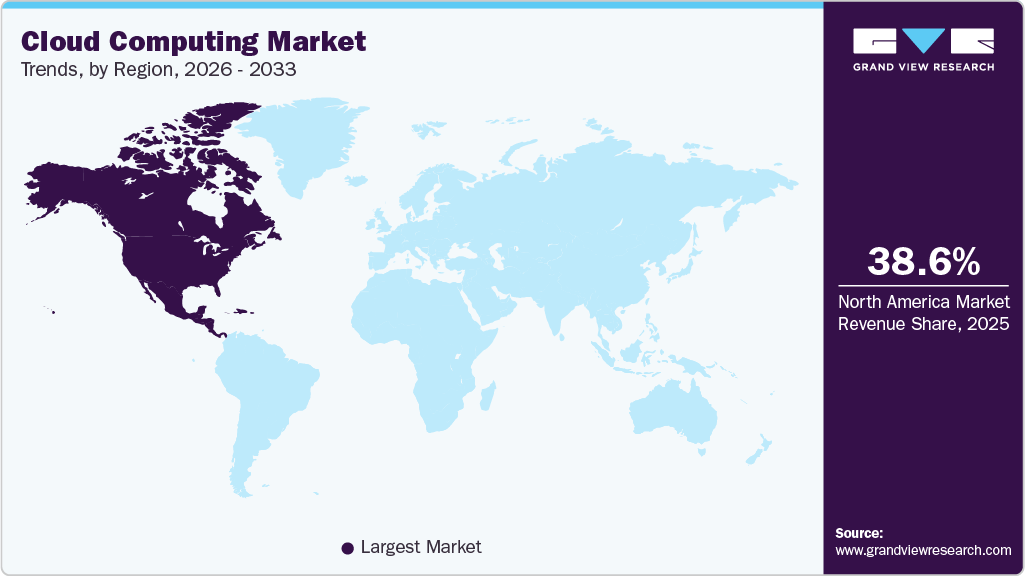
North America dominated the cloud computing market with a revenue share of 38.6% in 2025, supported by the region’s mature digital infrastructure, strong presence of hyperscale cloud providers, and early adoption of advanced cloud technologies. Enterprises are increasingly moving AI, machine learning, data analytics, and automation workloads to cloud environments, creating sustained demand for scalable computing and storage capacity. Large investments in data center infrastructure are further strengthening the region’s capacity to support high-performance, data-intensive workloads. In addition, widespread adoption of DevOps, cloud-native application development, and hybrid and multi-cloud architectures is encouraging organizations to expand cloud usage beyond basic infrastructure migration. The combination of technological maturity, enterprise cloud spending, and continued investment in AI-ready infrastructure is expected to reinforce North America’s position throughout the forecast period.
U.S. Cloud Computing Market Trends
The U.S. cloud computing industry accounted for the largest share of North America in 2025, supported by widespread enterprise cloud adoption and continued modernization of government IT infrastructure. Federal agencies and defense organizations are increasingly transitioning legacy systems and critical workloads to secure cloud environments to improve scalability, resilience, and operational efficiency. Government cloud initiatives are also strengthening demand for infrastructure capable of meeting stringent security, data protection, and compliance requirements. In parallel, established cloud infrastructure capabilities and strong adoption across commercial industries are expanding the range of workloads being migrated to cloud platforms. The combination of public-sector modernization, enterprise digital transformation, and demand for secure and compliant cloud environments is expected to sustain cloud investment in the U.S. through the forecast period.
Europe Cloud Computing Market Trends
The cloud computing industry in Europe is anticipated to grow considerably from 2026 to 2033, supported by the region’s ongoing digital transformation and increasing emphasis on data protection and sovereignty. Stringent privacy requirements, including the General Data Protection Regulation (GDPR), are influencing how organizations select, deploy, and manage cloud infrastructure, increasing interest in secure and compliant cloud environments. Enterprises are also adopting hybrid and private cloud architectures to maintain greater control over sensitive data while accessing the scalability and advanced computing capabilities of public cloud platforms. In addition, the growing use of cloud-based analytics, artificial intelligence, and application modernization is expanding enterprise workloads across the region. These developments are encouraging cloud providers to strengthen security, compliance, and localized infrastructure capabilities.
The UK cloud computing market is expected to expand rapidly over the forecast period, supported by strong adoption across financial services and other highly regulated industries. Banks and insurance companies are increasingly modernizing legacy technology infrastructure to support digital banking, real-time analytics, automated services, and improved customer experiences. Cloud platforms also provide financial institutions with greater flexibility to deploy and scale applications while strengthening data management and cybersecurity capabilities. As regulatory expectations around operational resilience and data protection increase, demand is shifting toward cloud environments that can combine scalability with robust security and governance. Continued digitalization across the UK financial ecosystem is therefore expected to remain a key driver of cloud adoption.
The cloud computing market in Germany accounted for a substantial share of the European market in 2025, supported by strong adoption across the manufacturing and automotive industries. German manufacturers are increasingly integrating cloud infrastructure into Industry 4.0 initiatives, enabling connected production environments, digital twins, IoT-based monitoring, and data-driven operational management. Cloud platforms facilitate the collection and analysis of data from distributed production systems, supporting applications such as predictive maintenance, production optimization, and supply chain management. The country's established industrial base and continued investment in factory digitalization are expected to sustain demand for cloud technologies as manufacturers seek greater visibility, automation, and flexibility across production operations.
Asia Pacific Cloud Computing Market Trends
The cloud computing industry in Asia Pacific accounted for a significant market share in 2025, supported by rapid digitalization across businesses and rising investment in digital infrastructure. Growing adoption among SMEs and startups is creating demand for flexible computing resources that can be deployed without substantial investments in physical IT infrastructure. The expansion of e-commerce and digital services is further increasing requirements for scalable cloud platforms capable of supporting fluctuating workloads and growing volumes of data. In addition, government-led smart-city and digitalization initiatives are encouraging the deployment of cloud-based technologies across public services and urban infrastructure. These developments are strengthening the role of cloud computing as an enabler of digital innovation across the region.
The Japan cloud computing market is expected to grow rapidly in the coming years, driven by increasing integration of AI, robotics, and automation across manufacturing, healthcare, and logistics. Cloud infrastructure provides the computing capacity and data management capabilities required to support advanced analytics, connected equipment, and increasingly automated operations. The growing use of edge computing alongside cloud platforms is also enabling organizations to process data closer to operational environments while retaining centralized cloud capabilities. These trends are supporting the development of smart manufacturing and advanced robotics applications and are expected to sustain cloud investment across Japan.
The cloud computing market in China held a substantial share in 2025, supported by the country's extensive digital infrastructure and widespread deployment of 5G and IoT technologies. The convergence of high-speed connectivity and cloud platforms is enabling large-scale data generation and real-time processing across industrial, commercial, and public-sector applications. Cloud infrastructure is increasingly supporting smart-city platforms, connected vehicles, digital payments, and other data-intensive services that require high scalability and availability. Continued development of digital ecosystems and enterprise technology adoption is expected to further expand demand for cloud computing capabilities in China.
Key Cloud Computing Company Insights
Key players operating in the cloud computing industry include Amazon Web Services (AWS); Microsoft Azure; Google Cloud Platform (GCP); Oracle Cloud; Salesforce, Inc.; and Alibaba Cloud. Competition is increasingly centered on expanding cloud infrastructure capabilities, strengthening AI and data analytics offerings, and broadening integrated platform services. Companies are pursuing product and service enhancements, strategic partnerships, technology collaborations, and agreements to expand their capabilities and address evolving enterprise requirements. Investments in AI-ready infrastructure, industry-specific cloud solutions, hybrid and multi-cloud management, and security capabilities are also becoming important areas of competitive differentiation. As enterprises place greater emphasis on scalability, cost optimization, data governance, and workload flexibility, cloud providers are increasingly focused on developing comprehensive ecosystems that can support a wider range of workloads and long-term digital transformation initiatives.
Key Cloud Computing Companies
The following key companies have been profiled for this study of the cloud computing market.
-
Alibaba Cloud
-
Amazon Web Services, Inc.
-
CloudHesive
-
Coastal Cloud
-
DigitalOcean
-
Google
-
GroundCloud
-
IBM
-
Microsoft Azure
-
Oracle Cloud
-
Rackspace Technology, Inc.
-
Salesforce, Inc.
-
Tencent
-
VMware LLC (Broadcom)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Amazon.com Inc., Google LLC, Microsoft Corporation, Workday, Inc., Adobe Inc., Alibaba Group)
- Expanding hyperscale data center infrastructure and global cloud regions
- Investing aggressively in AI, generative AI, and custom semiconductor capabilities
- Strengthening hybrid and multi-cloud offerings through acquisitions and partnerships
- Enhancing enterprise-focused managed services, cybersecurity, and analytics portfolios.
- Strong global brand recognition and large enterprise customer base
- Extensive integrated cloud ecosystems with broad service portfolios
- Significant economies of scale enabling competitive pricing and continuous innovation
- Advanced AI, automation, and security capabilities supported by high R&D investments.
- High capital expenditure requirements for infrastructure expansion and AI workloads
- Increasing regulatory scrutiny related to data sovereignty, cybersecurity, and antitrust concerns
- Vendor lock-in concerns may discourage some enterprise customers
- Intensifying competition leading to pricing pressure and rising operational costs
Emerging Players (CloudHesive, Rackspace Technology, Inc.)
- Focusing on niche and industry-specific cloud solutions
- Expanding regional cloud infrastructure and sovereign cloud offerings
- Forming strategic alliances with telecom operators, governments, and enterprises
- Prioritizing hybrid cloud, edge computing, and AI-enabled business applications.
- Greater flexibility in addressing specialized enterprise and regional requirements
- Strong presence in selected industries such as finance, healthcare, and government
- Competitive pricing strategies and customized service models
- Ability to differentiate through localized compliance and industry expertise.
- Limited global scale compared to hyperscale cloud leaders
- Lower brand visibility and smaller partner ecosystems
- Challenges in matching the pace of innovation and infrastructure investments of dominant providers
- Difficulty in gaining large-scale enterprise market share amid strong competition from established hyperscalers.
Recent Developments
-
In September 2026, Oracle reported that cloud infrastructure revenue increased 121% year over year to USD 7.4 billion in the first quarter of fiscal 2027. The company also added 850 MW of data center capacity during the quarter, highlighting continued infrastructure investment to support AI and cloud workloads.
-
In September 2026, Equinix introduced Equinix Fabric One, a managed connectivity service designed to provide any-to-any connections across enterprise, cloud, and AI environments. The offering incorporates open connectivity specifications developed by AWS and Google Cloud, supporting more streamlined networking across distributed infrastructure.
-
In July 2026, AWS made AWS Interconnect - multicloud with Oracle Cloud Infrastructure (OCI) generally available, enabling customers to establish private, resilient, high-speed connections between AWS and OCI workloads. The service strengthens multicloud interoperability and reduces the complexity of managing connections across cloud providers.
-
In June 2026, Alibaba Cloud announced that its global infrastructure had expanded to 105 availability zones across 32 regions, following additional data center investments in Japan, Malaysia, France, and Mexico. The expansion strengthens the provider's ability to deliver scalable cloud and AI infrastructure while addressing regional data privacy and sovereignty requirements.
-
In June 2026, Google Cloud announced a collaboration with Apple to support Apple Private Cloud Compute (PCC) infrastructure on Google Cloud. The collaboration combines Google Cloud's Confidential Computing technologies with Apple's privacy and security requirements, supporting sensitive AI workloads with stronger data protection and verifiable security controls.
-
In April 2026, Google Cloud introduced new AI infrastructure capabilities, including eighth-generation Tensor Processing Units (TPUs), new compute instances, AI-focused networking and storage technologies, and expanded Kubernetes capabilities. The portfolio is designed to support increasingly complex agentic AI workloads while improving computing performance, scalability, and infrastructure efficiency.
Cloud Computing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 943.6 billion
Estimated market size in 2026
USD 1,188.1 billion
Projected market size by 2033
USD 3,349.6 billion
Growth rate
CAGR of 16.0% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, workload, deployment, enterprise size, end use, and region
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Alibaba Cloud; Amazon Web Services, Inc.; CloudHesive; Coastal Cloud; DigitalOcean; Google; GroundCloud; IBM; Microsoft Azure; Oracle Cloud; Rackspace Technology, Inc.; Salesforce, Inc.; Tencent; VMware LLC (Broadcom)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cloud Computing Market Report Segmentation
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the cloud computing market report based on service, workload, deployment, enterprise size, end use, and region:
-
Service Outlook (Revenue, USD Billion, 2021 - 2033)
-
Infrastructure as a Service (IaaS)
-
Platform as a Service (PaaS)
-
Software as a Service (SaaS)
-
Workload Outlook (Revenue, USD Billion, 2021 - 2033)
-
Application Development & Testing
-
Data Storage & Backup
-
Resource Management
-
Orchestration Services
-
Others
-
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
Public
-
Private
-
Hybrid
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Small & Medium Enterprises
-
Large Enterprise
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
BFSI
-
IT & Telecom
-
Retail & Consumer Goods
-
Manufacturing
-
Energy & Utilities
-
Healthcare
-
Media & Entertainment
-
Government & Public Sector
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global cloud computing market is expected to witness a compound annual growth rate of 16.0% from 2026 to 2033 to reach USD 3,349.6 billion by 2033.
North America dominated the global market with the largest revenue share of 38.6% in 2025.
Alibaba Cloud, Amazon Web Services, Inc., CloudHesive, Coastal Cloud, DigitalOcean, Google, GroundCloud, IBM, Microsoft Azure, Oracle Cloud, Rackspace Technology, Inc., Salesforce, Inc., Tencent, The Descartes Systems Group Inc., VMware LLC, are some of the prominent players present in the cloud computing market.
Software as a service segment led with a 53.6% revenue share in 2025, while infrastructure as a service is the fastest-growing segment.
Public segment held the highest market share of 52.6% in 2025, while hybrid is the fastest-growing segment.
The resource management segment held the highest market share of 34.0% in 2025, while application development & testing is the fastest-growing segment.
Large enterprise segment dominated the market and accounted for the largest revenue share in 2025.
BFSI segment held the highest market share in 2025, while manufacturing is the fastest-growing segment.
The global cloud computing market size was valued at USD 943.7 billion in 2025 and is estimated at USD 1,188.1 billion in 2026.
Cloud Computing Market By Country
- U.S. Cloud Computing Market
- Canada Cloud Computing Market
- Mexico - North America Cloud Computing Market
- Germany Cloud Computing Market
- France Cloud Computing Market
- Japan Cloud Computing Market
- China Cloud Computing Market
- India Cloud Computing Market
- Australia Cloud Computing Market
- South Korea Cloud Computing Market
- Brazil Cloud Computing Market
- South Africa Cloud Computing Market
- Saudi Arabia Cloud Computing Market
- Uae Cloud Computing Market
- U.K. Cloud Computing Market
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


